Category: Demat Account

  • What Is Collateral Amount In Demat Account?

    What Is Collateral Amount In Demat Account?

    If you hold shares in your Demat account and wish to utilize their value without selling them, it is essential to understand the concept of Collateral Amount in a Demat account. Many people mistake the collateral amount for the account balance, whereas the two are distinct. In this article, we will explain in simple terms how collateral works, where it is used, its benefits, and the key points to consider when utilizing it.

    What Is Collateral Amount In Demat Account? 

    What is the collateral amount in a Demat account? It refers to the margin value you receive upon pledging eligible shares, ETFs, mutual funds, or other approved securities. This amount is not credited to your bank account as cash; instead, it appears as a trading margin. It can be utilized for MTF, Futures & Options (F&O), or other margin trades, subject to the broker’s policy and applicable exchange regulations.

    How does it work?

    When you pledge your eligible shares for margin, they are not sold, and you retain ownership of them. Once the pledge is complete, the broker assigns a collateral value calculated after deducting a haircut which can be used for MTF, Futures & Options (F&O), or other permitted margin trades.

    Example: Suppose you hold eligible shares worth ₹2 lakh in your Demat account and suddenly require additional margin for trading. Instead of selling the shares, you can pledge them for margin. The broker then provides you with collateral value against these shares in accordance with established rules which you can use for permitted trades. This allows you to retain your investments without needing to sell them.

    Why Do Brokers Ask For Collateral? 

    Brokers request collateral to safely provide trading margins to investors. This allows investors to access additional trading facilities without selling their existing investments, while also keeping the broker’s risk under control.

    • To provide trading margin: If an investor wishes to engage in additional trading, the broker provides margin by accepting eligible shares or other approved securities as collateral. This eliminates the need for the investor to inject fresh funds every time.
    • To mitigate broker risk: When a broker extends margin to an investor, the collateral serves as security. In the event of a sudden market downturn or if the investor fails to maintain the required margin, the collateral helps mitigate the broker’s risk.
    • To facilitate Margin Trading Facility (MTF): Under MTF, the broker provides funds for purchases on behalf of the investor. Consequently, the broker requires collateral to ensure there is adequate security backing the funds provided.
    • To meet margin requirements for Futures & Options (F&O): In Futures & Options (F&O) trading, maintaining the margin prescribed by the exchange is mandatory. Eligible collateral can help cover a portion of this margin, although cash margin may also be required in certain cases.
    • To comply with SEBI and exchange regulations: SEBI and stock exchanges have established clear regulations regarding margins and risk management. In accordance with these rules, brokers accept only eligible securities as collateral and provide margin after applying the prescribed ‘haircut’ to them.

    How Does Collateral Work In A Demat Account? 

    The process of creating collateral in a Demat account is completed in a few simple steps.

    Step 1: Select Eligible Shares

    First, your Demat account must hold shares or other securities that are included in the broker’s and exchange’s collateral list. Collateral benefits are available only on eligible securities.

    Step 2: Pledge for Margin

    Next, submit a margin pledge request for those shares via your trading app or the broker’s platform. Once approved, the shares remain in your name but are marked as collateral.

    Step 3: Haircut Application

    After the pledge is processed, the broker applies a specific ‘haircut’ to each security. This determines the value used for collateral purposes.

    Step 4: Collateral Value Realized

    The value remaining after the haircut is applied appears as ‘Collateral Value’ in your trading account. Note that this amount is not cash.

    Step 5: Utilize the Margin

    You can now use the available collateral value for MTF, Futures & Options (F&O), or other permitted margin trades, subject to the broker’s policies.

    Read Also: MTF Pledge Explained

    Collateral Amount Explained With A Real Example 

    Suppose you hold eligible shares worth ₹2,00,000 in your Demat account and pledge them for margin. If a 20% haircut applies to those shares, the collateral value would be calculated as follows.

    DescriptionAmount
    Total value of eligible shares₹2,00,000
    Haircut 20% (₹40,000)
    Available Collateral Value₹1,60,000
    Trading Margin₹1,60,000

    Calculation:

    • ₹2,00,000 × 20% = ₹40,000 (Haircut)
    • ₹2,00,000 − ₹40,000 = ₹1,60,000 (Collateral Value)

    What Is Haircut In Collateral? 

    When accepting collateral, a broker does not provide a margin based on the full market value of your shares. This reduction is known as a “haircut,” and it is determined based on risk.

    What does “haircut” mean?

    A haircut is the percentage that a broker or exchange deducts from a security’s market value to determine its collateral value. Its purpose is to mitigate the risk associated with sudden market fluctuations.

    Why does the haircut vary for different shares?

    Not all shares share the same level of risk and liquidity. Shares prone to high price volatility may attract a higher haircut, whereas relatively stable and highly liquid shares typically have a lower haircut.

    How does a haircut affect collateral value?

    The higher the haircut, the lower the collateral value you receive. This means that two shares with the same market value could yield different available margins if they are subject to different haircuts.

    Share ValueHaircutCollateral Value
    ₹1,00,00010%₹90,000
    ₹1,00,00025%₹75,000

    Which Securities Can Be Used As Collateral? 

    Only those securities are valid as collateral that are included in the eligible collateral lists of SEBI, stock exchanges, and the broker.

    Security Availability as collateral
    Eligible Equity SharesAvailable on most eligible shares
    Exchange Traded Funds (ETFs)Available on many eligible ETFs
    Mutual Fund UnitsAvailable on select eligible schemes.
    Government Securities (G-Secs, T-Bills)widely available
    Sovereign Gold Bonds (SGBs)Available through some brokers
    Corporate Bonds / Debt SecuritiesAvailable on eligible bonds
    Gold ETFsAvailable through several brokers
    Unlisted SharesNot valid as collateral
    Non-Eligible or Restricted SharesNot valid as collateral

    Difference Between Cash Margin And Collateral Margin 

    The purpose of Cash Margin and Collateral Margin is to provide margin for trading, but the mechanism for each is different.

    BaseCash MarginCollateral Margin
    Source of marginCash deposited into the bank accountPledged Eligible Securities
    Requirement for cashThe full amount has to be deposited in cash.You can get margin even without depositing additional cash.
    Haircut Not applicablecome into force
    Impact of Market ValueThe cash value remains stable.The collateral may also change if the value of the securities changes.
    UseUseful for all types of margins.For trades permitted by the broker and in accordance with the rules
    Better for whom?New investors and low-risk takersActive traders who invest for the long term

    Where Can You Use Collateral Amount? 

    Collateral cannot be used universally; its utilization is determined by the broker’s policies and applicable exchange regulations regarding specific trading facilities.

    • Futures Trading: Collateral can be used to meet a portion of the margin requirement in futures trading.
    • Options Selling: Options selling requires margin; eligible collateral can help increase the available margin.
    • Margin Trading Facility (MTF): Under MTF, collateral can be utilized to gain additional buying power.
    • Intraday Trading: Some brokers offer collateral margin facilities for intraday trading as well, subject to their policies.
    • Portfolio Funding: The value of long-term investments can be utilized as trading margin without having to sell the holdings.

    Benefits Of Using Collateral In Demat Account 

    Investors can derive several practical benefits from the effective use of collateral.

    • No need to sell investments: Collateral allows you to utilize the value of your eligible shares without selling them. This ensures your long-term investment remains intact.
    • Better utilization of capital: Instead of deploying additional cash, you can use the value of your existing portfolio as margin. This leads to more efficient capital utilization.
    • Access to additional trading margin: Having collateral available provides access to extra margin when needed, thereby increasing your buying power for trading.
    • Continued receipt of corporate benefits: Pledging shares does not alter their ownership. Consequently, you continue to receive corporate benefits such as dividends, bonus shares, and rights issues where applicable.
    • Investments remain active: Your portfolio remains invested even after being pledged as collateral. This means your investment stays intact while its value is simultaneously utilized for margin purposes.

    Read Also: Joint Demat Account: Meaning, Features, Benefits, and Steps

    Risks Of Using Collateral 

    Using collateral can be beneficial, but it also entails certain risks.

    • Market Decline: If the value of pledged securities falls, their collateral value may also decrease.
    • Increase in Haircut: Haircut rates may change based on market conditions or regulations, potentially reducing the available margin.
    • Margin Shortfall: If the available margin falls below the required level, the broker may ask you to deposit additional margin.
    • Forced Square-Off: If the margin requirement is not met on time, the broker may square off your open positions to mitigate risk.
    • Interest on MTF: If you use the Margin Trading Facility (MTF), you may be required to pay interest charges on the funds provided by the broker.

    Conclusion

    Once you understand the concept of collateral amount in a Demat account, it becomes clear that you can utilize the value of your investments without actually selling them. If collateral is used prudently and in accordance with the rules, it can prove to be a useful option for effective capital management in trading.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Margin Against Shares: How Does it Work?
    2What Is Liquidation in MTF?
    3What is Intraday Margin Trading?
    4What is Operating Profit Margin?
    5What is Stock Margin?
    6Key Differences Between MTF and Loan Against Shares
    7What is Margin Funding?
    8Top Tips for Successful Margin Trading in India
    9Is Margin Trading Facility (MTF) Safe in India?
    10MTF vs Intraday Trading: Key Differences

    Frequently Asked Questions (FAQs)

    1. What is collateral amount in a Demat account?

      It is the trading margin received in exchange for pledged securities.

    2. Is the collateral amount real cash?

      No, it is not cash but trading margin.

    3. Can I withdraw the collateral amount?

      No, it cannot be withdrawn.

    4. Do pledged shares remain in my Demat account?

      Yes, the shares remain in your Demat account.

    5. Can all shares be used as collateral?

      No, only eligible shares can be used.

  • Best Retirement ETFs in India

    Best Retirement ETFs in India

    Retirement planning isn’t just about saving cash, it’s about choosing investments that actually grow your money over time. That’s why so many people are turning to ETFs. If you’re looking for the right options for your future, this guide is here to help. We’ll cover how to pick the best retirement ETFs, key factors to consider, and simple strategies to make smart decisions for your long-term goals.

    What is an ETF?

    An ETF (Exchange-Traded Fund) is an investment option that tracks an index, gold, bonds, or other assets. Its units can be bought and sold on stock exchanges just like shares. Through a single ETF, you can gain investment exposure to multiple securities simultaneously, thereby achieving portfolio diversification.

    What is a Retirement ETF?

    A Retirement ETF is not a distinct category of ETF in itself; rather, the term refers to ETFs selected with the specific goal of building a retirement corpus over the long term. Investors can choose a mix of equity, bond, gold, or index ETFs based on their goals, time horizon, and risk appetite to build a robust fund for the future.

    How does an ETF work?

    An ETF is designed to mirror the movement of a particular index or asset. As that underlying asset gains or loses value, the ETF’s price shifts right along with it. You can easily trade these on the stock market throughout trading hours, just like regular shares.

    Why ETFs Can Be a Smart Choice for Retirement Planning 

    If you are looking for a retirement investment that is easy to manage and offers exposure to multiple companies simultaneously, an ETF could be a great choice.

    • Lower Investment Costs Can Improve Long-Term Returns: Every investment involves some costs. ETFs generally have lower expenses, allowing a larger portion of your investment to work for you. Over the long term, this difference can translate into better returns.
    • Diversification Helps Reduce Portfolio Risk: Instead of relying on a single company, an ETF provides exposure to a range of companies. This reduces the risk of your entire investment being impacted by a decline in any single stock.
    • Easy to Buy and Sell on the Stock Exchange: ETFs are bought and sold on the stock exchange just like individual shares. You can trade them whenever the market is open, according to your needs.
    • Passive Investing Requires Less Monitoring: An ETF is a convenient option even if you cannot track the market daily. Since it tracks a specific index, there is less need for frequent adjustments.
    • Suitable for Long-Term Wealth Creation: Preparing for retirement takes time. With regular investing and a disciplined approach avoiding hasty decisions, ETFs can help you gradually build a substantial corpus.

    Types of ETFs Suitable for Retirement Portfolio 

    When selecting ETFs for retirement, your goals and investment horizon are just as important as the returns.

    • Equity ETFs for Long-Term Growth: If you have a significant amount of time before retirement, Equity ETFs are worth considering. Many investors include them in their portfolios to capitalize on market growth over time.
    • Index ETFs for Stable Market Exposure: For those who wish to invest in the market without the hassle of selecting individual stocks, Index ETFs offer a convenient option. They aim to track the performance of a specific index.
    • Gold ETFs for Inflation Protection: Gold often gains importance during periods of rising inflation. Consequently, many investors allocate a small portion of their retirement portfolio to Gold ETFs to maintain a balanced investment mix.
    • Bond ETFs for Capital Stability: If retirement is approaching or you prefer to avoid high risk, you might consider Bond ETFs. Their primary objective is usually to provide stability to the portfolio.
    • International ETFs for Global Diversification: If you do not wish to limit yourself to the Indian market, International ETFs offer an opportunity to invest in foreign companies. This provides your investment portfolio with exposure to diverse markets.

    Read Also: Best Mutual Funds for Retirement Planning

    Which ETF Is Best at Different Stages of Retirement? 

    The same ETF is not suitable for every age group. As retirement approaches, the portfolio’s focus should shift from growth to stability.

    Age / StageWhat kind of ETFs should you focus on?Why It Can Be Suitable
    20s (20-29 Years)Equity ETFs, Index ETFsA longer investment horizon allows more time to benefit from market growth.
    30s (30-39 Years)Equity ETFs + Gold ETFsGrowth remains the priority, while Gold ETFs can add better diversification.
    40s (40-49 Years)Equity ETFs + Bond ETFs + Gold ETFsA balanced mix can help reduce risk without giving up growth potential.
    5-10 Years Before RetirementBond ETFs, Broad Market Index ETFsThe focus gradually shifts toward protecting capital and reducing portfolio volatility.
    After RetirementBond ETFs, Income-Oriented ETFs, Limited Equity ETFsStability and regular income become more important, while a small equity allocation may help manage inflation over the long term.

    7-Point Checklist Before Choosing the Best ETF for Retirement

    Factor Why It Matters
    Retirement GoalChoose an ETF that aligns with your goals and investment horizon.
    Expense RatioA low-cost ETF can prove to be better in the long run.
    Tracking ErrorAn ETF with low tracking error attempts to perform close to the index.
    AUM A healthy AUM reflects the stability of the fund and investor participation.
    Liquidity It is easy to buy and sell ETFs when there is good liquidity.
    Underlying IndexBefore investing, understand which companies or sectors the ETF tracks.
    Past PerformanceEvaluate based not only on past returns but also by considering other aspects.

    How Much Should You Invest in Retirement ETFs?  

    The right investment amount is one that you can sustain over the long term without interruption.

    • Start With Your Budget: First, determine how much you save each month after expenses. Set your investment amount accordingly so that you do not have to stop investing midway.
    • Estimate Your Monthly Investment: You can start with even a small amount. The key is to ensure the investment remains regular every month.
    • Increase Investments With Income Growth: If your salary or income rises in the future, increase your investment amount gradually. This can help build your retirement fund faster.
    • Avoid Investing Beyond Your Capacity: Do not invest beyond your means simply to build a large fund. Doing so might force you to halt your investments prematurely if the need arises.

    Tax Rules on Retirement ETFs 

    Taxation on ETFs is determined by their type (Equity, Gold, or Debt). Therefore, it is important to understand the tax rules before investing.

    ETF TypeShort-Term Capital Gain (STCG)Long-Term Capital Gain (LTCG)Holding Period for LTCG
    Equity ETF20%12.5% ​​tax after the annual LTCG exemption of ₹1.25 lakh.More than 12 months
    Gold ETFIncome Tax Slab12.5% (Eligible investments, without indexation)More than 12 months
    Debt ETFIncome Tax SlabIncome Tax SlabNo LTCG benefit available 
    International / Non-Equity ETFCommon Income Tax Slabs12.5% ​​or as per applicable rulesIt depends on the ETF category and the purchase date.

    How to Withdraw Money From Retirement ETFs Without Affecting Your Portfolio 

    When withdrawing money from ETFs after retirement, adopt a strategy that meets your needs while allowing the remaining investment to stay invested for the long term.

    • Sell Units Gradually: Sell ETF units based on your requirements. A phased withdrawal is considered better than selling your entire holding at once.
    • Plan Withdrawals Around Your Expenses: Determine the withdrawal amount based on your monthly or annual expenses. This helps avoid selling more units than necessary.
    • Avoid Selling in a Hurry: If you do not need the money immediately, do not rush into selling your ETFs. Waiting for the right time can often prove beneficial.
    • Keep Your Investment Horizon in Mind: If you have income from other sources, you can retain a portion of your ETF investment for future years instead of selling all the units immediately.
    • Use Other Savings for Small Expenses: For small or unexpected expenses, utilize your existing savings or emergency fund first. This ensures that your ETF investment earmarked for retirement remains undisturbed.

    Read Also: Best Nifty 50 ETFs in India

    ETF vs Mutual Fund for Retirement Planning 

    Both ETFs and mutual funds can be good options for retirement, but the right choice depends on your investment style and needs.

    Feature ETF Mutual Fund
    Trading They can be bought and sold throughout the trading hours, just like shares.Buying and selling take place at the end-of-day NAV.
    Expense RatioIt is usually low.In many schemes, it can be higher than that of ETFs.
    Investment StyleMost of them track the index.Both Active and Passive options are available.
    FlexibilityTrades can be executed at any time during market hours.The facility for intraday trading is not available.
    Demat AccountA Demat account is necessary for investing.A Demat account is not required for most schemes.
    Best Suited ForInvestors who prefer low costs and passive investing.Investors seeking SIPs and professional fund management.

    Are ETFs Safe for Retirement Planning? 

    A well-chosen ETF can aid in retirement planning, though it always carries market risk.

    • No Investment Is Completely Risk-Free: An ETF is also a market-linked investment. Its price fluctuates over time, so it cannot be considered a completely risk-free investment.
    • Spreading Investments Helps: An ETF can comprise multiple stocks or other assets. This helps mitigate the impact of a single company’s poor performance on the overall investment.
    • Patience Makes a Difference: When investing for retirement, there is no need to react to every minor market dip. A long-term perspective often yields better results.
    • Invest According to Your Needs: Do not select an ETF based solely on good returns. Your age, retirement timeline, and financial needs are equally important.

    Who Should Invest in Retirement ETFs? 

    Retirement ETFs can be a good choice for those looking to invest in a disciplined manner over the long term.

    • Salaried Employees: Individuals with a regular income can gradually build a retirement corpus by investing every month.
    • Self-Employed Professionals: For those without pension benefits, retirement ETFs can serve as an option to build capital for the future.
    • Young Investors: Those who start investing early can benefit from the power of compounding over a long period.
    • Late Starters: Even if you start late, a retirement fund can still be built through regular investments.
    • Passive Investors: ETFs are suitable for those who prefer simple, low-maintenance investments over the hassle of frequently selecting individual stocks.
    • FIRE Planning Enthusiasts: Those aiming to achieve early financial independence can consider including retirement ETFs in their long-term strategy.

    How to Invest in Retirement ETFs Using Pocketful 

    You can start investing in Retirement ETFs via Pocketful in a few simple steps.

    • Open a Free Demat Account: Open a Demat and Trading account on Pocketful with ₹0 account opening charges and complete the KYC process.
    • Add Funds: Add the required investment amount to your trading account.
    • Search for Your Preferred ETF: Search for your preferred Retirement ETF in the search bar and view its details.
    • Place Your Buy Order: Select the units and place your order. You can invest in ETFs on Pocketful with ₹0 delivery brokerage.
    • Monitor Your Portfolio: After investing, periodically track your ETF’s performance and manage it in line with your retirement goals.

    Conclusion

    Getting ready for retirement takes more than just stashing away money; you need smart investments that work for you. If you want a low-cost option built for the long haul, retirement ETFs are definitely worth considering. Just make sure your final choice aligns with your personal goals and risk tolerance before jumping in.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Small-Cap ETFs to Invest in India
    2Best Energy ETFs in India
    3Best Silver ETFs in India
    4List of Best Gold ETFs in India
    5Best Debt ETFs to Invest in India
    6Global ETFs in India

    Frequently Asked Questions (FAQs)

    1. What is a Retirement ETF?

      It is a long-term ETF investment designed for retirement.

    2. Is a Demat Account required for ETFs?

      Yes, a Demat and Trading account is required to invest in ETFs.

    3. Can I invest a small amount in ETFs?

      Yes, you can start investing with the price of a single unit.

    4. Are Retirement ETFs risky?

      Yes, they carry market risk.

    5. Can I sell my ETF anytime?

      Yes, ETFs can be sold during market trading hours.

  • How to Protect Demat Account from Fraud: 15 Safety Tips

    How to Protect Demat Account from Fraud: 15 Safety Tips

    Demat account security matters a lot today because digital investments are growing very fast. The stock market attracts many new people every day. Unfortunately, this growth also brings in dangerous cybercriminals looking for an easy target. There is a massive rise in online investment scams targeting ordinary retail investors in India. Fraudsters trick innocent individuals to steal their hard earned money and valuable shares. They use clever tactics to gain illegal access to personal investment portfolios.

    What is a Demat Account?

    Many beginners often ask a very common question. Is Demat account a safe option for your investments? To answer this question, one must first understand the basic purpose of this system. A Demat account holds shares and securities in an electronic format. This system completely replaces old paper certificates and prevents physical theft.

    The main purpose of a Demat account is to keep investments secure and make daily trading easy. It works much like a regular bank account. Instead of keeping physical cash, it safely stores digital shares, mutual funds, and government bonds.

    When an investor buys shares, they get credited directly to this account. When they sell shares, they get debited. These accounts are generally very safe because they are tightly regulated by the government. Depositories like CDSL and NSDL monitor them constantly to prevent errors and fraud.

    Can a Demat Account Be Hacked or Misused?

    Yes if proper care is not taken security issues can be there with your electronics accounts. A common risk is unauthorized trading by unknown people. This happens when a scammer logs in and trades without the true owner’s permission.

    There is a big difference between actual computer hacking and social engineering. Hacking involves breaking into highly secure systems using complex technical skills. Social engineering simply involves tricking a person into giving away their secret password or OTP.

    When researching whether a demat account handling service is safe or not, individuals must check the platform’s security features. A high amount of demat account fraud happens purely due to human error. Investors might unknowingly share sensitive details or click on dangerous internet links.

    Common Types of Demat Account Frauds

    Investors should know the common tricks used by scammers. The table below explains the most frequent types of frauds seen in the market today.

    Fraud TypeSimple Explanation
    Phishing Emails and Fake Login PagesScammers send fake identical emails just like your broker and these emails have links that can directly steal your login details even if pressed once. 
    OTP and Verification Code ScamsFraudsters call and pretend to be helpful customer care agents. They ask the investor to share a six digit OTP to solve a fake problem.
    Fake Customer Support CallsScammers put fake helpline numbers on the internet. When somebody searches for help they call on these numbers and scammers trick them to get access to their account and all details. 
    Screen Sharing App FraudsHere Scammers trick and ask the individual to download screen sharing apps like Anydesk or TeamViewer. And once the screen is shared the scammers can clearly see the investors personal information and relevant data. 
    SIM Swap FraudCriminals manage to get a duplicate SIM card of the investor’s registered mobile number. They then receive all the banking and trading OTPs directly on their own device.
    Unauthorized Power of Attorney (PoA) MisuseSometimes untrustworthy brokers might misuse the PoA document given by the client. They might sell shares or transfer funds without the actual owner’s consent.
    Fake Trading Apps and Investment PlatformsScammers create bogus mobile applications that look very real. Users deposit money into these fake apps, but the funds never reach the actual stock market.
    Malware and Keylogger AttacksClicking on unknown links sometimes install malware or harmful software to the investors system. Keyloggers record every single keystroke, easily capturing secret passwords without anyone knowing.

    Signs That a Demat Account May Be Compromised

    Getting to know about the scam can save you a lot of money. Here are some ways by which you can check if your account is in danger.

    Warning SignWhat It Means
    Unauthorized Login AlertsReceiving an SMS or email about a login from an unknown location is a huge red flag. It means someone else currently has the account password.
    Unknown Buy or Sell TransactionsFinding strange trades in the transaction history is a clear sign of trouble. Scammers might be using the stolen funds to manipulate risky penny stocks.
    Missing Shares from HoldingsIf long term investments suddenly disappear from the portfolio, it indicates a serious security breach. Immediate action is required to freeze the account.
    Unrecognized Device AccessModern security systems often show which devices are currently logged in. Spotting an unknown mobile phone or computer model means the account is fully compromised.
    Unexpected Changes in Contact InformationScammers often try to change the registered email or phone number first. This completely stops the real owner from getting transaction alerts.

    Read Also: How to Enable Two-factor Authentication in Demat Account?

    15 Best Ways to Protect a Demat Account from Fraud

    1. Choose a SEBI-Registered Broker

    It is crucial to pick a reliable and well known Depository Participant. Registered brokers follow strict rules and offer better protection against scams. An unregistered broker might easily run away with the invested money.

    2. Create a Strong and Unique Password

    The best way is to put a strong password that contains capital letters, numbers, and special symbols. The password shall be a mix of everything and not just your date of birth or name as longer complex passwords are very hard to break. 

    3. Enable Two-Factor Authentication (2FA)

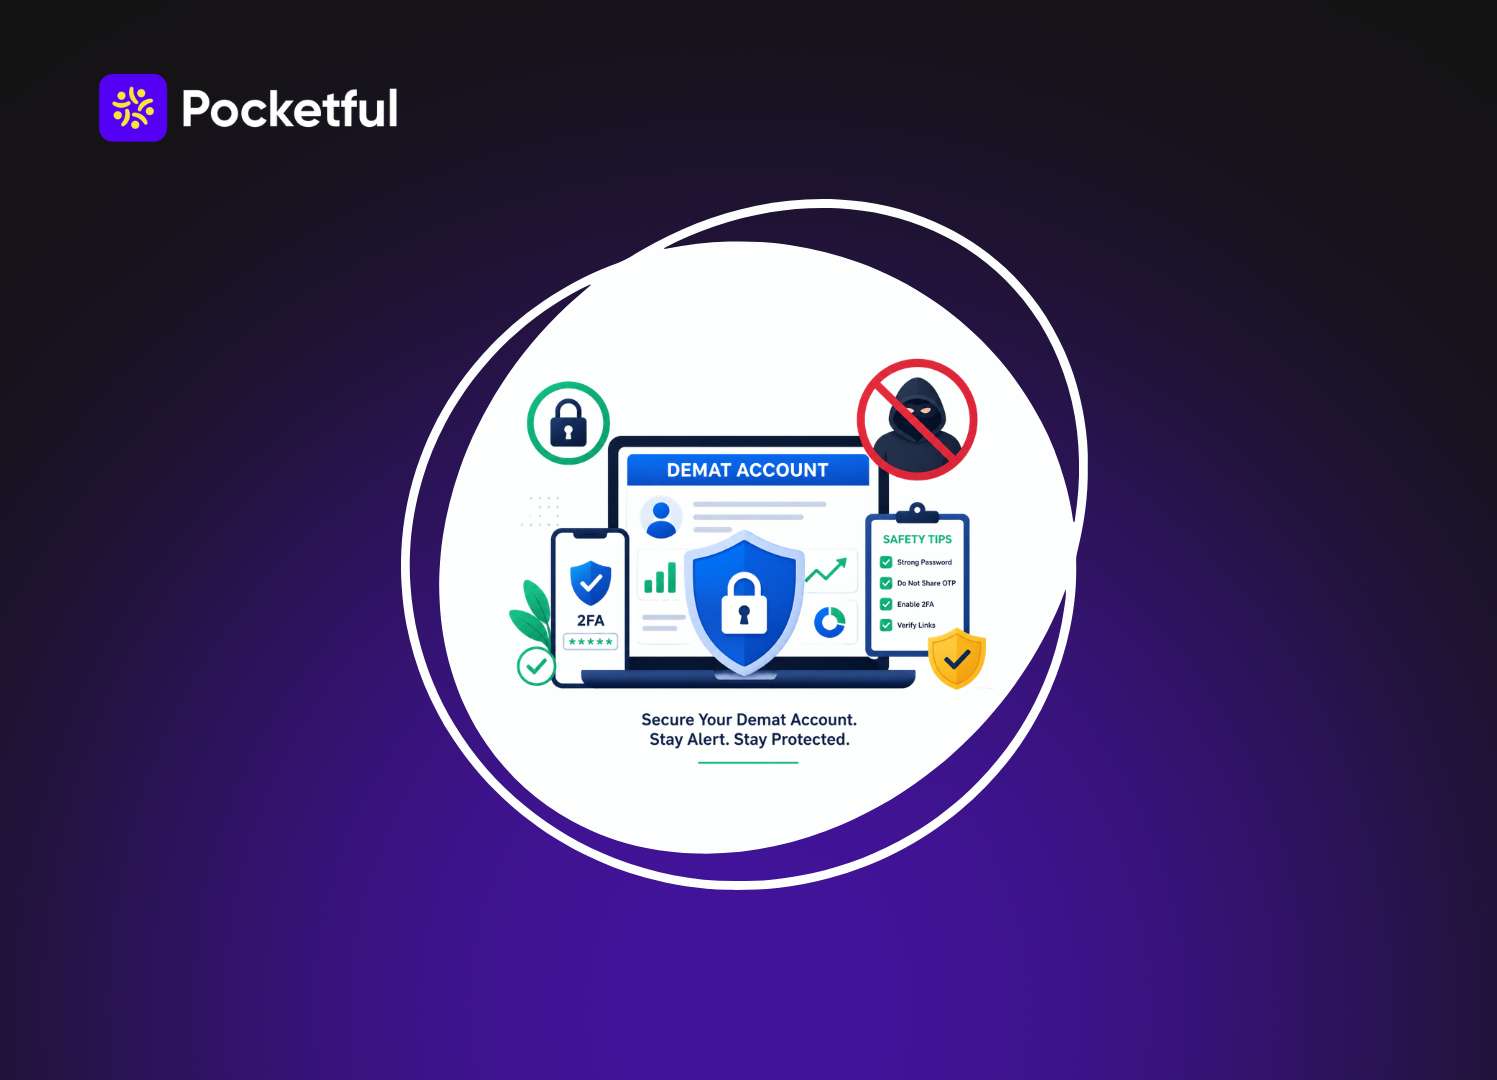
    This means adding a second layer of security to your account, even if the password is breached your account would require an additional step that is the OTP to log in. Most modern brokers make this feature mandatory for all users.

    4. Never Share OTPs or Login Credentials

    Official brokers and depositories never ask for passwords or OTPs over a phone call. The information shall always be kept secret at all times and shall not be shared with anyone. 

    5. Regularly Change the Password

    Updating the account password every few months is a very good habit. It highly reduces the risk of old data breaches affecting the account. A fresh password keeps the account safe from past mistakes.

    6. Monitor Holdings Frequently

    Investors shall regularly keep an eye on their portfolio as it helps in spotting errors. Errors if caught within time helps you to prevent major financial losses.

    7. Check SMS and Email Alerts from Depositories

    CDSL and NSDL send direct alerts for every single trade. Reading these messages carefully helps catch unauthorized activities instantly. These alerts act as an early warning system for the investor.

    8. Keep the Mobile Number and Email Updated

    You must always keep your credentials updated as all the security alerts are directly shared on your registered details. It makes sure that all security alerts are directly reaching you on time. A wrong phone number means missing out on crucial security warnings.

    9. Avoid Public Wi-Fi While Trading

    One should always avoid using free public networks and Wifis as they are generally very insecure. It is very easy for hackers to intercept these open networks and steal your data and password. Always use a private mobile network when opening a trading app.

    10. Install Antivirus and Update Devices

    Using good security software keeps dangerous malware away. Updating the phone and computer operating systems fixes known security weaknesses. A secure device is the first step to safe trading.

    Scam messages often contain links offering free stock tips or huge profits. Clicking them can download dangerous viruses or lead to fake websites. It is best to simply delete such messages immediately.

    12. Secure the Debit Instruction Slip (DIS)

    The DIS booklet is exactly like a bank chequebook. It should be kept safely, and one must never leave a signed blank slip with a broker. A signed slip allows anyone to transfer shares out of the account.

    13. Be Careful Before Signing a Power of Attorney (PoA)

    Investors should insist on a limited purpose PoA or use the new DDPI system. This stops brokers from transferring shares without proper permission. The new DDPI system is much safer for retail investors.

    14. Freeze the Demat Account If Not Using It

    People traveling abroad or stopping trading for a while should lock their accounts. Depository participants offer a simple facility to freeze accounts temporarily. This stops any transactions from taking place until the account is unfrozen.

    15. Log Out After Every Trading Session

    Investors shall not directly close the mobile app rather you should manually log out every time. This needs to be done so that nobody can access the app or funds as sometimes the app still runs in the background. This is especially important when using a shared computer.

    Understanding CDSL and NSDL Security Features

    The two main depositories in India offer excellent security features. The table below outlines these built in protections.

    Security FeatureHow It Helps
    SMS Alerts for Every TransactionThe depositories send instant messages for all debit and credit movements. This keeps investors well informed about everything happening with their shares.
    Email NotificationsDetailed statements and transaction confirmations are sent directly via email. These official emails provide a clear and permanent record of all market activities.
    Account Statement VerificationBoth NSDL and CDSL provide consolidated account statements on their websites. Investors can log into depository portals directly to double check their actual holdings.
    Freeze and Unfreeze FacilityDepositories allow account holders to freeze their entire account or just specific shares. This is a very powerful tool to stop all unauthorized transfers instantly.
    Trusted Device AuthenticationModern security systems are designed to recognize trusted devices. Logging in from a completely new computer often triggers an extra security verification step.

    How to Verify Every Transaction in a Demat Account

    Keeping a close watch on transactions is very necessary. Here is how investors can verify their trades safely.

    Verification MethodWhy It Is Important
    Checking Holding StatementsInvestors must compare the shares shown in their trading app with the official depository statement. These two numbers should always match perfectly.
    Reviewing Daily Transaction ReportsBrokers send a contract note at the end of every trading day. This document contains exact details of all the buying and selling done on that specific day.
    Matching Trades with Broker RecordsIt is a good practice to check the financial ledger regularly. Ensure that the money deducted from the bank matches the exact value of the shares purchased.
    Importance of Monthly Account ReconciliationSetting aside time once a month to review the account is highly vital. Monthly checks help spot small discrepancies that might otherwise go completely unnoticed.

    Read Also: What is TPIN in Demat Account?

    What Should You Do If You Suspect Fraud?

    Step 1: Immediately Change your login credentials

    The very first action is to secure the login details. Changing the password and the T-PIN stops the hacker from doing further damage. This step must be taken within seconds of spotting a fraud.

    Step 2: Freeze the Demat Account

    Investors must quickly contact the depository or broker to lock the account. A frozen account cannot transfer any shares out to another person. This keeps the remaining shares safe.

    Step 3: Contact the Broker

    The trading platform’s customer support must be informed immediately. They can easily cancel pending orders and block unauthorized fund withdrawals. Brokers have special tools to halt suspicious activities.

    Step 4: Inform the Depository (CDSL/NSDL)

    Depositories should be made fully aware of the suspicious activity. They have the authority to trace the share movements and help in the official investigation and make the process speedy.

    Step 5: Report the mishappening to SEBI

    You must file a formal complaint on the SEBI SCORES portal. This makes sure that the broker and authorities take the matter seriously and resolve it as soon as possible. SEBI strictly monitors these complaints.

    Step 6: File a Police/Cyber Crime Complaint

    The victim should report the fraud to the national cyber police by dialing their helpline number 1930, this helps in tracing the stolen funds immediately. A quick police report is very helpful.

    How SEBI Protects Investors Against Demat Frauds

    SEBI works very hard to keep the market safe. The following table highlights the main steps taken by the regulator.

    Protective MeasureDetails
    Regulatory FrameworkSEBI creates strict rules that all market participants must follow. These regulations ensure that the stock market remains fair, transparent, and secure for everyone.
    Depository MonitoringThe regulator keeps a very close watch on NSDL and CDSL operations. This constant supervision ensures that depositories manage investor data and shares carefully.
    Broker Compliance RequirementsBrokers face heavy penalties if they misuse client funds or shares. SEBI regularly conducts strict audits to ensure brokers are not involved in any illegal activities.
    Investor Protection MechanismsSEBI runs the SCORES portal to handle public complaints efficiently. They also enforce systems like the direct payout mechanism, bringing shares directly to the investor’s account.

    Conclusion

    The digital age brings great convenience to the stock market. However, staying alert is the absolute key to keeping investments completely safe. By following basic security rules, anyone can enjoy a peaceful and profitable investing journey.

    For more market news and insights, download Pocketful, offering users zero brokerage on delivery trades and an easy to use platform designed for both beginners and experienced investors.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Demat Account in India
    2Lifetime Free Demat Account (AMC Free)
    3Demat Account: Fees & Charges
    4How to Close Your Demat Account Online?
    5Features and Benefits of Demat Account
    6Types of Demat Accounts in India
    7How to Use a Demat Account?
    8How to Buy Shares through a Demat Account?
    9Joint Demat Account
    10BSDA – What is a Basic Service Dema

    Frequently Asked Questions (FAQs)

    1. Is it safe to use a public Wi-Fi network while trading in stocks? 

      No, free Wi-Fi or public connections are very insecure and are easy to hack by the scammers. One should always use a private network or mobile data while trading.

    2. What is a DIS booklet in the stock market? 

      A Debit Instruction Slip (DIS) is very similar to a chequebook given by the bank. It is a physical paper document used to authorize the manual transfer of shares between accounts.

    3. How fast should one report an unauthorized transaction?

      One should report as soon as they get to know about the suspicious activity. Also one should immediately inform the cybercrime police by dialing 1930 as this helps in freezing the funds immediately.

    4. Can SEBI help if a broker commits fraud? 

      SEBI helps in protecting retail investors as just by filing a formal complaint with SEBI SCORES online portal the action starts. 

    5. Can a frozen Demat account still receive dividends? 

      Yes, even if the Demat account is freezed due to security reasons investors still get the benefits of dividends linked to their bank account.

  • Demat Account for Private Limited Company – Guide 2026

    Demat Account for Private Limited Company – Guide 2026

    A Demat account for a Private Limited Company is no longer just an investment tool. It has become a compliance requirement as well. With companies increasingly investing in equities, bonds, and ETFs, and with MCA regulations mandating dematerialisation of securities, having a company-level Demat account is now essential.

    Unlike individual accounts, a corporate Demat account requires structured documentation and approvals. This guide explains the complete process, required documents, and how to open a Demat account for a Private Limited Company with Pocketful.

    Why Does a Private Limited Company Need a Demat Account?

    A Private Limited Company operates as a separate legal entity. This means all financial investments must be held in the company’s name. Even when the company has shareholders, the company is treated as a separate legal entity.

    So, having a demat account for the company is quite important as follows:

    • Hold and manage shares, bonds, ETFs, and government securities under the company’s name.
    • Comply with MCA Rule 9B by converting physical securities into electronic form.
    • Invest surplus business funds in market-linked instruments.
    • Participate in IPOs, rights issues, and other corporate opportunities.
    • Maintain a clear and auditable record of all transactions.

    Eligibility to Open a Demat Account for a Private Limited Company

    Before starting the application process, the company must meet a few basic eligibility conditions. These ensure that the entity is legally registered and is in a condition to have one demat account. These are:

    • Be registered under the Companies Act, 2013.
    • Hold a valid PAN card issued in the company’s name.
    • Be active and compliant with ROC filing requirements.

    In addition, all directors and authorised signatories involved in the account must complete individual KYC as per SEBI guidelines.

    Documents Required to Open a Private Limited Company Demat Account

    Opening a corporate Demat account involves detailed documentation. Since the account is in the company’s name, both company-level and individual-level documents will be needed.

    Company-Level Documents

    DocumentDetails
    Company PAN CardMandatory for tax identification.
    Certificate of IncorporationIssued by MCA/ROC at the time of registration.
    Memorandum of Association (MoA)Defines the company’s objectives and scope.
    Articles of Association (AoA)Governs the internal management of the company.
    MCA Challan or ReceiptProof of payment for company registration.
    Latest Address ProofBank statement (not older than 3 months) in the company’s name.
    Balance Sheet for Last 2 Financial YearsAudited financials or a Net Worth Certificate from a Chartered Accountant.
    Board ResolutionAuthorising account opening and naming authorised signatories.
    List of DirectorsOn company letterhead.
    List of Authorised SignatoriesRequired if different from directors.
    Shareholding PatternReflecting the ownership structure of the company.

    Director Or Authorised Signatory Documents

    DocumentDetails
    PAN CardMandatory for identity verification.
    Aadhaar CardRequired for KYC.
    Passport-size PhotographRecent photograph.
    SignatureScanned or physical signature as required.

    Tip: All documents should be self-attested by the authorised signatory. Company documents must also carry the official seal wherever applicable.

    Read Also: How to Open a Demat Account Online?

    Step-by-Step Process To Open A Demat Account For A Private Limited Company With Pocketful

    When you are planning to open a demat account for a private company, here are the steps to follow:

    Step 1: Contact The Broker Or Depository Participant

    Start by reaching out to the broker or depository participant where you want to open the Demat account. Their team will explain the account opening process, eligibility criteria, required documents, and verification requirements. Carefully understand all instructions before proceeding further.

    Step 2: Prepare All Required Documents

    Now, collect all the documents as per the list. Check the details and ensure there is no mismatch in the same. Also, it is important that you properly sign every document as needed. Company documents should be stamped as well. 

    Step 3: Submit The Application And Documents

    Fill out the application form. Fill in the spaces as asked. The name of the company and the directors should be clearly mentioned. Follow what is there in your company board letter. 

    Step 4: Complete In-Person Verification

    A verification process is required for non-individual accounts. A representative will verify original documents either physically or through a video-based process. The authorised signatory must be present.

    Step 5: Complete KYC For Directors And Signatories

    Each director or authorised signatory must complete individual KYC. This includes PAN and Aadhaar verification as per SEBI guidelines.

    Step 6: Account Activation

    Once all checks are complete, the Demat account is activated. Login credentials are shared. You can check the working. Once you are sure, start investing in your company as needed.

    Things To Keep In Mind

    Opening a demat account for a company is easy. But most of the people face delays due to small mistakes. These include the following: 

    • Ensure compliance with MCA Rule 9B by dematerialising existing physical securities.
    • Draft the Board Resolution carefully with clear authority and correct signatory details.
    • Use a CA-certified Net Worth Certificate if audited financials are not available.
    • Maintain exact name consistency across PAN, incorporation documents, and application forms.
    • Check the fee structure, as corporate accounts may have higher AMC charges.
    • Keep ROC filings updated, as inactive or non-compliant companies may face rejection.

    Read Also: How to Open a Demat Account for Partnership Firms & Required Documents?

    Conclusion

    Opening a Demat account for a Private Limited Company is not just about investing. It is equally about staying compliant and maintaining proper financial records. With MCA Rule 9B in place, companies need to ensure their securities are held in electronic form.

    With the right documentation and a clear process, getting started is straightforward. Platforms like Pocketful make it easier to open and manage a corporate Demat account with guided support at every step.

    If you are planning to invest or need to meet compliance requirements, this is the right time to set up your company’s Demat account with Pocketful.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Demat Account in India
    2Lifetime Free Demat Account (AMC Free)
    3Demat Account: Fees & Charges
    4How to Close Your Demat Account Online?
    5Features and Benefits of Demat Account
    6Types of Demat Accounts in India
    7How to Use a Demat Account?
    8How to Buy Shares through a Demat Account?
    9Joint Demat Account
    10BSDA – What is a Basic Service Dema

    Frequently Asked Questions (FAQs)

    1. Is It Mandatory For A Private Limited Company To Have A Demat Account?

      Yes. Under MCA Rule 9B, private limited companies are required to dematerialise their securities. This makes a Demat account a compliance requirement, especially for companies holding or issuing shares.

    2. Can Any Director Operate The Company’s Demat Account?

      No. Only individuals named as authorised signatories in the Board Resolution can operate the account. The authority is strictly defined during the account opening process.

    3. What Is A Board Resolution And Why Is It Required?

      A Board Resolution is a formal approval document passed by the company’s board. It authorises the opening of the Demat account and clearly states who can operate it on behalf of the company.

    4. What If The Company Does Not Have Two Years Of Financials?

      In such cases, a Net Worth Certificate issued by a Chartered Accountant can be submitted instead of audited financial statements.

    5. Can A Private Limited Company Trade In F&O Using Its Demat Account?

      Yes. A company can trade in equity, intraday, and F&O segments, subject to SEBI regulations and account activation for these segments.

  • Demat Account for Partnership Firm – Documents & Process

    Demat Account for Partnership Firm – Documents & Process

    A Demat account allows investors to hold shares and other securities in electronic form. There is a common misconception that only individual investors can open demat accounts, but partnership firms can also enjoy the benefits of opening a demat account for better investment and management of their business funds.

    Many partnership firms open Demat accounts to invest their surplus money in stocks, mutual funds, bonds, ETFs and other financial products. That makes buying, selling and holding investments far easier, faster and safer.

    However, the process of opening a Demat account for a partnership firm is slightly different from an individual account.  

    In this blog, we will learn about opening a Demat account for a partnership firm, documents required, step-by-step process, and a few important things to remember before you get started.

    What is a Demat Account for a Partnership Firm?

    A Demat account for a partnership firm is essentially a digital locker for all its investments. Gone are the days of storing physical share certificates, everything from shares to bonds is now held electronically, which makes managing them a whole lot simpler and more secure.

    The account is registered under the firm’s name, and the partners who are authorised to do so handle it on the firm’s behalf. Using this account, the firm can put its money into shares, mutual funds, bonds, ETFs, and various other market-linked options.

    Partnership firms usually open a Demat account when they want to efficiently use their surplus funds, whether that is building a long-term investment portfolio or actively trading in the stock market.  

    Why Partnerships Firms Open Demat Accounts? 

    • Idle Money is Wasted Money: Every firm hits a stage where funds are just idle in a current account, doing absolutely nothing. Smart partners do not let that go on for long. They move that surplus into shares, mutual funds, bonds, or ETFs, because even modest returns beat zero returns, every single time.
    • No Worries About Physical Handling of Papers: There was a time when firms stored stacks of share certificates in files and almirahs. Now, a demat account can easily hold securities, and suddenly there is no scrambling for paperwork when you need it most.
    • Faster & Safer Transactions: Demat accounts make transactions faster, cleaner, and far more secure than the old way of doing transactions. And the fear of documents getting lost, damaged, or stolen also disappears.
    • Better Tracking of Investments: A Demat account gives firms complete visibility, portfolio value, past transactions, pending dividends, current holdings, all in one place, available anytime. For partners who want to stay on top of their investments without hiring a dedicated person to track it all, this is very useful.

    Documents Required 

    The documents needed are listed below;

    1. Partnership Deed – A notarised copy that clearly mentions all partners’ names and the firm’s structure. 
    2. PAN Card – Both, the firm’s PAN and the PAN cards of all authorised partners.
    3. Address Proof – A utility bill, lease agreement, or bank statement, but make sure it is not older than three months.
    4. Bank Details – A cancelled cheque or bank statement in the firm’s name, needed to link the account for transactions.
    5. Registration Certificate – If your firm is registered under the Indian Partnership Act, 1932, this needs to be submitted.
    6. Resolution Letter – Signed by all partners, clearly naming who’s authorised to run the account.
    7. KYC Documents of Authorised Partners – Aadhaar, Passport, or Voter ID along with address proof for each authorised partner.

    Furthermore, some DPs may also ask for: 

    • Last six months’ bank statement of the firm
    • Latest audited Profit & Loss statement
    • Most recent ITR acknowledgement
    • Net Worth Certificate from a CA (with UDIN number)
    • FATCA declaration
    • Balance sheets for the last two financial years, CA-attested

    Read Also: How to Open an LLP Demat Account in India: Documents & Process

    Step-by-Step Process to Open a Demat Account

    Opening a Demat account for a partnership firm is not as complicated as it sounds, but it does require some groundwork. Let us explore how the process works. 

    Step 1: Pick the Right Depository Participant (DP)

    The first step is selecting a suitable Depository Participant (DP). A DP can be a bank or brokerage platform registered with either NSDL or CDSL.

    Before making a decision, compare:

    • Account opening charges
    • Annual Maintenance Charges (AMC)
    • Brokerage and transaction fees
    • Trading platform features and usability
    • Customer support services

    Choosing the right DP can help ensure a smoother trading and investing experience.

    Step 2: Fill Out the Account Opening Form

    Once you have chosen your DP, get hold of the account opening form, most DPs let you download it online, though some still prefer the physical one. The form will ask for details about the firm itself as well as all the partners involved. 

    Step 3: Submit Your Documents and Complete KYC

    The partnership firm and all partners must complete the Know Your Customer (KYC) process.

    Most DPs allow:

    • Digital document uploads
    • e-KYC verification
    • Video-based verification

    Step 4: Submit the Authority Letter or Resolution

    The firm needs to formally declare, in writing, which partners are authorised to operate the account, sign instructions, and carry out transactions. Without a clear resolution letter or authority letter signed by all partners, the DP will not proceed.

    Step 5: In-Person Verification (IPV)

    At least the authorised partners need to go through IPV. Depending on your DP, this can be done face-to-face at their office or over a video call. It is a regulatory requirement, so this step cannot be skipped. 

    Step 6: Wait for Account Activation

    Once everything is completed, the DP opens the account in the firm’s name and issues a BO ID (Beneficiary Owner Identification number). That is your Demat account number, and your firm is officially ready to go.

    Things to Keep in Mind 

    The account is not opened in the firm’s name alone. As per NSDL guidelines, the Demat account is technically opened in the names of the authorised partners but the securities held in it belong to the firm.

    Unlike individual Demat accounts that can be activated within a day or two, partnership firm accounts involve heavier documentation and verification. 

    The firm must be registered under the Indian Partnership Act, 1932, and must have a valid PAN in the firm’s name. Without these two things, the account simply cannot be opened.

    Benefits of Opening a Demat Account for a Partnership Firm 

    • One Login is Everything You Need: Before Demat accounts became the norm, firms juggled investments across multiple places, different brokers, different formats, different statements. It was frustrating. A Demat account brings everything, shares, bonds, mutual fund units, ETFs, government securities, onto one platform.
    • Aligns with Professional Standards: This is something firms rarely think about, but it matters more than it seems. A partnership firm operating a SEBI-regulated Demat account linked to its PAN, with proper authorization letters and KYC in place, simply comes across differently. Banks take it more seriously. Auditors find it easier to work with.
    • Opportunity to Expand Investment Portfolio: Without a Demat account, a partnership firm is locked out of some of the most interesting investment opportunities in the market. IPOs, Non-Convertible Debentures, Government Securities, new ETF launches, none of these are accessible without a demat account. Opening the account opens those doors, and that kind of diversification can strengthen a firm’s long-term financial position.

    Conclusion 

    Opening a Demat account for a partnership firm is not something that should be put off indefinitely, and yet, a surprising number of firms do that. They either assume it is too complicated, too time-consuming, or simply not relevant to their business. 

    But, a demat account solves problems that firms do not even realise they have, scattered investments, idle surplus funds, slow transactions, messy paperwork, and the constant risk of losing physical certificates. Many modern platforms like Pocketful also make the process easier with seamless online account opening and digital KYC verification. 

    Beyond the operational benefits, it brings credibility, with banks, auditors, and business partners. 

    The process does require some patience. But once it is done, the firm is better positioned, financially and operationally.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Demat Account in India
    2Lifetime Free Demat Account (AMC Free)
    3Demat Account: Fees & Charges
    4How to Close Your Demat Account Online?
    5Features and Benefits of Demat Account
    6Types of Demat Accounts in India
    7How to Use a Demat Account?
    8How to Buy Shares through a Demat Account?
    9Joint Demat Account
    10BSDA – What is a Basic Service Demat Account?

    Frequently Asked Questions (FAQs) 

    1. How long does the whole process take?

      Honestly, it depends on how prepared you are with your documents. If everything is in order, most DPs can activate the account within a week to ten days. 

    2. Is a registered partnership firm required, or can unregistered firms also apply?

      Unregistered firms can also apply. However, registered firms generally face fewer complications during the verification process.

    3. Which DP should a partnership firm choose, NSDL or CDSL?

      Both are equally reliable and regulated by SEBI. The choice really comes down to the broker or bank you’re comfortable working with. 

    4. Can the firm invest in mutual funds through a Demat account?

      Yes, absolutely. Mutual fund units can be held in Demat form, alongside shares, bonds, ETFs, and government securities.

    5. What happens to the Demat account if one partner exits the firm?

      The firm needs to inform the DP, update the partnership deed, and submit revised authorisation documents. The account does not automatically close, but the changes must be formally reflected, otherwise it creates compliance issues.

  • How to Change Name in Demat Account

    How to Change Name in Demat Account

    Life brings many unexpected personal changes and milestones. People often get married or notice spelling mistakes on their important documents. Sometimes individuals simply choose a brand new identity for personal reasons. When these details shift, official financial records must follow suit instantly. Financial institutions remain incredibly strict about matching personal details across all platforms. A mismatch between a government identity card and investment records can quickly lead to frozen funds. Keeping everything updated ensures complete peace of mind for all investors. The Indian stock market requires exact matches to keep investments completely safe from any fraud. This might sound like a tough task initially. However, the modification process remains quite straightforward when the right steps are followed.

    Why Name Change is Required

    Many investors wonder about the exact procedure and often search for how to Change Name in Demat Account. Here are the main reasons why updating these details is required:

    • Smooth Market Transactions: If the identity on the permanent account number (PAN) card does not match the trading profile, buying and selling shares becomes very difficult. Brokers might temporarily block the trading profile to prevent illegal trades. Matching records keep the trading account active and ready for the market.
    • Claiming Dividends: Companies pay out dividends directly to the exact person listed in their shareholding records. A slight mismatch can delay these payouts or cause bank transfer failures. Accurate records ensure that extra income reaches the bank safely.
    • KYC Approvals: Regulatory bodies require strict and ongoing compliance for all financial participants. Future profile modifications or transferring funds will fail if the details are not identical across all investment platforms. Keeping the Know Your Customer (KYC) data updated prevents these sudden rejections.
    • Easy Inheritance: Having accurate and matching records makes it much easier for nominees or family members to claim investments in the future without legal hurdles. It secures the financial future of loved ones.

    Ignoring a name mismatch can lead to serious legal and regulatory roadblocks. The financial system relies entirely on accurate data to prevent illegal activities. Leaving old details on an active profile is not an option.

    Here are three legal implications of a change in name:

    • Regulatory Compliance Failure: The Securities and Exchange Board of India (SEBI) demands consistent financial records for all active investors. This strict rule prevents fraud, stops money laundering, and ensures complete investor safety. 
    • Taxation Issues: The Income Tax Department links all financial activities directly to the PAN card. If the stock broker records do not match the official tax records, it can lead to compliance notices or tax filing errors. Accurate names prevent unnecessary scrutiny from tax officials.
    • Banking Rejections: Stock trading requires a fully linked and verified bank profile. If the bank details have a different identity compared to the stock holding profile, the depository participant will automatically reject money transfers. The law prevents third-party bank transfers to ensure money goes to the rightful owner.

    Step by Step Process to Change Your Name

    Updating personal records involves a clear and logical sequence of actions. Investors must follow this path carefully to ensure quick approval. Missing a step can restart the entire process.

    Step 1: Update the PAN Card First

    In India, the PAN card serves as the master financial record for all citizens. It must show the new identity before reaching out to any stock broker. Investors should apply to the Income Tax Department for a PAN correction first.

    Step 2: Contact the Depository Participant

    The depository participant is the broker or bank actively managing the investments. Account holders should contact their broker to request a specific account modification form. Modern platforms often provide this form as a downloadable file on their official websites.

    Step 3: Fill modification form

    User shall be very careful while writing the old details, new details, and the unique client ID in the form. Every section must be filled out using clear block letters to avoid reading errors. Providing the correct client master details is highly crucial here.

    Step 4: Submit Supporting Documents

    The investor must attach the correct legal proofs based on the exact reason for the modification. All document photocopies must be self-attested, which means they must be signed by the account holder. Some brokers also require an in-person verification process over a video call to confirm the identity.

    Step 5: Verification and Confirmation

    The broker carefully verifies the request and forwards the approved data to the national depositories. This system update usually takes between seven to fifteen business days to complete fully. A final confirmation email or text message is sent once the account reflects the new identity.

    Documents Required Based on Reasons

    The specific paperwork depends entirely on the life event that caused the identity change. Brokers strictly follow these documentation rules. Preparing the right file saves a lot of time.

    1. Due to Marriage

    This is the most common reason for a profile update among investors.

    • A notary-signed copy of the official marriage certificate.
    • A scanned copy of the passport showing the husband’s name, if available.
    • Publication of the name change in the Official Gazette, which is optional but helpful.
    • An updated PAN card showing the newly adopted identity.

    2. Due to Divorce

    Reverting to a maiden name requires clear legal proof from the courts.

    • A certified and stamped copy of the legal divorce decree.
    • An updated PAN card and Aadhaar card reflecting the maiden identity.
    • A government gazette notification, especially if the identity was legally changed back.

    3. Due to Spelling Errors

    Sometimes a name is simply misspelled during the initial account opening phase.

    • self-attested copy of the PAN card showing the correct spelling.
    • self-attested copy of the Aadhaar card or passport for cross-verification.
    • A written request letter explaining the exact spelling mistake clearly.

    Adopting a completely new identity for personal or religious reasons requires strict government verification.

    • The original gazette notification published in the official Government Gazette.
    • At least two separate identity proofs with the new identity, such as a voter ID or driving license.
    • An updated PAN card reflecting the completely new name.

    5. Father’s Name Change

    If the account holder’s father officially changes his name, the linked records must also be updated.

    • A notarized copy of the official gazette notification showing the father’s new legal identity.
    • Updated personal KYC documents reflecting the new father’s name.

    Read Also: KYC Regulations Update: Comprehensive Guide

    Comparison of Name Change Categories as per Difficulty Level

    Different types of updates require different levels of effort. Gathering a gazette notification is naturally harder than submitting a basic identity card. Brokers classify these requests based on the legal proofs involved.

    Here is a direct comparison of the various categories and their difficulty levels.

    CategoryProof RequiredDifficulty Level
    Minor Spelling ErrorPAN and AadhaarVery Easy
    Marriage or DivorceMarriage Certificate or Divorce DecreeModerate
    Legal Name ChangeGazette NotificationHigh
    Father’s Name ChangeGazette NotificationHigh

    Minor corrections usually get approved very quickly because they only need basic documents. Legal changes take much more time due to the strict government gazette requirement.

    Key Points to Remember

    Keeping these essential pointers in mind will prevent application rejections. A rejected form means starting the process all over again.

    • Self-Attestation is Mandatory: Every single photocopy submitted must carry a personal signature. Brokers will immediately reject unverified and unsigned documents because they cannot prove authenticity. This simple signature serves as a personal guarantee of truth.
    • Signature Mismatches Need Attention: If the personal signature changes alongside the identity, a fresh specimen signature form is required. This specific form must be officially verified and attested by a bank manager. The bank manager confirms that the person signing is the actual account owner.
    • Joint Accounts Follow Specific Rules: In a joint holding setup, the modification process only applies to the specific person whose details changed. The details of the secondary holders remain completely unaffected. The primary holder must ensure their own details are perfect.
    • Avoid Trading During the Process: Financial experts highly recommend waiting before selling any shares. Trading actively while the profile modification is in progress can cause technical settlement failures. It is best to pause all market activities for a few days.

    Role of Depository (CDSL and NSDL)

    Depositories act like highly secure digital bank vaults for shares and mutual funds. In India, the Central Depository Services Limited (CDSL) and the National Securities Depository Limited (NSDL) securely hold these electronic assets. Brokers simply act as the service bridge between the retail investor and these main depositories.

    When an investor submits a modification request, the broker verifies the physical documents first. After thorough verification, the broker updates their internal system and sends the approved data to the depositories. The depositories then receive this update and record the changes permanently in their central database.

    Read Also: Eligibility Criteria to Open a Demat Account

    Conclusion

    By understanding the correct administrative steps and gathering the right documents, investors can complete this process very smoothly. A clean and updated profile ensures uninterrupted trading, timely dividend payouts, and highly secure investments.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1How to Find Demat Account Number from PAN?
    2Types of Demat Accounts in India
    3 Documents Required to Open a Demat Account
    4How to Open a Demat Account Online?
    5Demat Account Nomination – How to Add a Nominee?

    Frequently Asked Questions (FAQs)

    1. Can I change my name in a Demat account online?

      Yes, many brokers allow online name change through their website or app by submitting documents and a modification request.

    2. How long does a Demat account name change take?

      It usually takes 7 to 15 working days after document verification.

    3. Is PAN update mandatory before changing the name in a Demat account?

      Yes, your PAN card should be updated first because it is the primary identity proof linked to your Demat account.

    4. What documents are required for a name change after marriage?

      You generally need an updated PAN card, marriage certificate, and a valid identity proof.

    5. Can I change my surname in a Demat account?

      Yes, you can change your surname by submitting the required documents and a modification form.

    6. What happens if PAN and Demat account names do not match?

      A mismatch can cause KYC issues, transaction delays, and problems in receiving dividends.

    7. Is there any fee for name correction in a Demat account?

      Some brokers offer it free, while others may charge a small processing fee.

    8. How can I change my name in an NSDL or CDSL Demat account?

      Update your PAN card, submit the modification form with supporting documents, and complete the verification process through your broker.

  • What is a Repatriable Demat Account?

    What is a Repatriable Demat Account?

    Welcome to the world of investing in India. If you live abroad, you might be watching the Indian stock market grow and wondering how you can join the journey. It is actually very easy to invest your hard-earned money back home. The rules are clear, and the process is entirely online today. But before you start buying shares, you need the right setup. The Indian government has made special rules to help overseas Indians invest safely.

    In this blog, we will explain everything you need to know to get started.

    What is a Repatriable Demat Account?

    When you decide to invest in Indian stocks, you need a safe place to hold your digital shares. This is where a repatriable demat account comes into the picture. But before we go deep, let us understand the repatriable meaning in simple terms.

    The word repatriable simply means the freedom to move your money back to the country where you currently live. So, a repatriable account gives you the full freedom to invest your foreign earnings in India and then take both your main money and profits back abroad without any limits.

    The repatriable account meaning is tied to a specific bank account called a Non-Resident External (NRE) account. It acts as a bridge between your foreign bank and your Indian investments. When looking at the options for Non-Resident Indians (NRIs), you will often hear about repatriable and non repatriable setups. The main difference is all about moving your money out. While one lets you take funds out freely, the other restricts you. 

    What is a Non Repatriable Account?

    A non repatriable account is designed for NRIs who earn an income within India. This could be money received from property rent, a pension, or local business profits. This account is always linked to a Non Resident Ordinary or NRO bank account. Unlike a repatriable setup, you cannot freely transfer all your funds abroad at any time.

    The Reserve Bank of India allows you to transfer a maximum of 1 million dollars in a single financial year after paying the necessary taxes. It is a great choice if you want to manage your Indian earnings and invest them locally without the need to move funds overseas immediately.

    What is a Regular Demat Account?

    A regular demat account is the standard digital locker used by people who live in India. It is used to hold shares, mutual funds, and bonds in an electronic format. If you live in India, you buy shares and they sit safely in this digital vault.

    However, if you move abroad and become an NRI, the rules change for you. You cannot continue using your regular demat account. 

    How to Open a Repatriable Demat Account

    Opening your account is a simple process today. You do not need to visit a branch or deal with heavy paperwork. Here is the step-by-step guide to get you started:

    Step 1: Open a NRE Bank Account

    First, you need to open NRE bank account with an Indian bank. This account will hold your foreign income in Indian Rupees. It is the base for your entire investment journey.

    Step 2: Check NRI Investment Requirements

    Depending on your bank/brokerage house, you may require further permission and paperwork to make an investment as an NRI. Some organizations may insist on setting up a PIS-enabled account, whereas others have other options. 

    Step 3: Choose a trusted Broker

    Choose a SEBI-approved broker firm that provides the NRI trading and Demat account services at a competitive cost and ease of account opening. 

    Step 4: Submit your KYC documents

    This requires a copy of your passport, PAN card, overseas address proof, and photographs. You also need to show proof of income, like your latest bank statement or salary slip.

    Step 5: Complete Verification

    Most brokers now offer digital video verification. Once your details are verified, your account is activated. You can then link it to your NRE bank account and start trading immediately.

    Difference Between Repatriable Demat Account and Non Repatriable Demat Account

    It is easy to get confused between the two types of NRI accounts. Let us look at a simple breakdown to understand the differences clearly.

    FeatureRepatriable Demat AccountNon-Repatriable Demat Account
    Linked Bank AccountNRE AccountNRO Account
    Source of MoneyForeign income earned abroadIncome earned in India (like rent)
    Moving Money AbroadFully allowed without limitsLimited to USD 1 million per year
    Tax on Bank InterestInterest earned is tax-free in IndiaInterest is fully taxable in India
    PIS RequirementMandatory for buying stocksNot always required (Non-PIS route)

    As you can see, the first option is great for your foreign savings. The second option is better for money you earn inside India, like rent from a house.

    Features of a Repatriable Demat Account

    Here are the five key features that make this account special:

    • Digital Holding of Assets: You can securely hold Indian shares, mutual funds, and bonds in a purely digital format. There is no need to worry about losing physical paper certificates.
    • Direct Bank Linkage: Your account is directly connected to your NRE bank account. When you buy a share, the money is instantly debited from your bank.
    • Strict FEMA Compliance: Every trade you make follows the rules set by the Foreign Exchange Management Act. This keeps your investments completely legal and safe.
    • Seamless Fund Transfers: Whenever you sell your shares, the profits go straight back to your linked NRE account. From there, you can send it to your foreign bank easily.
    • No Speculative Trading: You are only allowed to do delivery-based trading. This means you cannot do intraday trading or short-term speculation, which protects your wealth.

    Read Also: What is Non-Repatriable Demat Account?

    Regulatory Framework in India for NRI Investment

    The Indian government wants to protect the economy while welcoming your investments. To do this, they have set up a clear regulatory framework in India for NRI investment.

    • Foreign Exchange Management Act: It tracks how foreign currency enters and leaves the country. By following this act, the government ensures that the Indian Rupee stays stable.
    • Portfolio Investment Scheme: The Reserve Bank of India uses this scheme to monitor the stock market. They want to ensure that foreign investors do not buy too much of a single Indian company. Under these rules, all your trades must pass through a specially approved bank branch.
    • Restriction on trades: the rules strictly say that NRIs must take actual delivery of the shares they buy. You cannot do intraday trading but F&O is permitted only on a non repatriation basis subject to SEBI regulation. This helps keep the stock market healthy and focused on long-term growth.

    Benefits of Repatriable Demat

    Investing through this route offers some fantastic perks. Here are five top benefits:

    • Unrestricted Fund Movement: You can transfer your original investment and all your profits back to your home country. There are no maximum limits on how much you can send out.
    • Tax-Free Interest: The idle money sitting in your linked NRE bank account earns interest that is completely tax-free in India. This boosts your overall returns.
    • Global Access to Markets: You get the power to invest in fast-growing Indian companies from anywhere in the world. Platforms like Pocketful let you track your portfolio on your phone at any time.
    • Portfolio Diversification: Adding Indian stocks to your global portfolio spreads out your risk. It allows you to tap into an emerging market with great potential.
    • Complete Peace of Mind: Because the system is highly regulated by the Reserve Bank of India, your money is very safe. You never have to worry about accidentally breaking Indian financial laws.

    Conclusion

    Investing in your home country is a proud and rewarding experience. India’s economy is growing at a rapid pace, and you do not have to miss out just because you live abroad. A repatriable demat account gives you the perfect bridge to connect your foreign earnings with Indian growth opportunities.

    It keeps your money safe, legal, and always ready to be moved back to your foreign home whenever you need it. By taking a few simple steps to set up your account today, you can build a strong financial future. Let your money grow with India’s success story.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Demat Account in India
    2How to Open an LLP Demat Account in India
    3What Is Power of Attorney (POA) in a Demat Account?
    4Benefits of HUF Account in India
    5FIFO in Demat: Meaning, Rules & Tax Impact

    Frequently Asked Questions (FAQs)

    1. What is the exact meaning of a repatriable demat account?

      It is a digital locker for NRIs to hold Indian stocks. It allows you to invest your foreign income in India and easily take the money back abroad later.

    2. Can I use my regular resident demat account after moving abroad? 

      No, you cannot. Once your status changes to an NRI, Indian laws require you to stop using your regular account and open an NRI-specific account.

    3. What are the main benefits of this account?

      The top benefits are that you can send your money abroad without any limits, and the interest on your linked NRE bank account is completely tax-free.

    4. How do I use a repatriable demat account to buy shares?

      First, put foreign money into your linked NRE bank account. Then, use your stockbroker platform to buy shares..

    5. Do I need special permission to open this account? 

      Yes, you need a Portfolio Investment Scheme permission letter from your bank. This letter allows you to legally trade Indian stocks as an NRI.

  • How to Open an LLP Demat Account in India: Documents & Process

    How to Open an LLP Demat Account in India: Documents & Process

    Limited Liability Partnerships (LLPs) are quite common in India. They offer flexibility along with limited liability protection. As more LLPs explore market investments, opening a dedicated Demat account becomes essential.

    A Demat account allows an LLP to hold and trade securities. This includes the options like stocks, bonds, ETFs, and mutual funds in electronic form. It helps maintain transparency, simplifies tracking, and keeps business investments separate from personal finances.

    This guide covers the complete process of opening an LLP Demat account with Pocketful, along with the required documents.

    Why Does An LLP Need A Demat Account

    An LLP can invest in financial markets, but the ownership of those investments must sit with the firm, not the partners. This is where a Demat account becomes essential. It ensures that every transaction, holding, and return is recorded under the LLP’s name, keeping financials clean and compliant.

    A dedicated Demat account allows the LLP to:

    • Hold shares, bonds, ETFs, and government securities directly in the firm’s name.
    • Participate in IPOs, rights issues, and other corporate actions without dependency on individuals.
    • Invest surplus fund in the market.
    • Ensure better tracking and management.
    • Track personal and business investments separately. 
    • Allows for simplification of audits and taxation.
    • Build a structured investment portfolio aligned with the LLP’s financial goals.

    Without a separate Demat account, managing investments at the firm level becomes unclear and difficult to track over time.

    Eligibility To Open An LLP Demat Account

    Before opening a Demat account, the LLP must meet a few basic regulatory conditions. These ensure that the entity is valid, traceable, and compliant from a financial and legal standpoint.

    The LLP should:

    • Be registered under the Limited Liability Partnership Act, 2008
    • Have an active PAN issued in the name of the LLP
    • Be compliant with MCA filings, including annual returns and financial statements
    • Have a valid registered address with supporting proof

    In addition to firm-level eligibility, all designated partners must complete their individual KYC. This is a mandatory step, as partners are responsible for operating and authorising transactions on behalf of the LLP.

    Read Also: What is Corporate Demat Account?

    Documents Required To Open An LLP Demat Account

    When you apply for the LLP demat account, having proper documents is a must to avoid delays. These are at low levels, which are shared below.

    Firm Level Documents

    DocumentDetails
    LLP PAN CardUsed for tax identification and must match the LLP name exactly
    Certificate Of IncorporationProof of legal existence issued at the time of registration
    LLP AgreementDefines partner roles, responsibilities, and contribution structure
    Address ProofBank statement or utility bill not older than 3 months
    FinancialsLast 2 years, audited balance sheet or CA-certified net worth certificate
    Board ResolutionAuthorises account opening and clearly names authorised signatories
    List Of Designated PartnersOn LLP letterhead with names and details
    List Of Authorised SignatoriesRequired if different from designated partners
    Contribution PatternShows the capital contribution of each partner

    Partner Level Documents

    DocumentDetails
    PAN CardMandatory for identity verification
    Aadhaar CardUsed for KYC and address validation
    PhotographRecent passport-size photo
    SignatureScanned or physical as required for verification

    Tip: Ensure all documents are self-attested. Firm documents should also carry the LLP seal where applicable.

    Steps To Open An LLP Demat Account

    Opening a Demat account for an LLP has some additional steps. The process is structured. All you need to do is ensure that the verification completes in time. The steps to follow are:

    Step 1: Contact The Broker Or Depository Participant

    Begin by reaching out to the broker or depository participant for a non-individual account opening request. LLP Demat accounts usually require a separate onboarding process, so direct coordination with the support or onboarding team is generally needed.

    Step 2: Prepare And Verify Documents

    Collect all firm and partner documents. Ensure that this is as per the checklist. Ensure names, addresses, and signatures match across all records to avoid delays during verification.

    Step 3: Submit The Application

    Fill out the account opening form and submit it along with supporting documents. This may be done digitally or through an assisted process, depending on the case.

    Step 4: Complete In-Person Verification

    IPV is mandatory for LLP accounts. This can be done through a video call or physical verification. The authorised signatory must be present with the original documents.

    Step 5: Complete Partner KYC

    Each designated partner must complete individual KYC. This includes PAN verification, Aadhaar validation, and identity confirmation as per regulatory requirements.

    Step 6: Account Activation

    Once all checks are completed, the account is activated. Login credentials and trading access are shared, allowing the LLP to start investing.

    Read Also: Documents Required to Open a Demat Account

    Tips To Avoid Rejection

    Most LLP Demat account applications get delayed due to small errors. A careful review before submission can help you avoid rejection and speed up approval. Some of the tips to follow are:

    • Ensure the LLP name is correct on all the documents, like PAN, incorporation certificate, and bank records.
    • Ensure the details of the partners are correct.
    • Check the names and rest details before applying.
    • Draft the Board Resolution clearly.
    • Have authorised signatories and their roles defined.
    • Ensure proofs are the latest and no longer than 3-6 months old.
    • Submit clear, readable document scans without cuts or blur.
    • Sign and stamp all required documents properly before submission.
    • Complete KYC for all designated partners without leaving any pending steps.

    Conclusion

    Opening a Demat account for an LLP is more about getting the basics right than dealing with a complex process. Once your documents are in order and partner KYC is complete, the rest moves smoothly.

    With Pocketful, the process is guided and structured, making it easier for LLPs to start investing without confusion. From equities to ETFs and beyond, your firm can build and manage its portfolio with clarity and control.

    If you are planning to put your business funds to work, this is the first step. Get started with Pocketful and set up your LLP Demat account today.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Demat Account in India
    2Lifetime Free Demat Account (AMC Free)
    3Demat Account: Fees & Charges
    4How to Close Your Demat Account Online?
    5Features and Benefits of Demat Account
    6Types of Demat Accounts in India
    7How to Use a Demat Account?
    8How to Buy Shares through a Demat Account?
    9Joint Demat Account
    10BSDA – What is a Basic Service Demat Account?

    Frequently Asked Questions (FAQs)

    1. Can An LLP Open A Demat Account In India?

      Yes, an LLP is treated as a separate legal entity and can open a Demat account in its own name. The account must be linked to the LLP’s PAN, and all designated partners are required to complete KYC as part of the process.

    2. How Many Partners Need To Complete KYC?

      All designated partners must complete individual KYC. These partners are responsible for authorising and operating the account, even if only a few are assigned as signatories in the Board Resolution.

    3. Is A Board Resolution Mandatory For Opening The Account?

      Yes, a Board Resolution is a mandatory document. It formally authorises the LLP to open a Demat account and clearly defines who can operate it on behalf of the firm.

    4. What If The LLP Does Not Have Financial Statements?

      If the LLP is newly formed and does not have audited financials, a net worth certificate issued by a Chartered Accountant can be submitted instead.

    5. Can An LLP Trade In F And O Segments?

      Yes, once the account is activated, an LLP can trade in equity delivery, intraday, and derivatives. This depends on the segments enabled and regulatory requirements.

  • What Is Power of Attorney (POA) in a Demat Account? 

    What Is Power of Attorney (POA) in a Demat Account? 

    To make your investments and trade in the stock market you require a Demat account. This account acts like a digital locker for your shares. While setting this account up you must have heard about the POA full form which stands for Power of Attorney. 

    Most of the new investors are curious about what is POA and why POA is needed. It is a type of a document that allows the broker the right to move shares out of your account when you sell your shares.

    When an investor signs this document they get a unique record on your account. The POA number depicts the specific code which tracks this legal agreement between the investor and the broker. Using a POA in share market trades makes life much easier for you as an investor. 

    What Is Power of Attorney (POA) in a Demat Account?

    POA acts as a permission slip where it gives the right to the broker that they can take shares from your account only when you decide to sell them. Here you are still the owner of your shares. The broker is just the person who helps move them from your locker to the buyer.

    Let us understand this with an example, let’s say that being the owner of the car you have put your car in a safe locked space. And if you are looking to sell your car you must have to go to that space, take out your car and drive it to deliver it to the buyer. But this will take a lot of time and effort.

    But what if you have given a “Specific Power of Attorney” to the owner of the garage and you have given them a spare key, but they can only use it if you send them a message saying, “I have sold the car, please deliver it to the buyer.” The manager cannot use your car for personal trips or sell it to anyone else without your order. In the stock market, your broker is the garage manager and the POA is that spare key.

    The role of a POA is to handle the “debit” or the outgoing side of your trades. When you buy shares, you don’t need a POA because the shares are coming into your account automatically. This is only required when you sell, transfer or pledge your securities. The main task that it looks for is moving up shares to the stock exchange or use them as a guarantee to get extra money for trading.

    How Does POA Work in a Demat Account?

    The process begins when the investor signs the POA form when you open your account. Your broker then records this permission in their system. This is how you get connected with your digital signature to the actual share holdings.

    Wherever you open the app and want to sell your shares you just click on the “sell” button and the broker acts on your behalf. Here the broker looks at the sell order and as per rights given under POA the broker asks the depository (like NSDL or CDSL) to move the shares from sellers account to the buyers account. The depository checks if the POA is valid and then transfers the shares to the exchange so the buyer can get them.

    The broker or Depository Participant (DP) behaves like a helping hand. Their job is to follow your orders as it is. They are guided by strict rules from SEBI. The POA is only triggered when you take an action, like selling a stock or pledging shares to get more trading margin. Without your sell order, the broker cannot move anything.

    Types of Power of Attorney in Demat Accounts

    There are mainly two types of POA that every investor should know about. One is very common, and the other is something you should usually avoid for basic investing.

    1. Specific (Limited) POA

    This is the standard version used by almost everyone. It gives the broker permission to do only 4 or 5 specific things. These include selling your shares, pledging them for margin, or helping with mutual fund transfers. It is valid as long as your account is open, it is a safe option as there are limitations on what the broker can act upon. 

    2. General POA

    A General POA is very broad in nature as it gives the person holding it the power to do almost anything on your behalf. They could open new accounts or move your money around. This is rarely used in the stock market unless you are using a high-end service where a professional manages everything for you. For a normal investor, this is not recommended.

    Read Also: What is Demat Debit and Pledge Instruction (DDPI)?

    Why Do Brokers Ask for POA?

    Brokers ask for a POA to make sure your trades don’t get stuck by some minor mistake. In the Indian market, everything moves very fast. When you sell a share today, it must reach the exchange very quickly.

    • Quick and Easy Settlement: The POA allows the broker to send your shares to the buyer immediately, which helps in avoiding penalties for the late delivery.
    • Ease of Trading: Without a POA, you would have to give a physical or digital slip for every single sale. If you trade ten times a day, doing this manually would be very annoying and could lead to some mistake.
    • Margin Trading: If you want to trade with more money than you have in cash, you can “pledge” your shares as a guarantee. The POA makes this process instant and hassle free.
    • No Repeated Approvals: It is a one time procedure where once you sign it, you don’t have to worry about the paperwork every time you book a profit.

    Is POA Mandatory for a Demat Account?

    Many people think they must sign a POA to open an account, but that is not true. According to SEBI guidelines, a POA is completely optional and investors can open a Demat account and start investing even without it.

    If you choose not to give a POA, you can still sell your shares. However, you will have to use a system called “e-DIS.” In this system whenever you would like to sell your share you have to manually enter a 6 digit TPIN and for final verification an OTP will be shared to your registered mobile number.

    Recently we have seen that brokers have opted for a new safe option known as DDPI (Demat Debit and Pledge Instruction) which works like the limited POA (limitations on broker) but this option has tighter restrictions and is more secure for the investors. You can either opt for POA, DDPI or can sell the shares manually using the TPIN method. 

    Benefits of Giving POA

    Here are multiple perks if you give a POA to a trusted broker like Pocketful.

    • Fast Execution: The shares that you have sold reach the buyers account within time and you avoid the short delivery fines (if not shared within time). 
    • Zero Paperwork: No physical slips or couriers are required to be shared with your broker, just sign the POA one time and you can stay care free. 
    • Better Opportunities: As there is a rapid fluctuation in the market by giving a POA you can sell your shares instantly the moment you get the right price. 
    • Simple Pledging: The extra shares in your demat account can give you extra limits for intraday or F&O trading. 

    Risks and Concerns of POA

    Trust Factor: Here the biggest concern is that you are giving powers directly to your broker to move your shares on your behalf but if the broker is not honest at any moment then there is a risk of misuse.

    • Old Formats: Earlier POA forms had a broad spectrum to cover but modern versions like DDPI are much more reliable and safe for the investors. 
    • Monitoring: One shall always check their account statement and SMS alerts to monitor if the movements are correctly done or not. As here you would have to give a penalty if something goes wrong. 

    Read Also: FIFO in Demat: Meaning, Rules & Tax Impact

    How to Give (Execute) POA for a Demat Account

    To activate POA for your trading account you would need to follow the given steps:

    • Registration Form: The first step is to download the POA or DDPI form, from the broker’s website. 
    • Fill the Details: Here you need to put your name and provide your 16-digit Demat account number.  
    • Check the Limits: One should always cross check that you are only giving rights for tasks like “settlement” and “pledging”. 
    • Sign Online or Offline: You can opt if you want to e-sign via mobile number (aadhar linked) or go for the offline method.
    • Get Confirmation: You will receive an email of confirmation as soon as the depository registers your POA.

    Safety Tips Before Granting POA

    Before you sign any document, keep these tips in mind to stay safe:

    • Reputation Matters: One should only rely on brokers that are registered with SEBI and also have a decent track record. 
    • Read the Clauses: Always cross check before signing the final document and be cautious about any clause that states or gives the broker the power to handle your bank account or give total control over the account. 
    • Track Alerts: Always pay attention to the SMS and emails you get from NSDL or CDSL.
    • Nominee is a Must: Nominee is a must add for your account as this keeps your family protected. 

    Read Also: What is a Basic Service Demat Account?

    How to Revoke or Modify POA

    You have the power to cancel your POA at any time you feel so. It does not bind you for a fixed period of time.

    • How to Revoke: A formal written request needs to be shared with your broker for revoking the signed document although some brokers even let you do this process online by e-signing the revocation letter/form.
    • How to Modify: If any changes required the old POA needs to be cancelled and a fresh POA needs to be signed as per the new conditions. 
    • Processing Time: The revocation request can be usually processed within 3 to 5 working days, once done you have to only use your TPIN and OTP for selling your shares. 

    Conclusion

    Power Of Attorney is a tool that is designed to help the investor to ease down their trading faster and easier. It acts as a helping assistant for moving your sold shares to the buyers account, so that investors like you can focus on planning your next move rather than focusing on the timely movements of shares. Although this is optional, most of the traders prefer this as it relieves the investors from risk of penalties due to delayed procedure or any technical fault. By staying alert and choosing a transparent platform like Pocketful, you can trade with peace of mind and keep your costs low.

    For more market news and insights, download Pocketful – offering users zero brokerage on delivery trades and an easy to use platform designed for both beginners and experienced investors Pocketful.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Types of Demat Accounts in India
    2Features and Benefits of Demat Account
    3What is TPIN in Demat Account?
    4How to Open a Demat Account Online?
    5Top 10 Demat Account in India
    6How to Use a Demat Account?
    7What is Non-Repatriable Demat Account? Meaning and Definition
    8How to Open an NRI Demat & Trading Account in India
    9What is a Minor Demat Account? Meaning, Features & Benefits
    10How to Enable Two-factor Authentication in Demat Account?

    Frequently Asked Questions (FAQs)

    1. Is POA mandatory to open an account?

      No, accounts can be opened without it. You will just have to manually enter your TPIN and OTP every time you make a sell trade. 

    2. Can the broker sell my shares without my order?

      No the brokers are bound with only certain things in which they can act, legally the POA only works when you place a sell order yourself. The broker cannot just decide to sell your holdings on their own.

    3. What is a POA number?

      This is a unique reference number that is linked to your agreement that has been signed between you with the broker. It is stored with the depository to show that the broker has permission to move your shares.

    4. Is the new DDPI system better than POA?

      Yes, DDPI is considered safer as there are more limitations to the broker’s task and it can easily be digitally signed. This is a modern version of a POA which is recommended by SEBI.

    5. Can I cancel my POA later?

      Yes, you can easily revoke or cancel your POA at any time by simply informing your broker through a written or digital request. 

  • Open Free Demat Account

    Join Pocketful Now

    You have successfully subscribed to the newsletter

    There was an error while trying to send your request. Please try again.

    Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.