Category: Mutual Funds

  • How to Sell Mutual Funds to Your Clients

    How to Sell Mutual Funds to Your Clients

    When a client comes to invest in mutual funds, they often have several questions in mind such as which fund to choose, how much to invest, and what might happen if they incur a loss. As a mutual fund distributor, your role goes beyond merely selling funds; it also involves providing the right answers to these questions. Let’s explore how to engage with a client and help them make an informed investment decision.

    Know Your Client Before Pitching a Mutual Fund

    Before offering any mutual fund, sit with the client and ask simple questions to get what they’re looking for. Find out their reasons for investing, how much they earn, and when they’ll need the cash back. Getting these details upfront makes it clear what actually suits them.

    • Investment Goal: Find out why they want to save. Are they saving to buy a home, pay for their children’s school, or build a fund for retirement? When you know their main goal, picking the right option gets simple.
    • Investment Period: Find out their timeframe first. If they need cash back in just two or three years, walk them through short-term risks and exit penalties before pushing long-term options.
    • Risk Tolerance: Market dips don’t bother everyone, but some clients panic over any small drop. Have an honest chat about this early on so you don’t end up picking funds that stress them out. 
    • Monthly Budget: Find out how much they can put away each month without stress. Don’t push a huge SIP on them right away; pick an amount they can stick with after taking care of their everyday expenses.
    • Existing Investments: If they already own mutual funds, take a look at what they have. They might not need another fund at all, or they might already own something that overlaps.
    • Need for Money: Find out if they might need quick cash in the near future. If that’s a chance, explain how long payouts take and break down any exit penalties or lock-in rules so there are no surprises.

    How to Choose the Right Mutual Fund for Your Client 

    Once the client’s needs are understood, the next step is to select the right mutual fund. It is not enough to simply look at the returns a fund has generated; consider the following factors when making a selection:

    1. Pick the Right Fund Type: Go with equity funds if your client is staying in for the long haul. For index tracking, look at index funds. Just line up their timeline and risk comfort before settling on any category.
    2. Look Beyond Recent Returns: Don’t judge a scheme off just one good year. See how it held up against its benchmark over several years instead. And reminding them of past performance isn’t a promise of future gains.
    3. Check the Riskometer: Always check the Riskometer first. If a client can’t stand big dips, don’t throw high-risk funds at them without making sure they get the downside.
    4. Compare Expense Ratios: Fees vary across schemes. When you’re comparing two similar funds, check their expense ratios side by side. Show them why Direct plans cost less than Regular ones so they see where the money goes.
    5. Know What the Fund Holds: You ought to know what stocks or bonds the fund actually owns. It makes it way easier to explain where their money is sitting and what might bump the returns up or down.
    6. Check Exit Load and Lock-in: When explaining mutual funds to a client, their primary interest is often the potential returns. However, simply stating how much a fund has earned is not enough. The client must also be aware of the risks such as the possibility of a decline in value—and the costs associated with the investment.
    7. Show What the Fund Has Actually Delivered: Present the fund’s returns to the client, but do not limit the data to a single year. Show performance over various timeframes and compare it against the relevant benchmark. This will give the client a clearer picture of how the fund has performed.
    8. Talk About the Chance of Losing Money: If a client is new to mutual funds, show them what a market dip actually looks like. For instance, a ₹50,000 investment could temporarily slip down to ₹45,000. Ask them how they’d feel seeing that drop and check when they might need to withdraw their money.
    9. Be Upfront About All Charges: Clients hate finding out about extra charges after they’ve already put money in. Walk them through the expense ratio and exit loads right at the start. When comparing Direct and Regular plans, lay out the cost difference clearly along with the support you offer.
    10. Avoid Promising Fixed Returns: When clients ask how much their money will grow in a year, don’t throw out exact numbers. Tell them returns shift with market conditions and performance. Make it clear that while investments can grow, there is always a chance of losing money too.

    Read Also: What is Trail Commission in Mutual Funds?

    How to Sell Mutual Funds Online 

    To sell mutual funds online in India, you must first complete the necessary certification and registration. Once this is done, you can explain various schemes to clients and assist them with investment transactions in compliance with the regulations.

    Step 1: Clear the NISM Series V-A Test

    You have to pass the NISM Series V-A Mutual Fund Distributors exam first. The test checks if you know your stuff when it comes to fund types, market risks, rules, and how selling works. 

    Step 2: Obtain Your AMFI Registration (ARN)

    After passing the exam, apply for an ARN (AMFI Registration Number) through AMFI. You will need to submit the required documents and fulfill the registration criteria. You may begin your activities as a distributor only after receiving your ARN.

    Step 3: Complete AMC Empanelment

    Complete the necessary empanelment process with the Asset Management Companies (AMCs) whose schemes you intend to distribute. Each AMC may have its own specific procedure.

    Step 4: Complete Client KYC

    Check your client’s KYC before doing any trade. If it’s pending, get their paperwork completed first as per the rules.

    Step 5: Suggest the Right Fund

    Check your client’s target, investment timeline, and risk level before pointing them to a fund. Also, clearly show them the fund’s riskometer rating, expense fee, and exit rules.

    Step 6: Execute the Transaction

    Submit the transaction with the client’s consent. Ensure that the ARN and EUIN (where applicable) are correctly provided, and share the transaction confirmation with the client.

    SEBI and AMFI Rules Every Distributor Must Follow

    Besides guiding clients on investments, mutual fund distributors have to stay on top of their registration details and follow basic regulatory rules. There are a few key tasks you must complete on time to keep your practice running smoothly:

    • Maintain the validity of your ARN: Keep track of your ARN’s expiry date and ensure it is renewed on time. If an ARN expires, your distribution activities and commission-related operations may be adversely affected.
    • Provide accurate EUIN information: Whenever applicable, make sure you put down the right EUIN of the employee or relationship manager who actually talked to the client for each transaction. Entering wrong or partial details can quickly lead to compliance trouble.
    • Submit the Annual Declaration on time: Following AMFI rules, every ARN holder has to turn in a ‘Declaration of Self-Certification’ (DSC) right after the financial year wraps up. Be sure to file this within the given deadline, or any delay could hold up your commission payouts. 
    • Complete the empanelment process with AMCs: Before distributing schemes offered by any AMC, ensure that you have fulfilled all their specific empanelment requirements. Simply holding an ARN does not automatically grant authorization to distribute schemes from all AMCs.

    Read Also: What is Mutual Fund Unit and How does it Work?

    Conclusion

    Finding clients isn’t the hardest part of selling mutual funds. What’s really tough is picking the right fund for each person. People almost never invest on day one, and no single fund works for everyone. So when you talk about a fund, don’t just share the upside. Be clear about the risks too. That way, clients can decide with confidence and won’t feel regret down the road.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. How can I start selling mutual funds in India?

      You need to clear the NISM Series V-A exam first. After that, get your ARN number from AMFI and sign up with the fund houses you want to deal with.

    2. How do I sell mutual funds online?

      Pick a good online investment platform, explain the funds to your clients through it, and submit their orders once they agree.

    3. Can I Sell Mutual Funds Anytime?

      Open-ended funds generally offer a redemption facility; however, lock-in periods, exit loads, and specific scheme terms and conditions may apply.

    4. How do I pick the right fund for a client?

      Look at what they want to achieve, how many years they plan to stay invested, how much market drop they can handle, and what the fund charges as expense ratio.

    5. Do Mutual Fund Distributors Earn Commission?

      Yes, distributors can earn a commission in accordance with AMC policies on eligible investments made through ‘Regular’ plans.
  • Can Mutual Funds Give Negative Returns?

    Can Mutual Funds Give Negative Returns?

    Mutual funds are a pretty popular choice for investors who are looking to grow their money using professional investment expertise. They offer a way to get into a whole range of different investments, like shares, bonds and other financial products. But, unfortunately, they don’t come with any guarantees – they don’t promise you’ll make a profit!
    The question, Can Mutual Funds Give Negative Returns, is therefore important to understand before investing.

    So, can mutual funds really give you a loss? Yes they can. Mutual fund investments can go down in value when the underlying stocks or bonds do poorly or when market conditions just aren’t good. The amount of the loss depends a bit on the fund’s investment strategy, the mix of stocks it holds, and how much risk it’s taking on overall.

    Understanding why this happens is actually pretty useful for investors – it can help them make more informed decisions and not get spooked when the market gets a bit bumpy.

    Can Mutual Funds Give You Negative Returns?

    Yes, mutual funds can definitely generate negative returns over both the short and long term. The value of the fund – its Net Asset Value, or NAV – gets adjusted according to the market value of the stocks it holds in its portfolio.

    If you put in ₹10,000 into a mutual fund and its value then fell by 10%, you’d be left with ₹9,000. That’s a loss of ₹1,000 – excluding any charges or taxes, of course.

    Mutual fund losses can happen in lots of different places. Equity funds, for example, might fall if stock prices start going down. Debt funds might lose value because of changes in interest rates or defaults on loans, or because they’re having trouble selling their holdings. Hybrid funds might experience losses from the value of both their shares and their bonds.

    The Association of Mutual Funds in India (AMFI) actually says that mutual fund schemes aren’t guaranteed-return investments – their values can go up or down depending on the market and how the underlying investments do.

    Why Do Mutual Funds Give Negative Returns?

    There are a whole bunch of factors that can cause a mutual fund to go down in value. And if you can understand these factors, you can get a better handle on the risks before you invest.

    1. Stock Market Volatility – the ups and downs of the market

    Equity mutual funds are all about investing in shares. So their performance is directly linked to how well the market is doing.

    When the market drops because of worries about the economy, geopolitical events or weak company profits, the value of the shares in the fund can drop too. This can reduce the value of the fund as a whole and give you a negative return.

    For example, say a fund has put a lot of its money into shares of banks. If the market thinks the banking sector is in trouble, the value of those shares will probably fall.

    2. Interest Rate Changes

    Interest-rate changes can really knock debt mutual funds for a loop. When interest rates go up, bonds that used to look pretty good may suddenly lose their appeal. Their value might even plummet, and that’s bad news for funds that hold onto them.

    The impact varies depending on what kind of bonds are in the fund, when they’re set to expire and the fund-manager’s overall strategy. Funds that are super sensitive to changes in interest rates will probably see bigger price swings.

    3. Credit Risk

    Debt mutual funds often invest in securities issued by other companies and lenders. But if the borrower is having financial troubles or just can’t make payments on time, it can be a real problem for the fund. This is what’s known as credit risk. And funds that have invested in shakier borrowers will be in a tougher spot than those that play it safer.

    If you’re investing in a debt fund, its a good idea to have a close look at the holdings and get a handle on the risks involved.

    4. What Happens When The Underlying Investments Go South

    A mutual fund’s performance is only as good as the investments it owns. And if those investments aren’t doing well, the fund probably won’t either. Let’s say you’ve got a tech-sector fund and all of a sudden tech companies are struggling – your fund will likely struggle right along with them.

    Even if you spread your investments out across different sectors, there’s still no guarantee you’ll avoid every potential risk.

    5. What Economic And Political Uncertainty Means For Your Mutual Fund

    We all know that economic slowdowns , policy changes, inflation and global conflicts can really rattle the markets. They can affect investor confidence, business performance and the prices of assets. And if your mutual fund has invested in any of those affected securities, it may experience some pretty rough times ahead.

    6. Watching Out For Investment Costs

    Mutual funds have all sorts of expenses that come with managing the fund and keeping it running. Those costs get added right to the funds net asset value. Even if your investments are generating some decent returns, those costs can cut into your bottom line. And if the portfolio is performing poorly, the costs can just make things even worse.

    Which Mutual Funds Can Give Negative Returns?

    Different mutual fund categories have different risk profiles. However, no market-linked category is entirely free from the possibility of losses.

    Mutual fund categoryWhy negative returns may occur
    Equity fundsFalling share prices and weak corporate earnings
    Small-cap and mid-cap fundsGreater price volatility and market uncertainty
    Debt fundsInterest-rate changes, credit defaults and liquidity risks
    Hybrid fundsDeclines in equity or debt investments
    Sectoral and thematic fundsPoor performance in a specific industry or investment theme
    Index fundsDeclines in the benchmark index being tracked

    The possibility and extent of losses depend on the scheme’s investments and market conditions. Investors should read the scheme information document and review the riskometer before investing.

    What Should You Do When Mutual Funds Give Negative Returns?

    Seeing your investment value take a tumble can be a real source of worry. But selling off immediately usually isn’t the right move. Before making any changes to your portfolio take a step back and think about the following steps.

    1. Get Your Investment Goals Back Into Focus

    Take a look at what you were thinking when you invested in the fund in the first place. Was it for some short term expense, a big home purchase or something more long term like retirement?

    Your investment horizon really matters. If you’ve got a long time before you need the cash, short term declines might not be the end of the world, even if there’s no guarantee things will turn around. But if you need that cash sooner rather than later, you need to ask yourself whether the fund is still a good fit for you.

    2. Take a Look At How The Fund Has Been Performing

    Compare the performance of the fund to its benchmark and how it stacks up against other funds in the same category over a decent time period.

    One time a fund is underperforming might have one explanation, and another time it might be something different. You also want to take a look at the fund’s portfolio, investment strategy, the people in charge, and just how much you’re paying in fees. Don’t make a decision based on just the latest numbers.

    3. Don’t Panic Sell

    Market volatility can be pretty tempting to get out at the wrong time – when prices are low. But selling can turn a paper loss into a real one. Before you pull your units, think about your goals, your time horizon and just why the fund is underperforming. If the fund just doesnt suit your needs any more, maybe its time to think about something different.

    4. Don’t Overstay Your Welcome with a Systematic Investment Plan

    A Systematic Investment Plan lets you invest a set amount of cash at regular intervals – its a great way to get in the game even when prices are low, and your money can buy more units. But just because you keep chugging along with your regular investments doesn’t mean the market is going to suddenly turn around in your favour. Before you invest another dollar, do a reality check on the fund and your personal finances.

    5. Spread the Risk Around with Diversified Investments

    Investing in a few different asset classes and market segments is a smart way to mitigate risk. There’s no one-size-fits-all answer, so you’ll need to think about combining some equity and debt investments based on your goals and what your risk level is. The right mix will depend on your individual circumstances, and that can take some figuring out.

    Diversifying can help you manage risk, but it won’t erase all your losses – unfortunately.

    6. Take A Close Look At Your Portfolio Every Now and Then

    Rather than reacting to every little market movement, take a close look at your investments on a regular basis. Ask yourself if your portfolio still aligns with your goals and risk tolerance. If you’re not sure what to do next, maybe its a good idea to grab some advice from a qualified financial adviser – they can help you make sense of things.

    Read Also: Top Reasons Why Mutual Funds Are Going Down

    How to Reduce the Risk of Negative Mutual Fund Returns

    Investors can’t eradicate market risk, but they can take steps to manage it.

    • Know Your Limits: Select plans according to your capacity to absorb losses.
    • Make a realistic time horizon for investment: It is best to refrain from engaging in the equity market with funds that must be available shortly.
    • Due Diligence Prior to Investment: Look into the investment goal, the portfolio, the fees involved and the risks prior to putting in your funds.
    • Diversification is Key: Refrain from placing all your eggs in one basket – diversify your portfolio among different sectors and asset classes.
    • Have an Emergency Fund: Ensure that you keep some extra money for unforeseen purposes – preferably separate from your investments in the market.
    • Review the Performance Periodically: Evaluate your investments on the basis of appropriate benchmarks and changes since your last evaluation.

    Buying Mutual Funds on Pocketful: A Step-by-Step Guide

    If you’re thinking about putting some money into mutual funds, Pocketful is a great place to start – they’ve got a load of schemes to browse through and ways to invest big or small.

    Here’s how to get started:

    1. Head over to Pocketful: Just pop over to the Pocketful Mutual Funds page – it’s where the magic happens.
    2. Get an account: Follow the usual routine to get yourself set up with a new account – it’s pretty straightforward.
    3. Get your KYC sorted: Fill in all the Know Your Customer details and get verified – this is a one-time thing, and you won’t have to do it again.
    4. Start looking around: Take a gander at all the different schemes – what are their goals, what kind of risk are they carrying, what’s in the portfolio, how much does it cost, and how long is this for?
    5. Time to pick a plan: Will you be investing a bit every month or all at once? Either way, make sure it fits with your overall cash plan.
    6. Get familiar with the details: Read the scheme information documents – and don’t just gloss over it, take a good, hard look – because this is your money we’re talking about.
    7. Get invested: Follow the instructions on the site and keep an eye on how your investments are doing.

    You can also use the tools on the site to help you compare the different funds – these will give you some ideas, but don’t be fooled into thinking they’ll magic up a winning strategy.

    And yes – before we go, be aware that using these comparison tools is a big help, but at the end of the day they won’t magically solve every problem – only you can do that.

    Conclusion

    Mutual Funds can give you a losing return because their value depends on the performance of what they’re invested in, and the state of the markets. Markets can be volatile, interest rates can go up and down, and there’s always a risk that someone won’t be able to pay back their loan. Economic uncertainty can all contribute to you losing money.

    The main thing is to get a good handle on the risks involved before you put in your money, and make choices based on your own goals, how long you can leave your money locked up, and how much risk you’re willing to take on. Try not to make decisions based on short-term market movements, and review your portfolio from time to time.

    If you’re looking for a Mutual Fund, you can take a look at options through Pocketful and compare them before you invest. Just remember, all investments carry risk, and no Mutual Fund can promise you a profit.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Trail Commission in Mutual Funds?
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. Can Mutual Funds Give You a Losing Return?

      Yes, they can. Mutual Funds can lose money when the things they invest in start to decline in value. Just how much you lose depends on what kind of fund you’re in, what’s in your portfolio, and what the markets are doing.

    2. Can You Lose Your Whole Investment in a Mutual Fund?

      It’s not impossible to lose a big chunk of your money in a mutual fund. How likely that is depends on which scheme you’re in. Don’t assume your money is automatically safe – take some time to understand the risks of a scheme before you put your money in.

    3. Will Mutual Funds Ever Recover from a Market Crash?

      Some of them might, if the things they’re invested in do well again. But don’t count on it happening – the outcome depends on what’s in the portfolio and how the market performs from then on.

    4. Should You Stop Putting Money into a Mutual Fund When the Returns Get Bad?

      Not necessarily. Take a step back and think about your goals, how long you can afford to keep your money locked up, and whether the scheme you’re in is still suitable for you. A Systematic Investment Plan (SIP) isn’t a guarantee that you’ll get a profit, or that you won’t lose money.

    5. Which Mutual Funds are the Least Likely to Lose You Money?

      The risk of a scheme varies depending on which one you choose. Some debt funds might be less volatile than equity funds, but they still come with risks – like the chance that a borrower won’t pay back their loan, or that interest rates will go up. Try to pick a scheme that matches your needs rather than relying on a label like “low-risk”.

  • Feeder Fund: Meaning, How It Works, Benefits & Risks

    Feeder Fund: Meaning, How It Works, Benefits & Risks

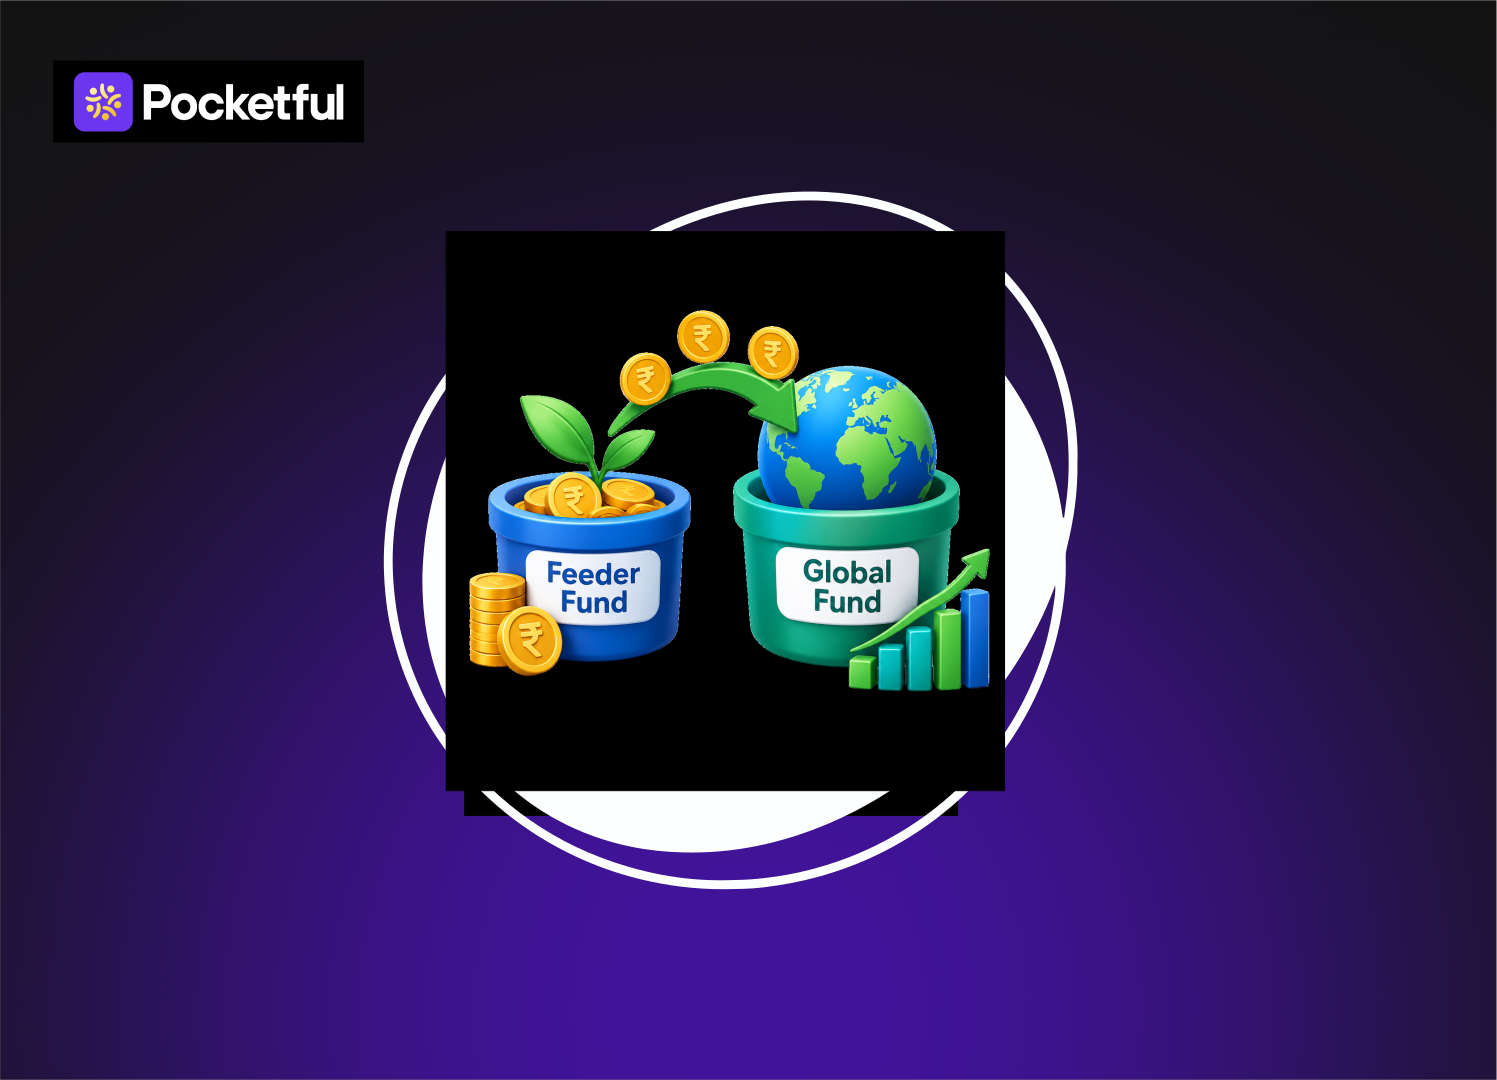
    A feeder fund collects money from investors and invests it into another fund. This fund is known as the master fund. This then invests in pool of shares, bonds or other securities.

    This type of fund can help the investors gain access to overseas markets easily. The investment is usually through a domestic mutual fund. While this is the basic, it is important to understand what is feeder fund in proper details now. So, read this guide to know more.

    What Is a Feeder Fund?

    The feeder fund meaning is simple when you follow the money. You invest in the feeder fund, but it usually does not build its own portfolio of individual securities. Instead, it invests most of its assets in a master or underlying fund.

    The master fund manages the actual portfolio and takes investment decisions. Its gains or losses are reflected in the feeder fund’s NAV after accounting for expenses and other applicable factors.

    In India, many international mutual fund schemes use a feeder or Fund of Funds structure. AMFI includes both overseas funds and Fund of Funds among recognised mutual fund scheme types.

    How Does a Feeder Fund Work?

    A feeder fund uses a two-level structure. Investors enter through the feeder fund, while most investment activity happens at the master fund level.

    The process generally works like this:

    1. Investors put money into the feeder fund.
    2. The feeder fund pools these investments.
    3. It buys units of the selected master fund.
    4. The master fund invests according to its stated strategy.
    5. Gains or losses affect the feeder fund’s NAV.
    6. Investors redeem feeder fund units when they want to exit, subject to scheme rules.

    This structure allows one master portfolio to receive money through different feeder funds. It can also help centralise portfolio management.

    What Is the Difference Between a Feeder Fund and a Master Fund?

    The feeder fund provides the route through which investors enter the structure. The master fund is where the underlying portfolio is generally managed.

    FeatureFeeder FundMaster Fund
    Main roleCollects investor moneyInvests pooled money
    Direct securitiesUsually limitedHolds the main portfolio
    Investor accessInvestors buy feeder unitsMay not be directly available
    NAVDriven largely by underlying fundDriven by portfolio securities
    PurposeProvides accessRuns the strategy

    For example, an Indian feeder scheme may invest in a US-based master fund. Investors can invest in rupees while getting exposure to companies listed abroad.

    Franklin Templeton’s Franklin U.S. Opportunities Equity Active Fund of Funds is one current example. It invests at least 95% of its assets in Franklin U.S. Opportunities Fund.

    Feeder Fund vs Fund of Funds: Are They the Same?

    A feeder fund and a Fund of Funds, or FoF, are closely related but not always the same. A FoF is a broader category that invests in other funds rather than directly in securities.

    A feeder fund usually channels most of its money into a specific master fund. A FoF may invest across several mutual funds, ETFs or strategies.

    BasisFeeder FundFund of Funds
    Typical structureMainly one master fundOne or several funds
    Main purposeAccess a specific strategyCombine underlying funds
    Portfolio decisionsMainly made by master fundFoF manager may allocate across funds
    Common useInternational or specialised exposureAsset allocation, gold, international or multi-manager

    In India, a feeder fund may operate as a Fund of Funds scheme. Always read the Scheme Information Document instead of relying only on the scheme name.

    Read Also: Floater Debt Funds: Benefits, Risks & Taxation in India

    What Are the Advantages of Feeder Funds?

    Feeder funds can be useful when they provide access to a wide range of markets and strategies. It is something that will help you to add the to your wealth portfolio creation. Some of the key advantages that you should know are as follows:

    1. Access to International Markets

    An international feeder fund can provide exposure to overseas companies through an Indian mutual fund. You invest in rupees and do not need to select foreign stocks yourself.

    This can be useful if you want geographical diversification within your overall portfolio.

    2. Professional Fund Management

    The master fund is managed by a professional investment team. This may help when the strategy needs specialised knowledge of another market or asset class.

    However, the feeder fund remains dependent on the underlying fund’s investment decisions and performance.

    3. Easier Diversification

    Some feeder funds provide exposure to countries, sectors, or investment styles with limited representation in India. This helps with the diversification and can help you with building a growing portfolio. 

    What Are the Risks of Feeder Funds?

    The investment in the feeder fund is totally a great deal. But just like any other investment plan, there are certain risks that you should know of. The key ones to know are as follows:

    1. Layered Costs

    The feeder fund has its own expenses, while the underlying fund also incurs expenses. AMFI notes that FoFs can have expenses at both levels, subject to regulatory limits.

    This means you should consider the overall cost rather than looking only at one expense ratio.

    2. Currency Risk

    Overseas feeder funds are affected by currency movements. A stronger rupee can reduce returns when foreign assets are translated back into rupees.

    A weaker rupee can have the opposite effect. Currency movement therefore adds another variable to your returns. AMFI also identifies exchange-rate movements as a risk for international funds.

    3. Underlying Fund Risk

    Poor performance, concentration or changes in the master fund can affect the feeder fund directly. You are relying on another fund for most investment decisions.

    Therefore, checking only the feeder fund’s past returns may not be enough.

    4. Investment Restrictions

    International mutual fund schemes can have some restrictions at time. This will include the mode of investment and also the plan. So, you should check the limitations as well before starting.

    There can be some charges or limitations as well that should be taken into consideration as well. 

    How Are Feeder Funds Taxed in India?

    Taxation depends on the feeder fund’s underlying assets. An international equity feeder fund will have different taxation that yous should know. 

    From FY 2025-26, Section 50AA mainly covers mutual funds investing more than 65% in debt and money-market instruments. It also covers funds investing at least 65% in such debt-oriented funds.

    For a typical unlisted international equity feeder or FoF outside Section 50AA, units held beyond 24 months generally become long-term capital assets. LTCG is taxed at 12.5% without indexation. Gains on units held for 24 months or less are generally taxed at the applicable slab rate.

    Feeder/FoF TypeHolding PeriodGeneral Tax Treatment
    International equity feeder/FoFUp to 24 monthsSTCG at applicable slab rate
    International equity feeder/FoFMore than 24 monthsLTCG at 12.5% without indexation
    Debt-oriented feeder/FoF covered by Section 50AA, bought on/after 1 April 2023Any periodDeemed STCG, taxed at applicable slab rate
    Qualifying domestic equity-oriented FoFAs per equity fund rulesEquity taxation may apply if conditions are met

    Ensure that you check the taxation policy well before you actually start.

    What Should You Check Before Investing in a Feeder Fund?

    Do not choose a feeder fund only because the underlying market has recently performed well. The master fund deserves the same attention as the feeder scheme.

    So, if you are an investor planning to invest the same, the key checkpoints to know are as follows:

    • Start by checking the investment strategy first.
    • Check the investment options you have.
    • Ensure to analyse the past performance and also the returns.
    • See if there are different sectors and segments that you can check.
    • Check the expense ratio before you select one.
    • Understand how currency movements can affect your returns.
    • Review the tax treatment applicable to the fund.
    • Look for the options like SIPs and lumpsum.
    • See if there is any entry or exit load.
    • Know the lockin period, if any.
    • Understand the overall risk level of the fund.
    • Check if your goals, time, and expectations match with the fund.

    Read Also: What Is IDCW in Mutual Funds and How Does It Work?

    Conclusion

    The feeder funds are great when you wish to invest in the broader market. But when you plan to invest in one of these, you would need to check all the details well. From the nature of the investment to the policy and taxes, everything needs to be considered to ensure you make the right call.

    For further details and support, you can open an account with Pocketful. This will help you to stay updated with the changes and also the latest information to ensure that the investment grows. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What Are Feeder Funds?

      Feeder funds collect money from investors and invest mainly in another fund called the master fund. The master fund manages the underlying portfolio.

    2. Is a Feeder Fund a Mutual Fund?

      It can be. In India, many feeder schemes are structured as Fund of Funds mutual fund schemes investing in an underlying domestic or overseas fund.

    3. Are Feeder Funds Risky?

      Yes. They carry market risk and the risks of the underlying master fund. International feeder funds also carry currency and country-specific risks.

    4. Is a Feeder Fund the Same as a Fund of Funds?

      Not exactly. A feeder fund generally channels most assets into a specific master fund, while a FoF may invest across multiple funds.

    5. Can Feeder Funds Invest in Foreign Markets?

      Yes. International feeder funds are commonly used to give investors exposure to overseas markets through an Indian mutual fund structure.

  • Floater Debt Funds: Benefits, Risks & Taxation in India

    Floater Debt Funds: Benefits, Risks & Taxation in India

    When interest rates change, it can impact your investments. In such a scenario, it is important to understand ‘floater debt funds.’ These are mutual funds that primarily invest in debt instruments whose interest rates fluctuate over time. But how do these funds work, what is the level of risk involved, and how are they taxed? Let’s explore this in simple terms.

    What Is a Floater Fund? 

    A Floater Fund is a type of debt mutual fund that primarily invests in bonds and debt securities with interest rates that change periodically. According to SEBI regulations, funds in this category must invest at least 65% of their total assets in floating-rate instruments. This can also include fixed-rate instruments for which the interest rate risk has been converted into a floating rate through the use of swaps or derivatives.

    For Example, consider a floating-rate bond with an interest rate linked to the RBI’s repo rate or another benchmark. When the benchmark changes, the bond’s interest rate may be reset in accordance with its pre-defined terms. By investing in such bonds, a Floater Fund gains exposure to floating rates. However, the fund’s returns are not fixed, and there remains a risk of loss.

    How Do Floater Debt Funds Work? 

    To understand a floater debt fund, it is essential to know where the money is invested and how changes in interest rates affect the investment. This can be understood through a few simple steps:

    Step 1: The Fund Invests in Floating-Rate Instruments

    First, the fund manager invests the money collected from investors into floating-rate bonds and other eligible debt instruments. According to SEBI regulations, at least 65% of a floater fund’s total assets must be invested in floating-rate instruments.

    Step 2: The Interest Rate Is Linked to a Benchmark

    The interest rates for many of these instruments are linked to a benchmark rate plus a fixed spread. As the benchmark changes, the interest rate may also adjust, in accordance with the terms of the specific instrument. Note that each bond may have a different benchmark and a unique reset schedule.

    Step 3: The Interest Rate Resets Periodically

    For example, suppose a bond’s interest rate is set at 1.5% above a benchmark rate. If the benchmark is 6%, the interest rate would be 7.5%. If, by the next reset date, the benchmark rises to 6.5%, the interest rate could increase to 8%. This is merely an illustrative example; the actual rate depends on the specific terms of the bond.

    Step 4: The Fund’s Income May Change

    When the interest rate on a bond rises, the interest income generated from it may also increase. Conversely, if the interest rate falls, the income may decrease. This impact is not necessarily immediate for the fund, as different securities may have different reset dates.

    Step 5: The Fund’s NAV Changes With Market Conditions

    A fund’s returns are not determined solely by interest income. Changes in bond prices, the credit quality of the issuers, overall market conditions, and the fund’s expenses all influence its Net Asset Value (NAV). Therefore, even when interest rates rise, it is not guaranteed that the returns on a floater fund will increase; there remains a possibility of incurring losses.

    SEBI Rules for Floater Funds in India 

    1. Minimum Investment Requirement

    According to SEBI’s mutual fund scheme classification framework, a Floating Interest Rate Fund must invest at least 65% of its total assets in floating-rate instruments. This may also include fixed-rate instruments for which the interest rate risk has been converted into floating-rate exposure through the use of swaps or derivatives.

    2. Investment Through Swaps and Derivatives

    SEBI’s framework permits funds to gain floating-rate exposure via fixed-rate instruments, provided that specific conditions are met. The objective is to maintain floating-rate exposure within the portfolio. It is mandatory to comply with the applicable derivative and risk-management requirements for such investments.

    3. Applicable Regulatory Framework

    SEBI issued a new circular regarding the classification and categorization of mutual fund schemes on February 26, 2026. Subsequently, a new Master Circular for Mutual Funds was issued on March 20, 2026. Therefore, the current investment allocation and applicable conditions for any fund should be verified against the latest regulations and its Scheme Information Document (SID).

    Read Also: Debt Mutual Funds: Meaning, Types and Features

    Floating Rate Funds India: Latest Market Data 

    To understand the landscape of floater funds in India, looking solely at their returns is not enough. It is also necessary to examine the amount of capital invested in this category and how these funds have performed over various time periods. Data from AMFI for September 2026, along with NAV-based figures available up to October 21, 2026, provide a clear picture of this.

    Latest Data on Floater Funds in India

    Market indicatorLatest available data
    Floater Fund schemes12
    Category AUM (September 2026)₹51,140 crore
    Net investment flow (September 2026)−₹1,710 cr
    Median 1-year return5.2%
    Median 3-year annualised return7.1%
    Median 5-year annualised return6.2%

    Benefits of Investing in Floater Debt Funds 

    Suppose interest rates in the market are rising, and you are considering investing in debt funds. In such a scenario, it can be useful to understand ‘floater debt funds,’ as their interest rate structure differs from that of fixed-rate funds. While they offer certain advantages, these benefits may vary depending on market conditions.

    • Rising Interest Rates May Help: The interest rate on a bond held within a floater fund can increase when its underlying benchmark rises. This has the potential to increase the interest income earned. However, such adjustments depend on the specific ‘reset date’ of the bond.
    • A Different Option for Debt Investors: If you are already invested in fixed-rate debt funds, a floater fund can serve as an alternative option. In a floater fund, interest rates can change over time, whereas fixed-rate bonds typically have a pre-determined coupon rate.
    • Investment Across Multiple Securities: Investing in a floater fund provides exposure to various debt securities through a single scheme. The selection of these securities depends on the fund manager’s strategy and the scheme’s investment mandate.
    • No Need to Select Every Bond Yourself: Evaluating the interest rate, maturity, and financial health of the issuing company for every individual bond can be complex. In a floater fund, the fund manager handles the selection of these securities. This spares the investor from having to choose each bond personally—though it is worth noting that the fund’s performance is contingent upon the manager’s decisions.
    • Can Add Variety to a Debt Portfolio: If your portfolio consists solely of fixed-rate investments, adding a floater fund can alter how your portfolio responds to interest rate movements. This introduces diversification, though it does not necessarily guarantee a reduction in overall risk.
    • Redemption Flexibility: Most floater funds are ‘open-ended.’ This means that, if needed, investors can redeem their units on any business day at the prevailing Net Asset Value (NAV). However, do not assume that the money will be available immediately. The terms of redemption and the timing of payouts depend on the rules of the respective scheme.

    Risks of Floater Funds 

    When considering an investment in a floater fund, looking only at the potential benefits is not enough. It is possible to incur losses in such funds, even when interest rate environments shift. To understand why, it is essential to examine the risks that could impact your investment:

    • Credit Risk: If any of the companies whose bonds are held by a floater fund fail to make timely interest or principal payments, the fund may suffer a loss. In such a scenario, the fund’s Net Asset Value (NAV) could decline. Therefore, it is crucial to review the fund’s holdings and their respective credit ratings before investing.
    • Interest Rate Risk: While the interest rate on a floating-rate bond can change, its market price does not always remain stable. Changes in interest rates, the specific terms of the bonds, and broader market conditions can cause bond prices to fall, which in turn can affect the fund’s NAV.
    • Liquidity Risk: Certain bonds may be difficult to sell when the need arises. If there are few buyers in the market, the fund might have to accept a lower price to complete a sale. In such situations, the availability of funds for investor redemptions could also be impacted.
    • Lower Income When Interest Rates Fall: If the benchmark rate linked to a bond declines, its interest rate may also decrease at the next reset date. This can lead to a reduction in the fund’s interest income. Consequently, before investing in a floater fund, it is important to understand that fluctuating interest rates can have an impact in either direction.
    • No Fixed Return or Capital Guarantee: Investments in floater funds do not offer a predetermined rate of interest or profit. If the prices of the bonds within the portfolio fall, or if the financial health of an issuer deteriorates, the value of your investment could decline. Therefore, such funds should not be viewed as options that provide guaranteed returns.

    Floater Debt Funds vs Fixed-Rate Debt Funds 

    The primary difference between floater funds and fixed-rate debt funds lies in how the interest rates of the bonds they hold are determined. This distinction dictates how the performance of each type of fund might be affected when interest rates change.

    Comparison factorFloater Debt FundsFixed-Rate Debt Funds
    Interest rateThe interest rate may be reset from time to time.The interest rate on a bond is usually predetermined.
    Rising interest ratesInterest income may increase after the reset.The market price of existing bonds could come under pressure.
    Falling interest ratesInterest income may decrease after the reset.The price of old bonds may rise.
    Interest rate riskIt may generally decrease, but it does not disappear completely.It could be higher, especially in the case of long-term bonds.
    Income predictabilityInterest income may vary.The coupon on a bond is fixed, but the total return on a fund is not.
    Other risksThere are credit, liquidity, and market risks.There are credit, liquidity, and market risks.
    Suitable considerationInvestors seeking debt investments that adjust in line with changing interest rates.Investors seeking exposure to fixed-coupon bonds.

    How to Choose a Floater Fund in India 

    When picking a floater fund, don’t just go after the one that gave the highest returns last year. What actually matters is the kind of bonds the fund invests in, how much risk comes with them, and how much the fund charges you.

    • Check Which Bonds the Fund Holds: Review the fund’s latest portfolio report. It will reveal whether the capital is invested in government securities, highly-rated corporate bonds, or bonds with higher credit risk. Understanding the quality of the bonds is crucial, as a default by an issuer could lead to a decline in the fund’s Net Asset Value (NAV).
    • Compare Returns Over the Same Period: When comparing two floater funds, examine their 1-year, 3-year, and 5-year returns. Ensure that the comparison is made over the same time frame and for the same type of plan (e.g., Direct Growth). Do not base your decision solely on the previous year’s strong performance, as past returns do not guarantee similar results in the future.
    • Look at the Expense Ratio: The expense ratio represents the annual cost of operating and managing the fund, which is adjusted within the NAV. For similar types of funds, a lower expense ratio can be advantageous for the investor, provided other factors remain favorable. Note that the expense ratio may differ between Direct and Regular plans.
    • Understand How the Portfolio May React to Interest Rates: Check the fund’s factsheet for metrics such as modified duration, average maturity, and portfolio yield. These indicators help in understanding the fund’s exposure to interest rate risk and the composition of its portfolio. Even with floating-rate exposure, the fund’s NAV may still experience fluctuations.
    • Read the Scheme Documents Before Investing: Take time to go through the fund’s Scheme Information Document (SID). It lays out the fund’s goals, where your money gets invested, the risks involved, and all the key terms. Reading this helps you see if the fund really fits your personal goals.

    Taxation of Floater Debt Funds in India 

    The tax payable on gains from a Floater Debt Fund depends on the date you purchased your units and the tax category of the fund. Therefore, it is essential to consider both these factors before redemption.

    1. Units Purchased on or After 1 April 2023

    If your fund qualifies as a “specified mutual fund,” any profits from units bought on or after April 1, 2023, count as short-term capital gains, no matter how long you hold them. These profits will be taxed based on your regular income tax slab rate. The rules for the 2026–27 tax year fall under Section 76 of the Income-tax Act, 2025.

    2. Units Purchased Before 1 April 2023

    Standard capital gains rules may apply to units purchased before this date. For eligible units sold on or after 23 July 2024, the tax is calculated based on the holding period.

    Holding periodGeneral tax regime
    24 months or lessShort-term capital gains; as per the applicable slab rate
    More than 24 monthsLong-term capital gains: Generally 12.5% ​​(without indexation) on transfers made on or after 23 July 2024.

    3. Tax on IDCW Payouts

    If you opt for the IDCW (Income Distribution cum Capital Withdrawal) option in a Floater Fund, the amount received is generally added to your taxable income and taxed according to your applicable tax slab. In certain cases, TDS (Tax Deducted at Source) may also be deducted.

    Read Also: Why Debt Funds Are Better Than Fixed Deposits of Banks?

    Who Should Consider Floater Debt Funds? 

    Before jumping in, think about your personal goals. While these funds work well for some, they aren’t right for everyone. They are especially great for investors expecting interest rates to rise.

    • Investors Expecting Interest Rates to Rise: If you anticipate that interest rates may rise, you might consider this fund. As rates increase, the interest income from some of the bonds held by the fund may also rise.
    • Investors With Existing Debt Investments: If you already hold fixed-rate debt funds, adding a Floater Fund can provide a different type of interest-rate exposure to your investment portfolio.
    • Investors Who Can Handle NAV Fluctuations: If you can tolerate fluctuations in the value of your investment, you may consider including this fund among your options. Please note that there is a possibility of incurring losses.
    • Investors Who Understand Credit Risk: Investors who examine the fund’s holdings and the credit quality of the underlying bonds are better positioned to make an informed decision.
    • Investors Who Do Not Require Fixed Returns: Returns in this fund are not predetermined. Therefore, before investing, consider when you might need your money and whether you are prepared to take on market-related risks.

    Conclusion

    When investing in floater debt funds, looking only at interest rates is not enough. You should also examine the bonds in which the fund has invested, the credit quality of those bonds, and the level of risk involved. Only then will you be able to determine whether the fund is suitable for your investment objectives.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What Is a Floater Debt Fund?

      It is a debt mutual fund that primarily invests in floating-rate instruments.

    2. How Do Floater Funds Work?

      The interest rates of the floating-rate instruments held within these funds can change periodically, based on specific terms and conditions.

    3. Are Floater Funds Risk-Free?

      No, they carry risks related to credit, liquidity, and the market.

    4. Can Floater Funds Benefit From Rising Interest Rates?

      Yes, when interest rates rise, the interest income from some of the bonds they hold may increase; however, returns are not guaranteed.

    5. How Are Floater Funds Taxed in India?

      Taxation depends on the category of the fund, the date of unit purchase, and the applicable income tax regulations.

  • What Is IDCW in Mutual Funds and How Does It Work?

    What Is IDCW in Mutual Funds and How Does It Work?

    IDCW in mutual funds stands for Income Distribution cum Capital Withdrawal. It is an option in which a mutual fund may distribute part of its available surplus to investors rather than keep the entire amount invested.

    But this is not an additional return on your investment. So, what is this exactly? Well, read this guide to understand the details here.

    What Is IDCW in Mutual Funds?

    Income Distribution cum Capital Withdrawal (IDCW) is an option that allows the fund house to distribute a part of the scheme’s distributable surplus among eligible investors.

    The money can come from income and realised gains generated by the scheme. Regulations also recognise that an IDCW distribution can include amounts from the investor’s capital through the equalisation reserve.

    In simpler words, it is a distribution from the value already available within the mutual fund scheme.

    IDCW was earlier known as the dividend option. SEBI changed the terminology to Income Distribution cum Capital Withdrawal from April 2021 for clarity. 

    How Does IDCW Work in Mutual Funds?

    When you invest in an IDCW option, you hold units of the mutual fund just like any other investor. The difference appears when the fund declares a distribution.

    Here is how the process generally works.

    1. You Invest in the IDCW Option

    You first select the IDCW option while investing in a mutual fund scheme that provides this facility.

    IDCW is available separately from the growth option. Some schemes may also provide different frequencies or sub-options depending on their structure.

    2. The Scheme Generates Income and Gains

    The mutual fund invests the collected money according to its investment objective. Depending on the type of fund, it may earn interest, dividends or gains from selling securities.

    A portion of the amount available for distribution may then form the scheme’s distributable surplus.

    3. The Fund Declares IDCW

    The AMC or trustees may declare IDCW when sufficient distributable surplus is available.

    However, declaring IDCW is not compulsory. The amount and frequency are also not guaranteed. A scheme offering a monthly or quarterly IDCW option does not mean investors are assured of receiving a payment every month or quarter.

    4. Eligible Investors Receive the Distribution

    Investors whose names appear in the records on the applicable record date become eligible for the declared IDCW.

    Depending on the option selected, the amount may be paid to the investor or reinvested in additional units.

    5. The NAV Adjusts After IDCW

    Once IDCW is distributed, money moves out of the scheme. As a result, the NAV of the IDCW option declines. This is mainly by the amount that you distribute.

    For example, suppose you hold 1,000 units of a mutual fund. Now, lets say these are with an NAV of ₹50.

    The value of your investment is:

    1,000 × ₹50 = ₹50,000

    Now, assume the fund declares IDCW of ₹2 per unit. You become eligible for a distribution of ₹2,000 before applicable tax deductions.

    Ignoring market movement and other adjustments, the NAV may reduce from ₹50 to around ₹48 after the distribution.

    Your investment has not suddenly generated an additional ₹2,000 outside the fund. A part of the value held within the scheme has simply been distributed to you.

    Why Did SEBI Rename Dividend to IDCW in Mutual Funds?

    In April 2021, the Securities and Exchange Board of India (SEBI) renamed the dividend option in mutual funds to Income Distribution cum Capital Withdrawal (IDCW) to make the payout mechanism clearer for investors. 

    The term “dividend” often created the impression that mutual funds offered additional income, similar to dividends paid by companies. 

    However, mutual fund payouts can come from both investment gains and investors’ capital. The new name aims to improve transparency and help investors understand that payouts are not guaranteed and can reduce the fund’s Net Asset Value (NAV).

    What Are the Types of IDCW Options?

    Mutual fund schemes commonly provide IDCW through payout and reinvestment options. You can understand the same as follows:

    1. IDCW Payout

    Under the payout option, the declared amount is paid to your registered bank account after applicable tax deduction.

    For example, say you hold 2,000 units. Now, the scheme declares an IDCW of ₹1 per unit, the gross distribution would be ₹2,000.

    The NAV of the IDCW option reduces after the distribution.

    2. IDCW Reinvestment

    Under the reinvestment option, you do not receive the declared amount in your bank account. Instead, the amount remaining after applicable TDS is used to purchase additional units of the same IDCW option.

    Your number of units therefore, increases, although the NAV adjusts after the IDCW declaration. SEBI scheme documents specifically provide for both payout and reinvestment facilities under IDCW.

    This option may appear similar to the growth option because the money stays invested. However, the mechanism and the taxation differ. IDCW is considered distributed before being reinvested and may therefore have tax consequences.

    Read Also: What is R-Squared in Mutual Funds?

    What Is the Difference Between IDCW and Growth Options?

    Both options invest in the same underlying mutual fund portfolio. The main difference lies in what happens to the income and gains generated within the scheme.

    ParticularsIDCW OptionGrowth Option
    DistributionMay distribute money when IDCW is declaredNo IDCW distribution
    NAVFalls when IDCW is distributedReturns remain reflected in NAV
    CompoundingDistributions reduce the amount remaining investedReturns remain invested and can compound
    Cash flowCan provide payouts when declaredMoney is generally accessed by redeeming units
    Tax timingIDCW is taxable when distributedCapital gains tax generally arises on redemption
    PredictabilityIDCW amount and frequency are not guaranteedNo periodic distribution is promised
    Suitable forInvestors who require distributions and understand the implicationsInvestors focused mainly on wealth accumulation

    Under the growth option, income attributable to the units remains invested in the scheme and is reflected in its NAV. Under IDCW, some of that value may be distributed instead.

    Suppose two investors each invest ₹1 lakh in separate options of the same scheme. If the IDCW option distributes money regularly, less capital may remain invested under that option.

    The growth investor receives no such distribution. The entire investment remains exposed to subsequent market movements and has a greater opportunity to compound over a long period.

    This does not automatically make one option right for every investor. Your choice should depend on why you are investing and whether you actually need distributions from the investment.

    How Is IDCW Taxed?

    IDCW received from mutual funds is taxable in the hands of the investor. To understand the taxation better, here are the key points that you should know:

    • IDCW is not tax-free.
    • TDS at 10% may apply under Section 194K. This is applicable if IDCW income exceeds ₹10,000 in a financial year.
    • TDS is only a tax deduction, not the final tax liability.
    • Your final tax depends on your total taxable income and applicable slab rate.
    • If excess TDS is deducted, you can claim it later.
    • Tax rules can differ for non-resident investors.

    What Are the Benefits and Limitations of IDCW?

    IDCW can be useful in specific situations. But just like any other investment option, there are certain pros and cons of investing in the same. These are as follows:

    Benefits of IDCW

    • You may receive money without manually redeeming mutual fund units.
    • It can provide occasional cash flow when the scheme declares IDCW.
    • The payout can be used for expenses or other financial requirements.
    • Investors can also choose reinvestment where the scheme provides the option.

    Limitations of IDCW

    • The amount of IDCW is not guaranteed.
    • The frequency of distributions is also not assured.
    • NAV reduces after the distribution.
    • IDCW is taxable in the hands of the investor.
    • Frequent distributions can leave less money invested for long-term compounding.
    • A high IDCW payout does not necessarily mean that a fund has delivered a high overall return.

    All these are some of the key points that you should consider when you are willing to invest. 

    Who Should Consider the IDCW Option?

    IDCW may suit investors who:

    • Prefer occasional payouts from their mutual fund investment.
    • Understand that IDCW payments are not fixed or guaranteed.
    • Do not want to redeem units manually each time they need money.
    • Are comfortable with the tax impact of IDCW.
    • Are not relying only on long-term compounding.

    If you need a more predictable withdrawal amount, you can also compare IDCW with a Systematic Withdrawal Plan. This can help you build a strong portfolio that will generate good returns.

    Read Also: What is Stamp Duty on Mutual Fund Investments?

    Conclusion

    IDCW in mutual funds allows a scheme to distribute part of its available surplus to investors. This is not an additional return but is again a benefit that you get. But before investing, it is important that you compare all the options in front of you to make the right call and avoid investing in funds that do not meet your expectations.

    This is where a platform like Pocketful can help you with the insights. Get all the details and support you need to start investing and build your portfolio better.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Mutual Funds vs Segregated Funds: Key Differences
    2Survivorship Bias and Mutual Fund Performance
    3What is Flow of Funds (FOF)?
    4How to Start Systematic Investment Plan (SIP) in Index Funds?
    5Indexation in Mutual Funds: Meaning, Calculation & Importance

    Frequently Asked Questions (FAQs)

    1. What Is the Full Form of IDCW?

      IDCW stands for Income Distribution cum Capital Withdrawal. It is the term used for the option earlier known as the dividend option in mutual funds.

    2. Is IDCW Paid Every Month?

      Not necessarily. Some schemes may offer monthly IDCW options, but the actual distribution depends on the availability of distributable surplus and the fund’s decision. A monthly option does not guarantee monthly income.

    3. Does NAV Fall After IDCW?

      Yes. When IDCW is distributed, the NAV of the relevant option generally falls by the amount distributed per unit, subject to applicable adjustments and market movement.

    4. Is IDCW Tax-Free?

      No. IDCW is taxable in the hands of the investor. For an individual investor, it is generally added to taxable income and taxed at the applicable income tax slab rate.

    5. Which Is Better, IDCW or Growth?

      There is no single option suitable for everyone. Growth may be more suitable for investors focused on long-term compounding, while IDCW may be considered by investors who prefer distributions and understand the associated tax and NAV impact.

  • What Is Flow of Funds (FOF)? Meaning, Example & Importance

    What Is Flow of Funds (FOF)? Meaning, Example & Importance

    Ask most people where their money goes after they pay a SIP instalment or park cash in a fixed deposit, and you’ll get a blank look. The money does not vanish, of course. A bank lends it to a business, an insurer puts it into government bonds, a mutual fund buys shares. Economists track this entire movement through something called the flow of funds. 

    In India, the Reserve Bank of India compiles these accounts every year, and they show who is saving, who is borrowing, and which financial products connect the two. 

    In today’s blog, we will find out what is the flow of funds, how it actually works, and why you should understand the concept.

    What is Flow of Funds (FOF)?

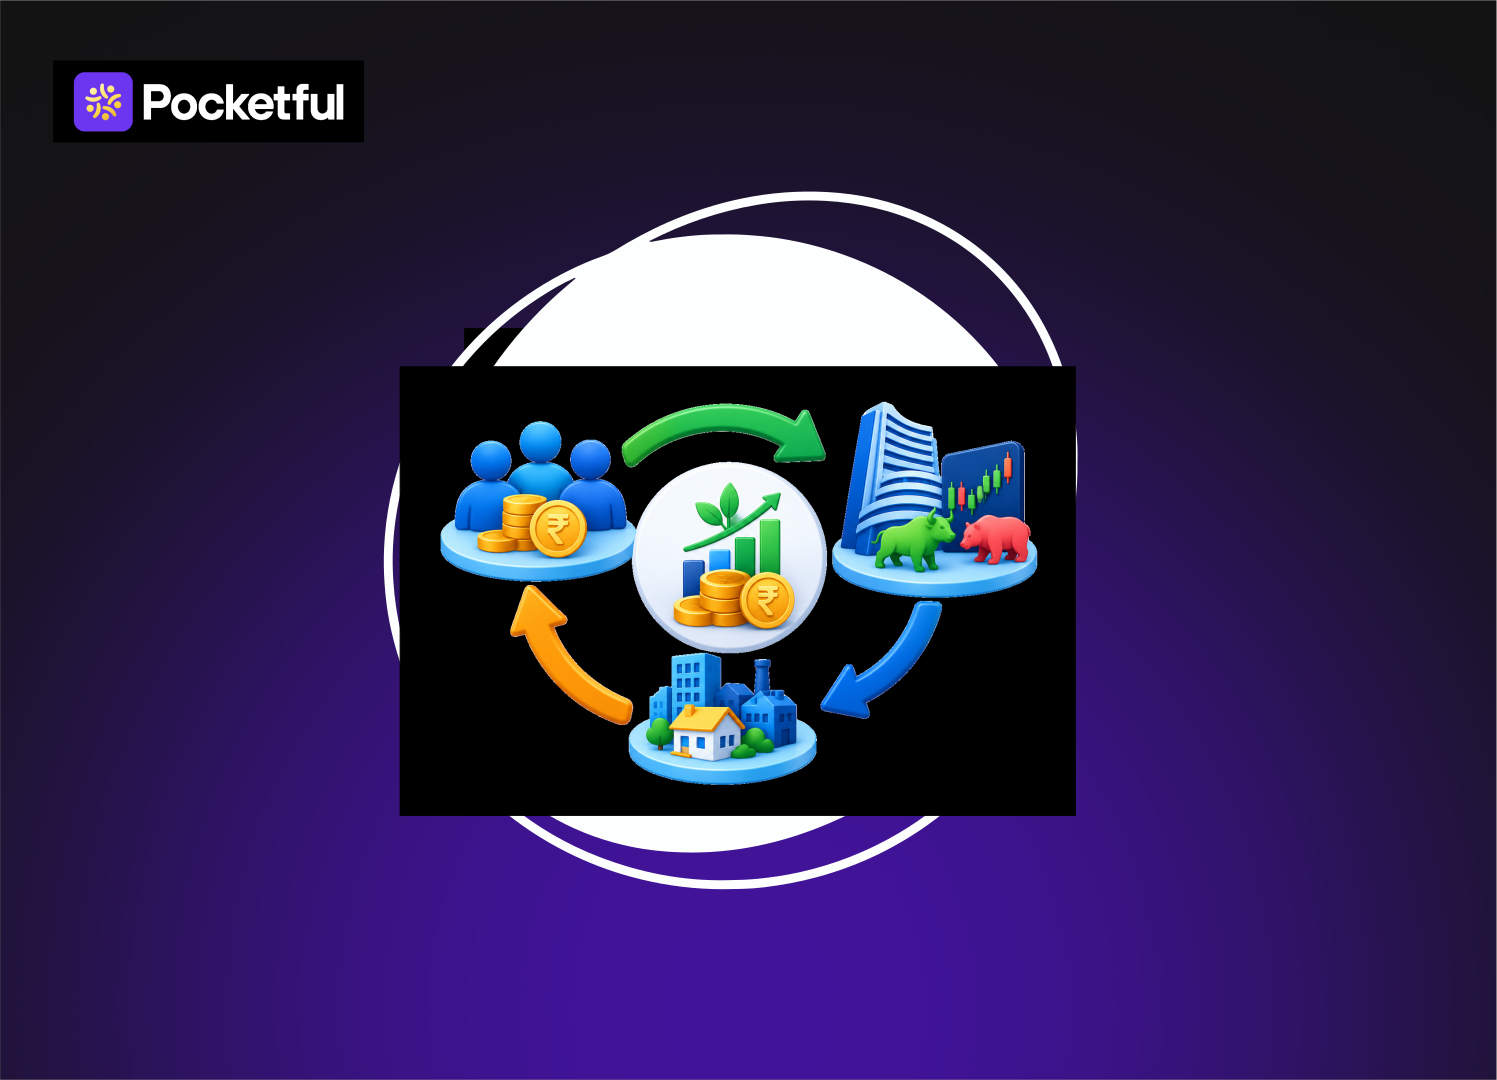
    Flow of funds is a series of accounts that provide information about financial transactions among the various sectors of an economy over a period of time, typically a financial year. It provides answers to a fundamental question: how much money did each sector raise, and what did they do with it?

    Not all individual and company accounts are included. They group them. In the Indian context, you will find households, non-financial companies, financial companies (banks, insurers, mutual funds and NBFCs), the government (Centre and states combined) and the rest of the world.

    Some of these sectors have surplus money, which means that they make more money than they spend. Some spend more than they make and are in debt. The accounts record both of them, and they also record the instruments in between, such as deposits, loans, bonds, shares, insurance policies, and provident funds. 

    How Does Flow of Funds Work?

    Every sector earns income, spends part of it, and saves what remains. That saving can go towards real assets, such as a house, a machine, or a factory, or it can be lent out as a financial asset.

    1. The Net Lender/The Net Borrower

    If a sector saves more than it invests in real assets, it ends up as a net lender. If it needs more than it saves, it becomes a net borrower. Indian households have long been the biggest net lenders since they save more. Their money lies in bank deposits, LIC policies, EPF and PPF accounts, post office schemes, mutual funds, etc. Companies and the government are on the other side. They usually need more funds than they generate, for expansion in one case and for public spending in the other.

    2. The Intermediaries

    Then come the intermediaries. A bank accepts deposits from lakhs of households and turns them into loans for businesses, home buyers and, indirectly, the government through bond purchases. A mutual fund gathers small investments and spreads them across equity and debt. Insurers invest premiums, much of it in government securities. None of these institutions produces much of their own money. Their job is to move it from people who have it to people who can use it.

    3. The Foreign Sector

    When the economy borrows more than it saves, the difference comes from overseas through foreign direct investment, portfolio flows, or external commercial borrowings. That’s why the rest of the world has its own column in the accounts.

    One rule holds everything together. A financial asset for one party is always a liability for another. Your fixed deposit is your asset and the bank’s liability. A government bond held by an insurer is the insurer’s asset and the government’s liability. Because of this, if you add up the net lending and borrowing of every sector, including the foreign one, the answer is zero.

    What is a Flow of Funds Matrix

    It is a comprehensive macroeconomic accounting grid that tracks the movement of financial resources and credit across sectors of an economy. 

    It acts like a nationwide spreadsheet where everyone’s spending and income connect and balance out. 

    Columns represent economic sectors that include 

    • Households (including NPOs)
    • Non-financial companies (Commercial businesses)
    • Financial Institutions (banks, AMCs, insurance companies) 
    • Central & State Government 
    • Rest of the World

    Rows represent Financial Instruments and Transactions (tools through which money moves): 

    Currency and bank deposits are the simplest. Loans, government securities, corporate bonds, equity shares, mutual fund units, life insurance funds, and small savings follow. Each one shows up as a separate line in the matrix.

    Sources & Uses of Funds:

    Furthermore, each sector’s column is subdivided into Sources of Funds and Uses of Funds.  Sources are what a sector raises, through borrowing, issuing shares or accepting deposits. Uses are where the money goes: lending, buying securities, holding deposits and so on.

    At last comes the net financial position, which is the gap between uses and sources. It tells you in one number whether a sector is feeding money into the system or drawing it out.

    Read Also: What is Fund of Funds (FOF)?

    Example of Flow of Funds (FOF)

    Below is an easy tabular illustration for better understanding 

    SectorFunds raised (sources)Funds invested or lent (uses)Net position
    Households10110100
    Non-financial corporations12060-60
    General government5010-40
    Financial corporations2002000

    Take households first, since their numbers are the easiest to follow. 

    Over the year, they put ₹110 crore into bank deposits, insurance premiums, EPF and PPF, mutual funds and shares. However, they borrowed only ₹10 crore through home and personal loans. 

    Subtract one from the other, and you get a surplus of ₹100 crore. In simple terms, households had that much more to lend than they needed for themselves.

    Let us come to companies now. They raised ₹120 crore through bank loans, bonds and fresh equity, but they did not spend all of it. ₹60 crore stayed in financial form, in deposits or invested elsewhere. The difference is ₹60 crore, which is their net borrowing. 

    The government is in a similar position, though its numbers are smaller. It raised ₹50 crore through market borrowings and small savings schemes and held back ₹10 crore in financial assets. That leaves it ₹40 crore short.

    Banks, insurers and mutual funds lie in between all of this. They collected ₹200 crore from deposits, premiums and fund units, and they gave away the same ₹200 crore as loans and securities. Nothing was left, so their net position is zero. 

    Now put the net figures side by side. Households are ahead by ₹100 crore, while companies and the government are behind by ₹60 crore and ₹40 crore, which adds up to the same ₹100 crore. The two sides cancel out exactly, as they always must. 

    In a real RBI table, you would also see the foreign sector, and the balancing would depend on overseas capital coming in or going out. 

    Importance of Flow of Funds

    • Helps in understanding the economic activity: It helps to find how funds move between different sectors of the economy, and helps analysts understand how savings are used for investments and how borrowing supports economic activities.
    • Tracks Savings & Investments: FOF helps in explaining how savings from households and other sectors are moved into financial assets, business investments, and lending, which gives a clear picture of how available financial resources are allocated across the economy. 
    • Helios Financial Planning: Businesses can use fund flow analysis to understand their sources of funds and how they are being used, and this helps them plan future expenses, manage financial resources, and identify funding needs. 

    Conclusion 

    Flow of funds provides clear, structured insight into the movement of money in India. It demonstrates who is saving, who is borrowing, which products link them up, and the matrix provides a view of all of this in one place. The key rule, one’s asset is always another’s liability, ensures consistency in the entire system.

    If you are handling any kind of money, from being a student to an analyst to an investor, it’s worth spending some time with these accounts. 

    They describe the importance of saving in a household, the role of the banks and mutual funds in channelling the savings, and the role of government borrowing and foreign inflows. Understanding the framework makes RBI publications easier to read, and your savings and investments appear to be a small but real part of a very big picture.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4How to Start SIP Using E-Mandate?
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What is Flow of Funds?

      It tracks the flow of funds among the various sectors in an economy, including the households, the business sector, the banking sector, and the government sector. 

    2. What is the main purpose of the flow of funds?

      The primary objective is to get an understanding of where the funds are being spent, how they are being spent, and how they flow through each sector. 

    3. What are the major elements of FOF?

      The major elements are sources of funds, uses of funds, and financial transactions among sectors.

    4. Explain the difference between Flow of Funds and Cash Flow.

      While flow of funds measures the movement of financial resources and financial transactions, cash flow measures the movement of cash and cash equivalents.

    5. Who uses the Flow of Funds analysis? 

      Economists, financial analysts, businesses, government authorities, and investors use FOF to understand financial trends.

  • Survivorship Bias and Mutual Fund Performance 

    Survivorship Bias and Mutual Fund Performance 

    At the time of investing in a mutual fund, an investor commonly looks at the past performance of funds and, based on this, compares it with other funds. But have you ever wondered what will happen to the funds that had performed poorly and disappeared from the market?

    In today’s blog post, we will give you an overview of survivorship bias and how it can impact mutual fund returns.

    What is the meaning of Survivorship Bias?

    Survivorship bias is an error in an analysis that focuses on investments, funds or companies that have survived until the end of a particular period and ignores those that failed or were discontinued. Simply put, this bias considers only the winners that are still around and forgets the ones that did not survive. The returns of the funds that disappeared are left out of the analysis.

    What is Survivorship Bias in Mutual Funds?

    When it comes to mutual funds, survivorship bias generally happens when investors evaluate historical fund performance by considering only schemes that are currently available for investment. It happens when an investor looks at the current list of equity mutual funds and identifies the funds with the best five-year returns. These funds may appear to have performed consistently well over the entire period. However, this analysis does not include the funds that existed five years ago but were later merged or closed after poor performance. Due to this, the investor may get the impression that the long-term mutual fund performance was better and more consistent than it actually was.

    Example of Survivorship Bias 

    Let’s understand survivorship bias through an example.

    There were 10 mutual funds available in an equity category during the year 2015. An investor named Mr X decided to analyse the performance of this category over the last 10 years. After 10 years, only 7 funds are still available. The remaining three funds were merged with other schemes or discontinued because of reasons such as low performance and less interest from investors. Now the 10-year returns of the remaining 7 funds are as follows.

    Fund Name10-Year Returns
    A15%
    B14%
    C13%
    D12%
    E11%
    F10%
    G9%

    In this case, the average return of these funds is 12%. Based on this data, the category appears to have delivered an approximate return of 12%. However, the 3 funds that were closed or merged are not included in this calculation. 

    Now let us include the three closed funds. Suppose their annualised returns until the date of closure were as follows:

    Fund NameReturn Until Closure
    H4%
    I2%
    J-3%

    The average return of all 10 funds is 8.7%. So the true category return was about 8.7%, not 12%. Survivorship bias overstated the category return by roughly 3.3%.

    How Does Survivorship Bias Affect Mutual Fund Performance

    Survivorship bias affects mutual fund performance in the following manner:

    1. Overstating the Average Return: If the investor ignores funds that have been discontinued or merged with some other scheme while calculating the average return, this may cause overstating the average return.
    2. Consistent Performer: A fund that has a consistent performance record and has survived for many years may ignore the funds that have performed poorly and disappeared during the same period.
    3. Easy Fund Selection: When an investor looks only at today’s top performer with the benefit of hindsight, it seems that picking these funds years ago was easy. The funds that looked equally promising but failed are not visible. 

    Why Do Mutual Funds Disappear?

    The common reasons why mutual funds disappear are as follows:

    1. Underperformance: If a fund consistently performs poorly or fails to deliver consistent returns, the AMC may decide to discontinue or merge the scheme.
    2. AUM: When a mutual fund scheme has very low assets under management, it may not be practical for the AMC to continue such funds because of operational and administrative costs.
    3. Change in Investment Strategy: There may be some cases when the scheme investment objective or strategy changes. Instead of continuing the existing fund, it may merge or restructure.
    4. Lack of Interest: If the investors show very little interest in a particular category or scheme. It may decide that continuing is not worthwhile.
    5. Regulations: If the regulatory authority changes the rules related to mutual fund categorisation, the asset management companies are required to close or merge the scheme.

    Read Also: How to Evaluate Mutual Fund Performance in India

    Importance of Survivorship Bias

    The key importance of survivorship bias is as follows:

    1. Real Picture: Analysing both surviving and discontinued funds provides a better idea of how a category has performed over time. It reduces the risk of judging the entire category only by its successful funds.
    2. Avoid Misleading Conclusions: If the poorly performing funds are removed from the data, then the average return may look higher than it really was.
    3. Understanding Investment Risk: A fund category may be less risky only when the successful funds are considered. Funds that have performed poorly may provide a better understanding of possible ups and downs.
    4. Comparing Categories: Survivorship bias can impact the comparison between different categories of mutual funds. It helps investors make fairer comparisons by relying on the performance of funds that are still available. 

    What Is the Difference Between Survivorship Bias and Other Investment Biases? 

    Survivorship bias ignores failures, while other investment biases stem from emotions, assumptions, and market trends. 

    Investment BiasMeaningExample
    Survivorship BiasFocusing solely on the successful investments and ignoring the failed ones and the ones that have been discontinued. Evaluating mutual fund performance by looking at only those funds that are still in existence. 
    Confirmation BiasFavours information which supports existing investment views.Read only the positive news before you invest in a stock. 
    Herd Mentality BiasFollowing other investors’ decisions without independent research.Buying a stock because it is trending among investors.
    Recency BiasGiving excessive weight to recent market performance when attempting to predict future returns. Investing in a fund simply because it delivered such good returns last year. 
    Overconfidence BiasOverestimating one’s ability to predict market movements or select winning investments.Taking excessive risks after a few successful trades.

    Impact of Survivorship Bias

    The key impacts of survivorship bias on the performance of mutual funds are as follows:

    1. Overestimation of Past Returns: Funds that have succeeded are the only ones included in a study, so the average return could be higher than reality.
    2. False Performance: An investor could be misled into thinking that most of the mutual fund is doing well because only surviving funds are visible. 
    1. Understanding Risk: Funds that are not doing well are supposed to disappear from the data set, thus making the overall category less dangerous compared to reality.
    2. Impact Mutual Fund Research: Mutual fund analysis could be concluded erroneously as to how well a category did. 

    Avoiding Survivorship Bias

    The common ways to avoid survivorship bias are as follows:

    1. Include Closed Funds: At the time of analysing the performance of a mutual fund category, one must consider funds that were closed, merged or discontinued instead of considering only funds that are currently available.
    2. Compare Same Duration: One should consider the fund performance only for the same period to prevent newer or recent funds from getting an unfair advantage.
    3. Risk-Adjusted Returns: An investor should not only focus on return; other factors such as Sharpe ratio, maximum drawdown, etc., should be considered while analysing historical data.

    Read Also: How to Build a Mutual Fund Portfolio

    Conclusion

    On a concluding note, survivorship bias can allow investors to understand a broader picture of mutual fund performance. The closed, merged, or discontinued funds may not be covered when analysing returns of the funds that are still active today for various reasons. The past may seem more impressive than it was in reality, and risk can be underestimated. So investors should also take into account the risk, consistency, investment strategy, and the market conditions. After grasping real risk, a broader and unbiased view can assist investors in making informed decisions. But it is recommended that anyone shouldn’t invest based on returns only and should invest only after taking advice from their investment advisor.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Trail Commission in Mutual Funds?
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. What is survivorship bias in a mutual fund?

      It is a bias that occurs when a mutual fund analysis focuses only on funds that are still active and ignores funds that are discontinued or merged. This practice was adopted so that the historical performance of mutual funds looks better than it actually was.

    2. Is it possible for an investor to minimise the impact of survivorship bias?

      Investors can reduce the impact of survivorship bias by using complete historical data that includes funds that were closed or merged, rather than analysing only currently available schemes.

    3. Does survivorship bias affect fund selection?

      If the investor studies funds that have performed well and survived, due to this it is considered that identifying successful funds was easier than it actually was.

    4. What is the difference between survivorship bias and selection bias?

      Survivorship bias in mutual fund selection considers the funds that have survived or remained active, whereas the funds that have discontinued will be removed. However, in the case of selection bias, the data does not represent the entire fund universe.

    5. Does survivorship bias affect historical fund comparison?

      Yes, if only surviving funds are used, comparisons over a long historical period can produce misleading results, because many funds that existed during that period have since closed or merged and are missing from the data. 


  • How to Start Systematic Investment Plan (SIP) in Index Funds?

    How to Start Systematic Investment Plan (SIP) in Index Funds?

    You can start a Systematic Investment Plan (SIP) in index funds by completing the KYC, deciding your SIP amount, finding a fund, and setting up automatic payments. Once registered and approved, your SIP will start. The amount you selected will be debited from your account on the date you selected for every month. 

    The process is simple, but choosing the right index and fund requires some comparison.

    What Is a SIP in Index Funds?

    A SIP in index funds is a method of investing a fixed amount regularly in a mutual fund that tracks a market index. SEBI explains that index mutual funds follow a passive investment strategy. Their objective is to replicate an index rather than actively select stocks to outperform it.

    SIP and index fund are therefore two different concepts:

    ParticularMeaning
    SIPA method of investing money at regular intervals
    Index fundA mutual fund that tracks a particular market index
    Index fund SIPRegular investments made into an index fund

    How Does SIP in Index Funds Work?

    An index fund SIP combines passive investing with regular investing. You choose the fund once and continue investing according to the schedule you have selected. Here are the steps to follow:

    1. You Select an Index Fund

    Select an index fund that matches your goals and needs. These funds track an index that has a different mix. These can be large-cap, mid-cap, small-cap, broad-market, or sector-based indices. Select one that matches your needs well. 

    2. You Decide the SIP Amount

    Next, you select how much you want to invest regularly. The amount of SIP will be based on the same. You can also select multiple schemes and divide the amount between them, or you can go ahead with one scheme at a time.

    Your SIP amount should ideally be based on your financial goal and monthly budget.

    3. Money Is Invested at the Applicable NAV

    Every SIP instalment purchases units according to the applicable Net Asset Value or NAV.

    For example:

    MonthSIP AmountNAVApprox. Units Purchased
    January₹5,000₹10050
    February₹5,000₹8062.5
    March₹5,000₹12540

    This means when the NAV is low, you will get more units. But if the NAV is high, units will be fewer. This is what we call rupee cost averaging. Remember that the risk is still there. 

    4. The Investment Continues Automatically

    After you register an eligible bank mandate, your SIP amount can be debited automatically on the scheduled date. This reduces the need to make a separate investment manually every month.

    How to Start SIP in Index Funds?

    To start SIP in index funds, you first need to decide what you are investing for. You can then compare suitable index funds and register your SIP through an AMC or investment platform. Here is the process.

    1. Define Your Investment Goal

    Start by understanding what your investment goals are, which can be:

    • Retirement planning.
    • Building long-term wealth.
    • Saving for a child’s education.
    • Creating funds for a future financial requirement.

    Your goal also helps determine how long you may need to remain invested. This will be your baseline for fund selection as well.

    2. Choose the Index You Want to Track

    Many people elect a fund because it looks attractive. This is the wrong way of selection and can impact your returns too. 

    For example, large-cap indices generally contain established companies. Mid-cap and small-cap indices can provide exposure to smaller companies but may experience greater price fluctuations.

    Sectoral indices are even more concentrated because they focus on a particular industry or theme. Answer the following questions to start with:

    • What companies are included in the index?
    • How many stocks does it contain?
    • How concentrated is the index?
    • Which sectors have the highest weight?
    • Does this exposure fit your goal and risk tolerance?

    3. Compare Index Funds Tracking the Same Benchmark

    Understand that two funds following the same index can still give different returns. So, you must compare the funds based on:

    • Expense ratio.
    • Tracking differences.
    • Tracking error.
    • Assets under management.
    • Fund history.
    • Exit load, if applicable.

    Expense ratio represents the recurring expenses charged to the scheme.

    Tracking difference shows the difference between the fund’s return and its benchmark return. Tracking error measures the consistency of that difference.

    Since an index fund is designed to replicate its benchmark, both are useful measures when comparing similar funds.

    AMFI also identifies index funds as passive funds whose holdings closely follow their benchmark.

    4. Complete Your KYC

    This is an important stage. KYC verifies details such as your identity and address. SEBI states that KYC is mandatory to start and so you cannot move ahead without this. 

    Depending on the platform and your KYC status, you may need documents or details such as:

    • PAN.
    • Aadhaar or another accepted identity document.
    • Address details.
    • Mobile number and email address.
    • Bank account information.

    You may also need to complete the applicable verification process.

    5. Select the SIP Option

    Once your account is ready, search for the chosen index fund and select the SIP investment option rather than lump-sum investment.

    Enter:

    • SIP amount.
    • SIP frequency.
    • Preferred SIP date.
    • Start date.
    • Investment duration, where applicable.

    Monthly SIPs are common, although available frequencies can vary between schemes.

    6. Register Your Bank Mandate

    Once everything is set, you must focus on the automatic payments. You are starting a SIP which means every month a fixed amount will get debited from your account. This will be on a fixed date as well. This set up is easy and will be done with the bank. 

    7. Confirm and Start the SIP

    Check all the details before confirming the transaction. Review the SIP details, amount, and other details well to move ahead. Once registration is complete, investments can begin according to the selected schedule.

    Read Also: Mutual Fund Tips for Beginners in India

    What Should You Check Before Starting an Index Fund SIP?

    Starting a SIP in an index fund should focus on proper analysis of fund, returns, risk, and the time period. The key things to check are:

    1. Investment Horizon

    Start by checking when you need the funds. This will give you the actual tenure of your investment. It can be for some months or even for years as you may feel appropriate. 

    2. Risk Level

    Index funds are sometimes considered simple because they use passive management. Simple does not mean risk-free.

    If the underlying index falls by a significant amount, the fund will generally move in the same direction.

    Different indices also carry different risk levels. A diversified large-cap index and a sector-specific index should not be viewed as identical investments.

    3. Expense Ratio

    Index funds generally have lower management costs. This means their expense ratio is low but you should still compare the same between different funds. A small difference in annual costs can become more noticeable over a long investment period.

    4. Tracking Difference and Tracking Error

    An index fund aims to follow an index, but its returns will not match the benchmark exactly. A minor difference is fine but if the returns have a lot of gap, be mindful before you invest. 

    5. Direct and Regular Plans

    Mutual fund schemes may offer direct and regular plans. You must select a plan based on the needs and should also consider what kind of returns you wish to see.

    6. Do Not Choose Only on Past Returns

    A fund showing the highest recent return is not automatically the most suitable choice. You should also see where it invests and what the sector potential is. This will give you an idea on future returns well. 

    7. Review the SIP Periodically

    Once you start a SIP, you should follow it well. This is where you would be able to see if the fund is actually performing well or not. 

    Review it periodically to check whether:

    • The fund continues to track its benchmark efficiently.
    • Your financial goal remains unchanged.
    • Your SIP amount remains adequate.
    • Your asset allocation still matches your risk profile.
    • You need to increase your SIP as your income changes.

    There is generally little need to react to every daily market movement.

    Conclusion

    Starting a SIP in index funds involves choosing a fund that works well for your needs. The idea is to ensure that the fund matches your needs and there is a proper risk and return ratio as well. But this is only possible when you properly analyse the fund and work to make the right choice.

    But tracking an index fund is not easy. This is where you can seek help of Pocketful. Get all the insights and details you need to start investing well. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1How to Invest in S&P 500 from India
    2Indexation in Mutual Funds: Tax Rules
    3Dynamic Bond Funds: Meaning, Benefits, Risks & Taxation
    4Rupee Cost Averaging in SIP: Meaning, Benefits & Examples
    5What is a Capital Protection Fund?

    Frequently Asked Questions (FAQs)

    1. Can I Start a SIP in an Index Fund?

      Yes. Many index mutual funds offer a SIP facility. You can select the fund, choose the SIP amount and frequency, and register the required payment mandate.

    2. What Is the Minimum Amount Required for an Index Fund SIP?

      The minimum amount depends on the mutual fund scheme. Some schemes permit relatively small SIP investments, so you should check the current minimum before registering.

    3. Is SIP Better Than Lump Sum for Index Funds?

      Neither method is automatically better. SIP spreads investments across different dates, while lump-sum investing puts the available money into the market at once. The appropriate option depends on your cash flow, risk tolerance and investment plan.

    4. Can I Stop an Index Fund SIP Anytime?

      SIPs in open-ended index mutual funds can generally be stopped according to the AMC’s applicable process. Stopping future SIP instalments is different from redeeming units you already hold.

    5. Are Index Fund SIPs Risk-Free?

      No. Index funds follow market-linked benchmarks, so their value can rise or fall. SIP can spread investments across different market levels, but it does not eliminate investment risk.

  • Mutual Funds vs Segregated Funds: Key Differences

    Mutual Funds vs Segregated Funds: Key Differences

    Mutual funds and segregated funds both help you to invest in market-linked assets. The work is the same, but their bases are different. A mutual fund is mainly designed for investment. A segregated fund combines investment with certain insurance benefits.

    For Indian investors, there is one more point to understand. Segregated funds are mainly seen in countries such as Canada. So, knowing this is important. For investors, this guide shares the brief details on both.

    What Are Mutual Funds?

    A mutual fund pools money from different investors and invests it in shares, bonds, or other securities. This is managed by experts known as fund managers.

    You get units based on the amount you invest and the fund’s NAV. The same keeps on changing based on the market value of the fund.

    Mutual funds can invest in different places based on the type of fund. These can be:

    The risk also varies in each case. For instance, equity funds are considered to have the highest risk-return ratio. But if you go for a liquid or debt fund, the risk is low and so is the return. Therefore, the choice needs to be made with great care.

    What Are Segregated Funds?

    A segregated fund is also used for investment, but it comes through an insurance company. This is the main difference.

    The money is still invested in market-linked assets such as stocks and bonds. The investment is more like insurance contract and so there will be added benefits.

    These can include:

    • A maturity guarantee.
    • A death benefit guarantee.
    • Beneficiary benefits.
    • Certain creditor protection, depending on the rules.
    • Estate-related benefits.

    Now, this does not mean the investment cannot fall.

    Suppose the market performs badly. The value of the segregated fund can also go down.

    The guarantee generally applies only under the conditions mentioned in the contract.

    For example, a fund may guarantee a certain percentage of your eligible investment at maturity. But if you withdraw early, the same benefit may not apply.

    So, the guarantee needs to be understood properly before you consider the product.

    Segregated funds are commonly seen in countries such as Canada. They are not a common investment product in India.

    Are Segregated Funds and Segregated Portfolios the Same?

    No. This is where confusion can happen. In India, we also use the term segregated portfolio in mutual funds. But this is a completely different concept. 

    A segregated portfolio is created when a particular debt or money-market security in a mutual fund faces a credit event.

    Let us say a debt fund has invested in bonds issued by a company. Now the company faces a major credit issue and the value of those bonds becomes difficult to determine.

    In such a case, the affected security may be separated from the main portfolio as per applicable rules. This helps keep the affected investment separate from the rest of the fund.

    So, understand the difference clearly:

    ParticularMeaning
    Mutual fundA pooled investment product
    Segregated fundAn investment product linked with insurance
    Segregated portfolioA separate portfolio created within a mutual fund in certain credit events

    What Is the Difference Between Mutual Funds and Segregated Funds?

    The difference between mutual funds and segregated funds comes mainly from the insurance part.

    A mutual fund focuses on investment. A segregated fund has investment plus certain insurance-based benefits.

    Here is the comparison:

    ParticularMutual FundsSegregated Funds
    Product typeInvestment productInvestment with insurance contract
    Offered byAsset management companiesInsurance companies
    Market-linkedYesYes
    GuaranteeUsually noMay be available
    Death benefitNo insurance-style guaranteeMay be available
    CostGenerally lowerCan be higher
    LiquidityDepends on the fundDepends on the contract
    RiskMarket risk appliesMarket risk still applies
    Common in IndiaYesNo

    1. Investment Structure

    Mutual funds are simple in structure. You invest money in a scheme and the fund manager invests it based on the fund objective.

    Segregated funds work differently because the investment is part of an insurance contract. This is why they can offer benefits that normal mutual funds do not provide.

    2. Guarantee on Investment

    Mutual funds do not usually guarantee your investment amount. If you invest ₹1 lakh and the market falls, your investment could drop to ₹90,000 or even less.

    There is no fixed promise that the original amount will be restored.

    Segregated funds may provide a guarantee on a part of the amount invested but this is still not full protection.

    You need to check:

    • How much is guaranteed?
    • When does the guarantee apply?
    • Is there a fixed maturity period?
    • What happens if you withdraw early?
    • Does the guarantee reduce after withdrawal?

    Without checking these things, the guarantee number alone does not tell you much.

    3. Cost

    There is an expense ratio in mutual funds, which is the charge you pay to get the fund properly managed. Segregated funds can cost more because they also include insurance features.

    While there is a charge in both, the difference in charge is what you need to see. 

    4. Liquidity

    Mutual funds can generally be redeemed when required if they are open-ended. But there may be exit load or other conditions depending on the scheme.

    Segregated funds may have additional conditions because the guarantee may be linked to a specific period. If you withdraw before that, your benefit may reduce.

    So, if you may need the money early, this becomes an important point.

    5. Death Benefit

    Mutual funds do not provide a death benefit in the way an insurance contract does. If the investor dies, the units are transferred in accordance with the nomination and transmission process.

    Segregated funds may provide a death benefit guarantee to the beneficiary. Again, the actual amount will depend on the contract.

    6. Availability

    Mutual funds are widely available in India. You can invest through AMCs, brokers, and investment platforms.

    Segregated funds are different. They are mainly seen in markets such as Canada and are not a standard investment option in India.

    So, an Indian investor should not assume that both products are equally available.

    Read Also: Cyclical vs Defensive Stocks: Key Differences

    What Should You Check Before Choosing Between Mutual Funds and Segregated Funds?

    As an investor who is looking to invest, a proper comparison is important. You should know where you are investing and what you can expect in return. Some of the key points that you should consider over here are as follows:

    1. Your Investment Goal

    Start with why you are investing. It can be:

    • Retirement.
    • Long-term wealth creation.
    • Children’s education.
    • Buying a house.
    • Building a future corpus.

    Matching the fund with your goal will give you better returns and will help you ensure that your demands are met well. 

    2. Risk

    No matter which of the two you select, you will have some risk involved. A segregated fund may offer a guarantee, but that does not mean the investment value cannot move.

    Mutual fund risk also depends on the category. Hence, it is important that you understand the amount of risk you are willing to take and then select the fund.

    3. Charges

    When you are investing for the long run, there will be some costs that will keep adding up. In other words, even if there is a small charge, the same will look high when the total amount adds up in the near future. 

    Compare the benefits you can get with the charges that are paying for them. Ask whether those benefits are actually useful for you.

    4. Guarantee Conditions

    This is where you should spend some time. Mutual funds do not offer any type of guarantee. But if you see the segregated fund, there is a guarantee. This needs to be checked properly, and you must see what it means and how it can benefit you. The benefit can change based on how you use the product.

    5. Investment Period

    Your time period also matters. If you need money after two years, a product with a long maturity condition may not work well.

    Similarly, some mutual funds are better suited for longer holding periods because the market can move sharply in the short term.

    So, match the product with the actual time you have.

    Conclusion

    Mutual funds and segregated funds both invest in market-linked assets. But the structure of both is different. This is where you need to actually evaluate and analyse the same well. As an investor, knowing the details and getting support from an expert should be very useful.

    This is where Pocketful can help you. The platform offers you details of where to invest, how much to invest, and also the comparison, which can save your time and ensure better outcomes.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Stock PE vs Industry PE: Key Differences
    2High-Priced vs Low-Priced Stocks: Key Differences
    3MTF Charges vs Normal Trading Charges: Key Differences
    4Commodity Futures vs Options in India: Key Differences
    5Discount Broker vs Full-Service Broker: Key Differences

    Frequently Asked Questions (FAQs)

    1. What Is the Main Difference Between Mutual Funds and Segregated Funds?

      Mutual funds are mainly used for investment. Segregated funds also invest in market-linked assets but come with an insurance contract and may offer certain guarantees.

    2. Are Segregated Funds Available in India?

      Segregated funds are not commonly available in India. They are mainly seen in countries such as Canada.

    3. Are Segregated Funds Risk-Free?

      No. The investment value can still fall. The guarantee applies only as per the terms and conditions of the contract.

    4. What Is a Segregated Portfolio in Mutual Funds?

      A segregated portfolio is created within a mutual fund when certain securities face a credit event. It keeps the affected securities separate from the main portfolio.

    5. Which Is Better, Mutual Funds or Segregated Funds?

      It depends on what you need. Mutual funds may work for regular market-linked investing, while segregated funds may suit investors who also need certain insurance-linked benefits.

  • What Is Stamp Duty on Mutual Funds? How It Works

    What Is Stamp Duty on Mutual Funds? How It Works

    Do you come across any deductions on your mutual funds before allocating the number of units to you? That small deduction is referred to as stamp duty. But then what exactly does stamp duty mean when it comes to mutual funds?

    Simply, it is a small tax collected by the government whenever you buy new mutual fund units. Whether you are new to investing or have been doing it for years, knowing about the mutual fund stamp duty helps you understand exactly where your money goes. Let us break down everything you need to know about it.

    Stamp Duty vs Other Mutual Fund Charges

    When we talk about Stamp duty on mutual fund investments in India, it is important to see how it stands apart from other fees. Stamp duty is basically a one-time tax levied by the government on the issue or purchase of mutual fund units.

    The mutual fund world involves many bodies. You have the market regulator SEBI, the industry body AMFI, your fund house or AMC, and registrars like CAMS or KFintech. The AMC and registrars work together to collect this duty and pass it to the government.

    It is different from an Expense Ratio, which is a daily management fee charged by the fund house. It is also different from an Exit Load, a penalty you pay if you withdraw your money too soon. Then there is the Securities Transaction Tax (STT), which applies mainly when you sell equity funds.

    Knowing the difference helps you plan your investments better. It stops you from getting confused when you see different deductions in your account statement.

    A Quick Comparison

    FeatureStamp DutyExpense RatioExit LoadSecurities Transaction Tax (STT)
    What is it?Government tax on buying unitsYearly fee for managing your fundPenalty for early withdrawalGovernment tax mostly on selling
    When is it charged?When buying mutual fund unitsDeducted daily from the fund NAVWhen you sell before a set timeUsually when selling equity funds
    Who gets the money?The GovernmentThe Asset Management Company (AMC)The mutual fund schemeThe Government

    Which Mutual Fund Transactions Attract Stamp Duty?

    A very common question investors ask is about Stamp duty on mutual fund transactions. The rule is very simple. The government charges this duty only when new units are created and allotted to you.

    Here are the transactions where stamp duty applies:

    • Lump sum purchases: When you invest a big amount in one go.
    • SIP instalments: Every time your monthly Systematic Investment Plan buys new units.
    • Switch-in: When you move your money into a new mutual fund scheme.
    • STP (Systematic Transfer Plan): When a set amount is transferred to a new scheme regularly.
    • Dividend or IDCW reinvestment: When your earned dividends are used to buy more units instead of being paid out.

    Now, what about the times when it does not apply? You will be happy to know there is no Stamp duty on mutual fund redemption. When you sell your units to get your money back in your bank account, this duty is not charged. Similarly, switch-out transactions and SWP (Systematic Withdrawal Plan) do not attract this duty because no new units are being created. Understanding that redemption is free from this tax brings a lot of relief to regular investors.

    Why Should You Know About Stamp Duty on Mutual Fund Investments?

    Even though the amount is very small, being aware of it makes you a smarter investor. Here is why you should care:

    • Being Aware of the Actual Amount Being Invested: In case of investing Rs 10,000, a little less amount is invested due to the deduction of the duty.
    • Assessing the True Cost of Investment: Every cost does matter in the long term. Understanding the true cost imposed by the government and AMC will help you understand better.
    • Comparing It with Other Mutual Fund Charges: Once you know this is a tiny one-time government tax, you will not confuse it with the AMC expense ratio.
    • Planning Your SIP Amount Better: If you want an exact number of units, you will need to invest slightly more to cover the tax.
    • Avoiding Confusion Between Purchase and Redemption Charges: Many people worry about paying taxes while pulling money out. Knowing this duty is only for purchases gives you complete peace of mind.

    How Is Stamp Duty on Mutual Fund Investments Calculated?

    The calculation is quite straightforward. A standard rate of 0.005% is applied on the purchase amount, and this has been effective since 1 July 2020.

    • Step-by-Step Calculation: First, the system takes your total investment amount. On this net amount, a 0.005% duty is calculated. Finally, this tiny duty is deducted, and the remaining money is used to buy your units.
    • A Simple Example with Numbers: Suppose you invest Rs 10,000. The stamp duty at 0.005% will be just 50 paise. If you invest a larger amount like Rs 1,00,000, the duty comes to exactly Rs 5. Therefore, Rs 99,995 is used to buy your mutual fund units.
    • Who Collects and Pays the Duty: You do not have to fill out any separate forms or go to a government website. Your AMC or registrar automatically collects this money from your investment and pays it directly to the government.
    • How It Shows Up in Your Statement: When you look at your account statement, you will see your total investment. Just below that, there will be a clear mention of the duty deducted and the exact number of units allotted to you.
    • This Will Apply to All Types of Investors: There is no difference in terms of the person holding the shares. Irrespective of whether you are an individual, joint, HUF, minor, NRI, or even a company, the charge levied remains exactly the same – 0.005%.

    Read Also: Indexation in Mutual Funds: Tax Rules

    How to Check Stamp Duty on Your Mutual Fund Transactions

    Checking this deduction is very easy. Most modern apps and statements show it clearly. Here are a few simple steps to find it:

    • It is extremely easy to check this calculation: Almost all modern applications and statements provide this information. Here are just a few steps to verify it.
    • Log in to your mutual fund application, trading terminal, or website of the AMC: Get access to your application or website from where you can see your mutual fund account.
    • Transaction Statement/CAS Access: Obtain your latest transaction statement either from the application or via email.
    • Find the Stamp Duty Deduction in Every Purchase: Find your most recent purchase/SIP. Just beneath or right beside the investment amount, there will be a minor deduction marked as stamp duty.
    • Cross-verify this amount with Units Allotted: Multiply your allotted units with the Net Asset Value (NAV) on that date. It will fit perfectly with your investment less the duty.

    These steps are general and work for most platforms. The exact buttons or menus might differ slightly depending on the app you use. If you want a smooth experience checking all your investments, you can always explore the Pocketful platform.

    Stamp Duty Rate, Charges and Impact on Your Returns

    Many beginners worry that taxes will eat up their profits. Let us look at the real impact:

    • The Current Rate: At 0.005% on purchases, the fee is incredibly small. For every Rs 10,000, you pay less than a Rupee.
    • No Stamp Duty on Redemption: As discussed earlier, you only pay when you buy. Taking your money out does not attract this specific tax.
    • The Size of Its Effect on Long-Term Returns: Since it is an upfront payment, the effect becomes virtually zero in the long run. With investments for five or ten years, even if there was a Rs 5 charge on an investment of Rs 1,00,000, it becomes totally insignificant.
    • How It Is Different from Exit Load and Expense Ratio: Exit load and expense ratio take a much bigger bite out of your returns compared to this tiny government tax.
    • Why It Is Important to See the Latest Guidelines: Rates of government securities keep changing sometimes. It is always a good practice to see the updates given by SEBI, AMFI, or the government itself.

    Benefits of Understanding Stamp Duty on Mutual Fund Transactions

    Why should a regular investor care about such a small fee? Here is how knowing about it helps you:

    • Greater Transparency Regarding Your Payment: You will never wonder where that little money disappeared from your statement.
    • Proper Financial Budgeting: You can always budget for the exact amount you need to invest.
    • Less of a Surprise when Looking at Your Account Statement: It allows you to know everything that appears on your Consolidated Account Statement.
    • Confidence when Comparing Investment Platforms: If you know that it is a mandatory government charge, then you will not mistakenly think that your broker/AMC is charging you extra.

    Common Mistakes Investors Make About Mutual Fund Stamp Duty

    Even experienced investors sometimes get confused. Here are a few common mistakes you should avoid:

    • Stamp Duty Is Paid on Redemptions: People fear selling since they believe they have to pay this tax once again. Just remember that it is applicable on purchases only.
    • Getting Confused Between Stamp Duty, Exit Load, or Expense Ratio: These terms are entirely different from one another. The expense ratio is a yearly charge, whereas the exit load is charged in case of premature redemption.
    • Calculating Units Without Deducting the Duty: If you are manually calculating the number of units, which you are entitled to receive without deducting the stamp duty from your total amount, you would be making a mistake.
    • Not Reading Your Statement Periodically: You must make a habit of reading your statements to make sure that things are fine and your money is doing well for you.
    • Being Fooled by Fake Calls/Links Related to Stamp Duty: Sometimes scammers may call you up saying that the stamp duty needs to be paid for you.

    Simple Tips to Manage Mutual Fund Costs Wisely

    Every penny saved is a penny earned. Here are some tips to ensure that you keep your investment costs low and yields high.

    • Reading Scheme Documents Before Investment: Always take care to understand everything about the charges, such as the expense ratio and exit load.
    • Reviewing Your Statement After Every Transaction: It should always be a good habit for you to review your Consolidated Account Statement to see if everything is deducted properly.
    • Cost Comparison Between Direct & Regular Plans: Direct plans have a low expense ratio since there are no distributor commissions. This results in huge savings for you compared to stamp duty.
    • Invest for a Longer Period of Time: As time passes after you buy your investment in mutual funds, the impact of time costs, such as stamp duty, will be reduced.
    • Use Only the Official Mobile Application: For tracking as well as investing, make sure that you use only the official mobile application of your AMC or registered broker.

    Read Also: What is Mutual Fund Unit and How does it Work?

    Conclusion

    Understanding the small charges involved in your investments is a big step toward financial discipline. The stamp duty on mutual funds is a very small, one-time government charge that makes your purchase legally sound. It has almost no real impact on your long-term wealth creation. By keeping yourself informed about these simple concepts, you can invest with total peace of mind and watch your money grow without any unnecessary worries.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What is the current stamp duty rate on mutual funds in India?

      The current rate is 0.005% on the purchase amount. This rule has been in place since 1 July 2020.

    2. Do I have to pay stamp duty when I sell my mutual funds?

      No, you do not have to pay it when you sell. Stamp duty is only charged when new units are created and allotted to you.

    3. Is this duty applicable to my monthly SIPs?

      Yes. Every time your monthly SIP goes through and buys new units, a small 0.005% duty is deducted from that specific instalment.

    4. How do I pay this stamp duty to the government?

      You do not need to do anything manually. Your mutual fund house or the registrar automatically deducts it from your investment amount and pays the government.

    5. Will this small tax affect my long-term returns?

      Not at all. Because it is a tiny one-time charge of 0.005%, its impact on your wealth over five or ten years is practically zero.

  • Open Free Demat Account

    Join Pocketful Now

    You have successfully subscribed to the newsletter

    There was an error while trying to send your request. Please try again.

    Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.