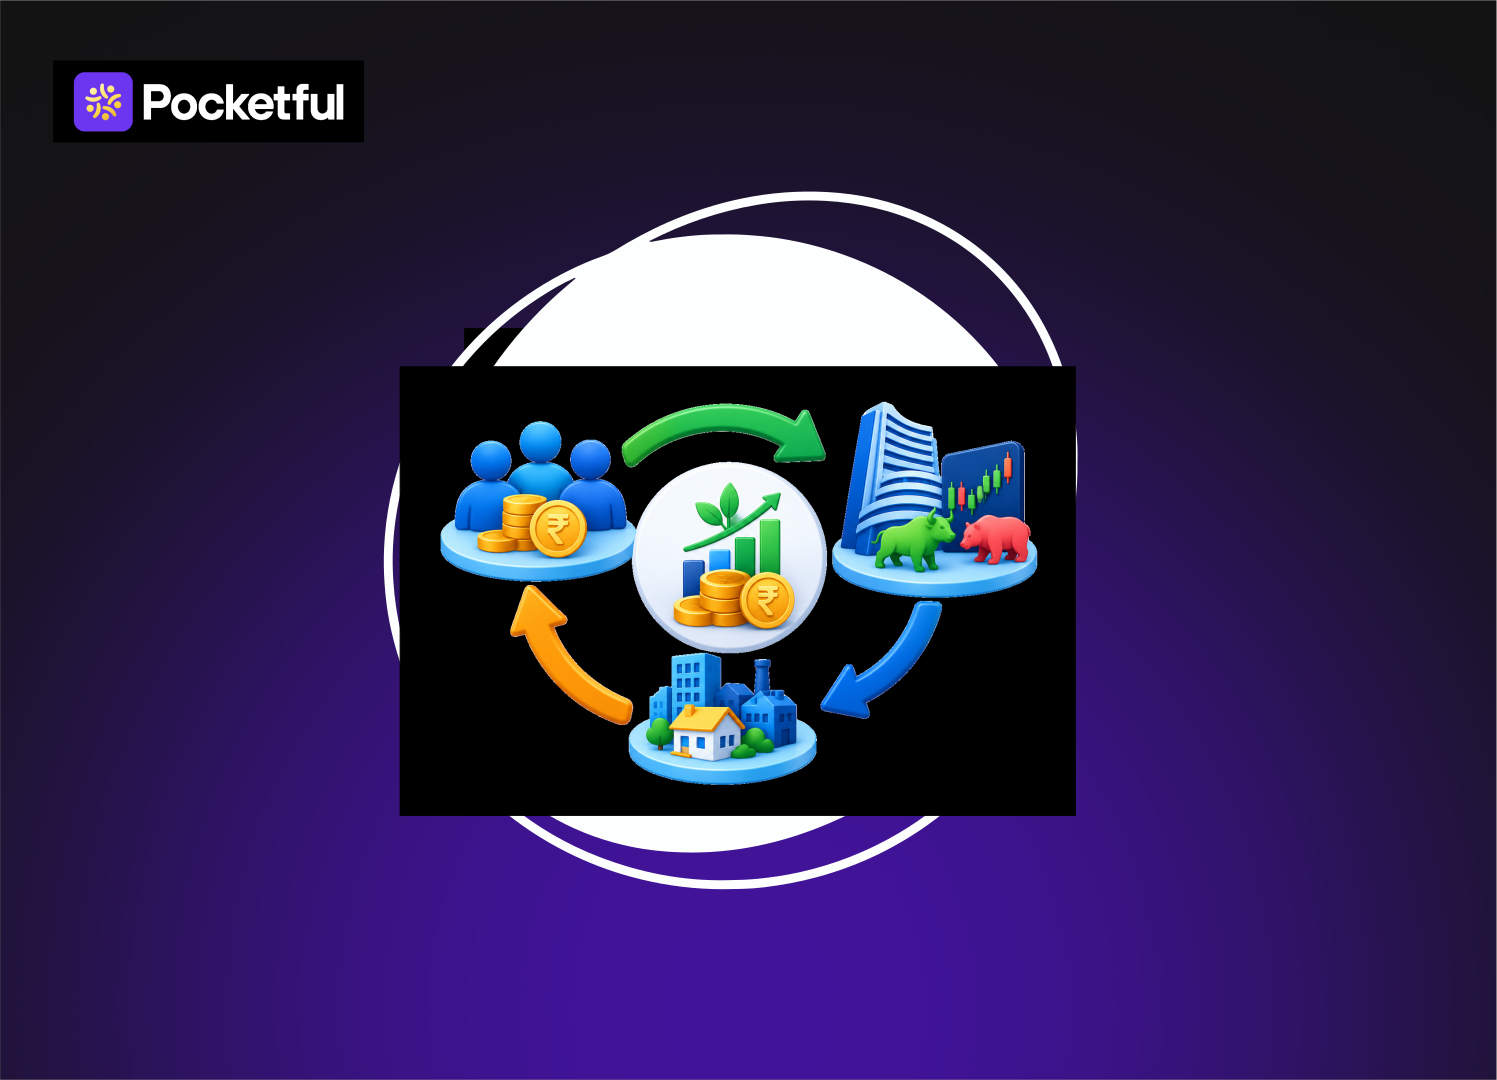
Ask most people where their money goes after they pay a SIP instalment or park cash in a fixed deposit, and you’ll get a blank look. The money does not vanish, of course. A bank lends it to a business, an insurer puts it into government bonds, a mutual fund buys shares. Economists track this entire movement through something called the flow of funds.
In India, the Reserve Bank of India compiles these accounts every year, and they show who is saving, who is borrowing, and which financial products connect the two.
In today’s blog, we will find out what is the flow of funds, how it actually works, and why you should understand the concept.
What is Flow of Funds (FOF)?
Flow of funds is a series of accounts that provide information about financial transactions among the various sectors of an economy over a period of time, typically a financial year. It provides answers to a fundamental question: how much money did each sector raise, and what did they do with it?
Not all individual and company accounts are included. They group them. In the Indian context, you will find households, non-financial companies, financial companies (banks, insurers, mutual funds and NBFCs), the government (Centre and states combined) and the rest of the world.
Some of these sectors have surplus money, which means that they make more money than they spend. Some spend more than they make and are in debt. The accounts record both of them, and they also record the instruments in between, such as deposits, loans, bonds, shares, insurance policies, and provident funds.
How Does Flow of Funds Work?
Every sector earns income, spends part of it, and saves what remains. That saving can go towards real assets, such as a house, a machine, or a factory, or it can be lent out as a financial asset.
1. The Net Lender/The Net Borrower
If a sector saves more than it invests in real assets, it ends up as a net lender. If it needs more than it saves, it becomes a net borrower. Indian households have long been the biggest net lenders since they save more. Their money lies in bank deposits, LIC policies, EPF and PPF accounts, post office schemes, mutual funds, etc. Companies and the government are on the other side. They usually need more funds than they generate, for expansion in one case and for public spending in the other.
2. The Intermediaries
Then come the intermediaries. A bank accepts deposits from lakhs of households and turns them into loans for businesses, home buyers and, indirectly, the government through bond purchases. A mutual fund gathers small investments and spreads them across equity and debt. Insurers invest premiums, much of it in government securities. None of these institutions produces much of their own money. Their job is to move it from people who have it to people who can use it.
3. The Foreign Sector
When the economy borrows more than it saves, the difference comes from overseas through foreign direct investment, portfolio flows, or external commercial borrowings. That’s why the rest of the world has its own column in the accounts.
One rule holds everything together. A financial asset for one party is always a liability for another. Your fixed deposit is your asset and the bank’s liability. A government bond held by an insurer is the insurer’s asset and the government’s liability. Because of this, if you add up the net lending and borrowing of every sector, including the foreign one, the answer is zero.
What is a Flow of Funds Matrix
It is a comprehensive macroeconomic accounting grid that tracks the movement of financial resources and credit across sectors of an economy.
It acts like a nationwide spreadsheet where everyone’s spending and income connect and balance out.
Columns represent economic sectors that include
- Households (including NPOs)
- Non-financial companies (Commercial businesses)
- Financial Institutions (banks, AMCs, insurance companies)
- Central & State Government
- Rest of the World
Rows represent Financial Instruments and Transactions (tools through which money moves):
Currency and bank deposits are the simplest. Loans, government securities, corporate bonds, equity shares, mutual fund units, life insurance funds, and small savings follow. Each one shows up as a separate line in the matrix.
Sources & Uses of Funds:
Furthermore, each sector’s column is subdivided into Sources of Funds and Uses of Funds. Sources are what a sector raises, through borrowing, issuing shares or accepting deposits. Uses are where the money goes: lending, buying securities, holding deposits and so on.
At last comes the net financial position, which is the gap between uses and sources. It tells you in one number whether a sector is feeding money into the system or drawing it out.
Read Also: What is Fund of Funds (FOF)?
Example of Flow of Funds (FOF)
Below is an easy tabular illustration for better understanding
| Sector | Funds raised (sources) | Funds invested or lent (uses) | Net position |
|---|---|---|---|
| Households | 10 | 110 | 100 |
| Non-financial corporations | 120 | 60 | -60 |
| General government | 50 | 10 | -40 |
| Financial corporations | 200 | 200 | 0 |
Take households first, since their numbers are the easiest to follow.
Over the year, they put ₹110 crore into bank deposits, insurance premiums, EPF and PPF, mutual funds and shares. However, they borrowed only ₹10 crore through home and personal loans.
Subtract one from the other, and you get a surplus of ₹100 crore. In simple terms, households had that much more to lend than they needed for themselves.
Let us come to companies now. They raised ₹120 crore through bank loans, bonds and fresh equity, but they did not spend all of it. ₹60 crore stayed in financial form, in deposits or invested elsewhere. The difference is ₹60 crore, which is their net borrowing.
The government is in a similar position, though its numbers are smaller. It raised ₹50 crore through market borrowings and small savings schemes and held back ₹10 crore in financial assets. That leaves it ₹40 crore short.
Banks, insurers and mutual funds lie in between all of this. They collected ₹200 crore from deposits, premiums and fund units, and they gave away the same ₹200 crore as loans and securities. Nothing was left, so their net position is zero.
Now put the net figures side by side. Households are ahead by ₹100 crore, while companies and the government are behind by ₹60 crore and ₹40 crore, which adds up to the same ₹100 crore. The two sides cancel out exactly, as they always must.
In a real RBI table, you would also see the foreign sector, and the balancing would depend on overseas capital coming in or going out.
Importance of Flow of Funds
- Helps in understanding the economic activity: It helps to find how funds move between different sectors of the economy, and helps analysts understand how savings are used for investments and how borrowing supports economic activities.
- Tracks Savings & Investments: FOF helps in explaining how savings from households and other sectors are moved into financial assets, business investments, and lending, which gives a clear picture of how available financial resources are allocated across the economy.
- Helios Financial Planning: Businesses can use fund flow analysis to understand their sources of funds and how they are being used, and this helps them plan future expenses, manage financial resources, and identify funding needs.
Conclusion
Flow of funds provides clear, structured insight into the movement of money in India. It demonstrates who is saving, who is borrowing, which products link them up, and the matrix provides a view of all of this in one place. The key rule, one’s asset is always another’s liability, ensures consistency in the entire system.
If you are handling any kind of money, from being a student to an analyst to an investor, it’s worth spending some time with these accounts.
They describe the importance of saving in a household, the role of the banks and mutual funds in channelling the savings, and the role of government borrowing and foreign inflows. Understanding the framework makes RBI publications easier to read, and your savings and investments appear to be a small but real part of a very big picture.
Frequently Asked Questions (FAQs)
What is Flow of Funds?
It tracks the flow of funds among the various sectors in an economy, including the households, the business sector, the banking sector, and the government sector.
What is the main purpose of the flow of funds?
The primary objective is to get an understanding of where the funds are being spent, how they are being spent, and how they flow through each sector.
What are the major elements of FOF?
The major elements are sources of funds, uses of funds, and financial transactions among sectors.
Explain the difference between Flow of Funds and Cash Flow.
While flow of funds measures the movement of financial resources and financial transactions, cash flow measures the movement of cash and cash equivalents.
Who uses the Flow of Funds analysis?
Economists, financial analysts, businesses, government authorities, and investors use FOF to understand financial trends.