Blog

  • Jio Platforms IPO Allotment Status, GMP & Listing Date

    Jio Platforms IPO Allotment Status, GMP & Listing Date

    Jio Platforms, one of India’s leading digital and telecommunications companies, is launching an initial public offering (IPO) to raise up to ₹30,213 crore. The issue opens for subscription on October 21, 2026, and will close on October 23, 2026, with a price band fixed at ₹1,065 to ₹1,119 per share. Since the IPO is entirely a fresh issue of shares, the company will receive the proceeds from the offering, primarily to repay debt of its subsidiary, Reliance Jio Infocomm, and for general corporate purposes. The shares are proposed to be listed on the Bombay Stock Exchange (BSE) and the National Stock Exchange (NSE) on October 28, 2026, subject to allotment and necessary regulatory approvals.   

    Jio Platforms IPO Day 3 Subscription Status

    On Day 3, Jio PlatformsIPO witnessed a good investor turnout, closing with an overall subscription of 18.30 times, QIB led the Subscription 55.12 times, The Non-Institutional Investors 13.83 times subscription Overall, indicating good participation. Among Non-Institutional Investors (NII), the bNII (above ₹10 lakh) portion was subscribed 15.74 times, while the sNII (less than ₹10 lakh) segment saw 10.01 times subscription. Shareholders category subscribed by 7.47. The Retail Individual Investors (RII) category was subscribed 2.69 reflecting healthy retail interest, the issue garnered 1,34,29,582 applications, with total bids amounting to approximately 4,04,416.60 crore, showcasing confidence across investor categories in the company’s growth potential.

    Investor CategorySubscription (x)
    Qualified Institutional Buyers (QIB)55.12
    Non-Institutional Investors (NII)13.83
    bNII (above ₹10 lakh)15.74
    sNII (less than ₹10 lakh)10.01
    Retail Individual Investors (RII)2.69
    Total Subscriptions18.30

    Total Applications: 1,34,29,582

    Total Bid Amount (₹ Crores): 4,04,416.60

    How to Check Jio Platforms IPO Allotment Status?

    Jio Platforms IPO allotment can be easily checked online in two ways: from the Registrar’s website and from the NSE & BSE website. This IPO will be listed on NSE & BSE exchanges, so the allotment status will be available to all investors on both platforms.

    Method 1: Registrar’s website (KFin Technologies Limited)

    The most reliable way is to check allotment from the KFin Technologies Limited website.

    How to do:

    • Visit KFin Technologies Limited official website
    • Select “Jio Platforms” from the IPO list
    • Enter your details PAN number, Application number, or DP/Client ID
    • Click on Submit
    • You will see the allotment status on the screen.

    Method 2: Check from NSE & BSE website

    If there is more traffic on the registrar’s website, allotment status can also be checked from NSE & BSE.

    How to do:

    • Visit NSE or BSE official website
    • Select ‘Equity’ segment
    • Select “JIO Platforms” from the IPO list
    • Enter PAN number and Application number
    • Click on Search

    Objective of the Jio Platforms IPO

    For Jio Platforms IPO, the issue is a 100% fresh issue of shares, with no Offer for Sale (OFS) component. Therefore, the company will receive the entire proceeds from the IPO, amounting to approximately ₹30,213 crore at the upper end of the price band. The funds are intended to be used primarily to repay certain borrowings of its subsidiary, Reliance Jio Infocomm, and for general corporate purposes. 

    Use of IPO ProceedsAmount (₹ Cr)
    Proceeds to be received by Jio Platforms through Fresh Issue  ₹30,213

    Jio Platforms IPO – Day 3 Update

    The grey market premium (GMP) of the Jio stands at ₹242 as of October 23, 2026 (Day 3). Considering the upper end of the price band at ₹1,119 per share, the estimated listing price is around ₹1361, reflecting a potential gain of approximately 21.63% per share in the grey market.

    DateGMPEst. Listing Price Gain 
    21-10-2026 (Day 3)₹242₹1,36121.63%

    Disclaimer: The above GMP (Grey Market Premium) is just unofficial market information, which is not officially confirmed. These figures are shared for informational purposes only and investment decisions based on these should be based on the investor’s own research and discretion. We do not conduct, recommend or support any kind of transaction in the grey market.

    Jio Platforms IPO IPO – Key Details

    ParticularsDetails
    IPO Opening DateOctober 21, 2026
    IPO Closing DateOctober 23, 2026
    Issue Price Band₹1,065 to ₹1,119 per share
    Total Issue Size27,00,000 shares (aggregating up to ₹30,213 Cr)
    Listing PlatformNSE & BSE
    RegistrarKFin Technologies Limited 
    DRHPJio Platforms

    Important Dates for Jio Platforms IPO Allotment

    EventDate
    Tentative AllotmentSeptember 29, 2026
    Refunds InitiationSeptember 29, 2026
    Credit of Shares to DematOctober 01, 2026
    Listing Date October 24, 2026

    Overview of Jio Platforms 

    Jio Platforms is a digital financial services platform in India that provides a range of financial products and services through its technology-driven platform. The company primarily operates in the lending and personal finance space, connecting customers with credit and other financial solutions through its digital ecosystem. Jio Platforms has built a strong presence in India’s growing digital lending market, supported by its technology platform, customer reach, and data-driven approach. With increasing digital adoption, rising demand for convenient financial services, and the continued expansion of India’s fintech ecosystem, Jio Platforms is positioned as a growing player in the country’s digital financial services landscape. 

    Frequently Asked Questions (FAQs)

    1. What is the opening and closing date of the Jio Platforms IPO ?

      Jio Platforms IPO  will open on 21 October 2026 and will close on 23 October 2026.

    2. What is the price band of the Jio Platforms IPO ?

      Its price band is fixed from ₹1,065 to ₹1,119 per share.

    3. What is the GMP (Grey Market Premium) of the Jio Platforms IPO today?

      The GMP on 21 October 2026 is ₹242, which leads to a possible listing price of ₹1,361.

    4. What is the total issue size of the Jio Platforms IPO?

      The total issue size of the Jio Platforms IPO is ₹30,213 crore, The IPO is entirely a fresh issue

    5. What is the expected listing date of  the Jio Platforms IPO?

      This IPO is expected to be listed on NSE & BSE on September 28, 2026.
  • Nifty CPSE Index: Meaning, Stocks & Weightage

    Nifty CPSE Index: Meaning, Stocks & Weightage

    India’s stock market has a number of indices. Every index is used to track the performance of different groups of companies. The Nifty CPSE Index is one of them. The Nifty CPSE Index follows a select group of Central Public Sector Enterprises listed on the exchange. These are companies where the Central Government holds a majority stake, and you will recognise a few of them straight away, such as NTPC, Coal India and Bharat Electronics.

    Put together, they show how government-run businesses are faring in the market. Because the index leans heavily on power, oil and gas, and infrastructure, it also shows how those sectors are doing. 

    In this blog, we look at what the index is, how it works, and the ways you can invest in it.

    What is the NIFTY CPSE Index

    The NIFTY CPSE Index is a thematic equity index managed by NSE Indices Limited. It includes selected listed CPSEs that meet the eligibility criteria set by the exchange. It started with a base date of 1 January 2009 and a base value of 1,000, and it was launched on 18 March 2014. It is a small and concentrated index. As per the latest factsheets, it holds 11 stocks.

    Why was the NIFTY CPSE Index created?

    This index was formed to support the government’s disinvestment programme. 

    Disinvestment simply means that the government sells a part of its holding in public sector companies to raise funds. 

    An exchange-traded fund (ETF) gave the government a more organised route. Retail and institutional investors could buy a single product that held several CPSE stocks together, and the government could sell its stake through that product in phases. 

    The NIFTY CPSE Index was built to be the benchmark for that ETF. So the index exists first as a source of disinvestment and as an investment theme.

    Features of the NIFTY CPSE Index

    • Follows a Theme: It is a thematic index, which means it follows one idea (government-owned enterprises) rather than the whole market. It is not a broad, diversified benchmark like the NIFTY 500.
    • Free-float Market Capitalisation: It uses a free-float market capitalisation approach with capping. Free float means only the shares available for public trading are counted, not the shares held by the government. Capping helps to limit how much weight any single stock can carry at the time of rebalancing, so that one large company does not take over the index.
    • Reviewed Quarterly: The index is reviewed, and its weights are realigned every quarter. Between those dates, a stock’s weight can drift higher or lower with its share price.
    • Concentrated to 11 stocks: Sector exposure is narrow. The May 2026 factsheet showed power holdings in power, oil, gas and consumable fuels, capital goods, and construction. There is no banking, IT or consumer goods in the mix, which is a big difference from the NIFTY 50.
    • Regular Dividend Payouts: The index has also tended to pay decent dividends, since many PSUs distribute a good part of their profits. The aggregate dividend yield has generally stayed in the range of roughly 2% to 3%, though it moves with prices.

    Factors Affecting the NIFTY CPSE Index

    1. Government Policies

    • Every company in the index is government-controlled, so a policy call in Delhi can show up in the share price the same day.
    • Disinvestment announcements, dividend directions and regulatory changes are the usual triggers.
    • Pricing rules matter as well, particularly for power, gas and fuel companies, where the government has a say in what can be charged.

    2. Commodity Prices

    • Coal India’s earnings track coal realisations. The oil and gas names track crude.
    • A sharp fall in either can affect profits within a quarter or two.
    • Since these sectors carry a heavy share of the index, the effect is rarely small.

    3. Infrastructure Spending

    • Higher capital spending by the Centre on power projects, transmission lines and defence orders helps NTPC, Power Grid and Bharat Electronics.
    • Power was close to 45% of the index in the May 2026 factsheet. If that spending slows, the index feels it more than a diversified one would.

    4. Company Performance

    • Results and dividends drive each stock, as with any listed company.
    • The difference here is size. With just 11 stocks, one disappointing quarter from a large constituent can drag the whole index.

    5. Overall Market Conditions

    • Interest rates, foreign investor flows, and general sentiment all play a part.
    • A weak market can pull PSU shares down even when the companies themselves have posted decent numbers.

    Read Also: CPSE ETF: What Is It, Benefits, Risks & How to Invest

    How does it work?

    NSE Indices selects the stocks according to its methodology. In simple terms, the company must be a CPSE where the government holds the required stake, it must be listed, and it must meet liquidity and size requirements. Eligible stocks are then weighted by free-float market capitalisation, with the cap applied.

    The index value is calculated in real time during market hours. Every quarter, the weights are reset to match the methodology. When a stock no longer qualifies, or a new one becomes eligible, the constituent list is updated.

    You cannot buy the index directly. Investors can invest through an ETF or an index fund that tracks it. Since these products try to replicate the index, their returns will be close to the index, after adjusting for a small tracking difference and expenses. 

    Selection Criteria for Nifty CPSE Index 

    The CPSEs selected meet the below-mentioned parameters: 

    • Included in the list of CPSEs published by the Department of Public Enterprises
    • Listed on the National Stock Exchange of India Ltd. (NSE) 
    • Having more than 51% government holding (stake via Govt. of India or President of India) under the promoter category. 
    • Companies having average free float market capitalization of more than 1000 Cr. for 6 months period ending December 2019 are selected. 
    • Companies which are IRDA dividend norms compliant shall be considered eligible to be included in the index 

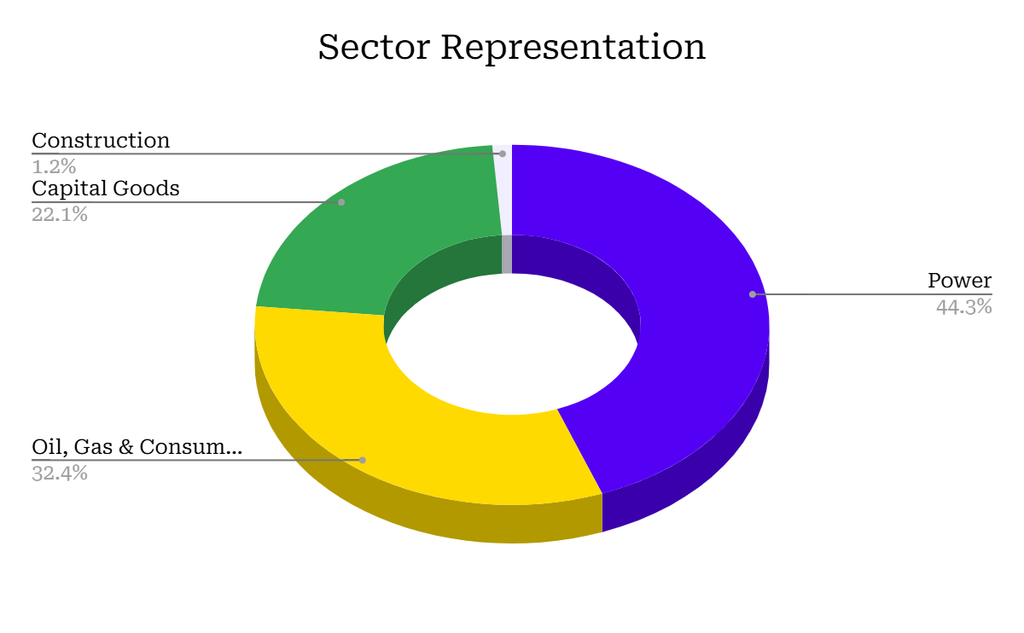
    Weightage of Sectors in CPSE Index

    SectorWeight (in%)
    Power44.3
    Oil, Gas & Consumable Fuels32.35
    Capital Goods22.12
    Construction1.23

    Top Index Constituents by Weightage 

    Below is the list of NIFTY CPSE Index Stocks

    S. NoCompany NameWeight (%)
    1NTPC Ltd.20.23%
    2Bharat Electronics Ltd.20.20%
    3Power Grid Corporation of India Ltd.17.84%
    4Coal India Ltd.15.39%
    5Oil & Natural Gas Corporation Ltd.13.26%
    6NHPC Ltd.4.15%
    7Oil India Ltd.3.70%
    8Cochin Shipyard Ltd.1.92%
    9NLC India Ltd.1.44%
    10NBCC (India) Ltd.1.23%

    Nifty CPSE Index Performance 

    Index Returns (%)QTDYTD1 Year5 YearsSince Inception
    Price Return-6.99%-2.14%-3.57%21.40%10.85%
    Total Return-6.26%-0.60%-1.55%24.71%14.30%
    (data as of 30th September, 2026)

    Read Also: What Is Nifty ETF?

    Conclusion 

    This index shows how a group of government-owned companies is performing in the stock market. Most of them come from power, oil and gas, and infrastructure. If you like the idea of investing in these businesses but do not want to pick and track each stock yourself, an ETF that follows the index is the simpler way to do so.

    That said, PSU stocks do not move only on company results. A policy change, a pricing decision by the government, a shift in the market, or a slowdown in the sector can all pull them up or down. So before putting money in, look at the risks properly and ask whether this kind of exposure fits what you are trying to achieve with your money.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1GIFT Nifty vs Nifty 50: Key Differences
    2Nifty Weekly Options Strategy for Beginners
    3Bank NIFTY Intraday Options Trading: Steps, Strategies & Tips
    4NIFTY Next 50 – Meaning, Types & Features
    5Options Trading Strategies

    Frequently Asked Questions (FAQs)

    1. What is the NIFTY CPSE Index?

      It is an NSE index that tracks listed Central Public Sector Enterprises. It was designed to support the government’s disinvestment programme through the ETF route.

    2. How many stocks are in the NIFTY CPSE Index?

      As per recent factsheets, it holds 11 stocks. These can change after a review.

    3. When is the index rebalanced?

      The weightage of these stocks is realigned every quarter, and the constituent list is updated when companies stop or start meeting the eligibility criteria.

    4. Does the index pay dividends?

      The companies in it have a record of paying dividends, and the index’s aggregate dividend yield has usually stayed between roughly 2% and 3%. Dividends are not guaranteed.

    5. What is the P/E ratio of the CPSE index? 

      P/E Ratio of this index is 12.02 as of 30th September, 2026. 

  • Junk Bonds: Meaning, Types, Risks & Ratings in India

    Junk Bonds: Meaning, Types, Risks & Ratings in India

    Say your bank FD pays 7%, and someone shows you a bond paying 12%. Sounds tempting? So many people’s first thought is, “Why isn’t everyone buying this?” The answer is that the bond is probably a junk bond, and that extra 5% is the price of a risk you may not have fully looked at yet.

    This blog covers what junk bonds are, how they work, how Indian rating agencies classify them, and who can reasonably hold them.

    What are Junk Bonds?

    A Junk bond is issued by a company whose credit rating is weak. A low rating means the agency sees a real chance that the company may struggle to pay interest or return your principal on time. You’ll hear Indian bankers and advisers say high-yield bonds or below investment grade bonds more often than “junk”, but it’s the same thing.

    The logic is easy to follow. If a friend with a steady salary asks to borrow money, you would lend it at a decent rate. If a friend whose business has uneven cash flow asks, you will definitely want more interest, because you are less sure of getting it back. Junk bond issuers are that second friend. They pay more because nobody would lend to them otherwise.

    How Do Junk Bonds Work?

    A company raises money from investors, pays a fixed coupon every year or every few months, and returns the face value when the bond matures.

    What changes is how much can go wrong in between. The company might delay a payment. It might default altogether. Or its rating might get cut again, and the bond price falls even though no default has happened yet. If you need to sell at that point, you will take the loss.

    The Liquidity Problem

    Liquidity is the other problem people do not consider. A lot of lower-rated bonds hardly trade on the exchanges. You may want to sell but do not find anybody on the other side, or only at a price that is not a good fit for you.

    Junk Bonds in India 

    1. IL&FS

    Start with IL&FS. Until mid-2018, it was a name that debt investors trusted, with top ratings to match. Then payments started getting delayed. 

    Within weeks, the ratings were cut sharply, and the damage did not stay with one company. Lenders, NBFCs, and debt funds holding its paper were all impacted, and the whole credit market turned cautious almost overnight. 

    2. Franklin Templeton

    Franklin Templeton’s story came two years later, in April 2020. The fund house closed six debt schemes, holding roughly ₹25,000 crore between them. These schemes had leaned on lower-rated bonds to squeeze out extra returns. COVID happened, investors rushed to redeem, and those bonds simply couldn’t be sold fast enough at a reasonable price. So the schemes stopped taking redemptions.

    Most investors did get their money back, and in many cases more than the value at the time of closure. But it took years.

    Read Also: How to Buy and Sell Bonds in India?

    Different Credit Ratings of Junk Bonds

    In India, ratings come from agencies like CRISIL, ICRA, CARE Ratings, and India Ratings. The scale runs from AAA at the top down to D, which means the issuer has already defaulted.

    The cut-off sits at BBB-. Anything at BBB- or above is called investment grade. Anything from BB+ downwards is junk territory.

    A BB-rated bond is speculative, so the issuer can probably pay today but carries a chance of trouble. 

    At B, repayment depends heavily on the business performing well. 

    C means default is a high possibility, and D means it has already happened. 

    You will also see + and – signs, and a BB+ is clearly in better shape than a BB-.

    Another thing about ratings is that they are not fixed for life. Agencies review issuers regularly, and a bond that looked decent when you bought it can get downgraded a year later. 

    Credit RatingCategoryMeaning
    AAAHighest SafetyLowest credit risk; strongest repayment capacity.
    AA to AHigh SafetyStrong repayment capacity with relatively low credit risk.
    BBB to BBB-Investment GradeAdequate repayment capacity but vulnerable to adverse conditions.
    BB+ to BB-Speculative GradeHigher credit risk; repayment may be affected by business conditions.
    BHighly SpeculativeRepayment depends heavily on favourable business conditions.
    CVery High RiskDefault is highly likely.
    DDefaultThe issuer has already defaulted on its debt obligations.

    Types of Junk Bonds

    1. Fallen Angels

    These bonds are issued by companies that used to be high-quality and financially stable. Due to market downturns, poor management, or rising debt, they were downgraded to the junk category. 

    2. Rising Stars

    These bonds are issued by young, fast-growing companies or startups that are still in their nascent stage. Their credit ratings start low, but they carry the potential to scale up as their business scales up. 

    3. Distressed Bonds

    These are bonds with no rating and are issued by a company already in trouble. Most retail investors should stay away from these completely.

    Did you know? 

    If you do not want to pick individual bonds, Credit risk mutual funds invest a large chunk in lower-rated papers on your behalf. It’s an easier route.

    Features of Junk Bonds

    • High Yield: Coupons of junk bonds are often in double digits, well above government securities or AAA corporate bonds. If you invest ₹1 lakh in a 7% FD, you earn ₹7,000 a year. The same money in a 12% bond earns ₹12,000, but only if the company actually pays.
    • High Returns: Higher returns come with higher default risk, and the bond’s price can also swing a lot on company news, sector troubles, or interest rate movements. Exits are difficult when compared with listed shares, since trading volumes are lower.
    • Secured/Unsecured: Some junk bonds are backed by collateral such as property or receivables, while others are unsecured. If things go wrong, a secured bond gives you a better chance of recovering at least part of your money.

    Who Should Invest in Junk Bonds? 

    Not everybody, and certainly not investors who are first-time bond buyers. If you have never invested in bonds, start with government securities or AAA-rated papers and get comfortable first.

    Junk bonds can be a fit if you already have a strong base of safer investments and want an allocation for higher returns. You should be able to lose that money without it changing your life. You should also be able to read a rating report and understand a company’s financials, and have enough time to wait through a bad patch.

    They are a poor fit for retirees who depend on regular income, or for money meant for something near-term like school fees or a house down payment. Don’t buy one just because the yield number looks nice on the screen.

    Most advisers suggest keeping this exposure to a small portion of your overall debt allocation and spreading it across several issuers, rather than one. Before buying, read the rating report, check the company’s cash flows, and find out whether the bond is secured.

    Read Also: Benefits of Investing in Bonds

    Conclusion 

    Junk bonds can pay you far more than an FD ever will. They can also leave you with delayed payments or a partial loss. If you want to try them, start small, stick to issuers you understand, and treat a very high coupon as a warning sign instead of a bonus. It is suggested that staying with safer bonds is a perfectly good decision. Not every portfolio needs this kind of risk.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What are War Bonds?
    2What is Sovereign Gold Bonds?
    3What is Coupon Bond?
    4What is Insurance Bond?
    5What are Social Bonds?

    Frequently Asked Questions (FAQs)

    1. Are junk bonds legal in India?

      Yes. Companies can issue lower-rated bonds, and they’re regulated by SEBI like any other debt security. The rating is disclosed in the offer document, so investors can see the risk before investing money.

    2. What is the difference between junk bonds and investment grade bonds?

      Investment grade bonds are rated BBB- or above and carry a lower chance of default. Junk bonds are rated BB+ or below, so they pay higher interest but are more likely to miss or delay payments.

    3. Can I lose all my money in a junk bond?

      It is possible, though not guaranteed. After a default, you may recover part of your money, particularly if the bond is secured. In other cases, recovery can be difficult or take years.

    4. How can a retail investor buy junk bonds in India?

      Listed bonds can be bought on NSE or BSE through your broker or an online bond platform. 

    5. Are junk bonds better than fixed deposits?

      They pay more, but they are not safer. Bank deposits up to ₹5 lakh per depositor are covered by DICGC insurance, and junk bonds have no such cover.

  • What is Reinvestment Risk? Meaning, Examples & Mitigation Strategies

    What is Reinvestment Risk? Meaning, Examples & Mitigation Strategies

    Earning interest on an investment is only one part of the picture – what happens when you get your hands on that interest or your investment comes to term? The rate on your next investment might be a lot lower than it was before.

    This situation is commonly known as reinvestment risk. And it’s one that can trip up investors who rely on fixed deposits, bonds, and other investments that pay out a predictable income.

    Understanding reinvestment risk can help you make better decisions about where to put your money, when to plough it back in and how to plan for the inevitable changes in interest rates.

    What is Reinvestment Risk 

    Reinvestment risk is the worry that you’ll earn lower returns when you put your interest payments or the original amount back into new investments.

    It often becomes a big deal when market interest rates take a dip. An investment that was a good option at the time might now be paying out less than comparable investments.

    For instance, imagine you put some cash into a fixed deposit earning 7.5% a year. When it finally matures, the banks are only offering 5.5% on similar deposits. If you put the cash back into a new deposit – your future interest payments are going to be lower.

    Reinvestment risk is a particular concern for investors who are getting regular interest payments or depend on their investments to generate a steady income.

    How Reinvestment Risk Works

    Reinvestment risk pops up when you have to put the cash generated by an investment straight back into another one.

    Think of it like a bond that makes interest payments every year. You get the cash and put it straight into another bond or fixed deposit. But if interest rates have dropped since you last invested – your new investment is likely to earn less than the old one.

    You get the same problem when a fixed deposit finally matures. You get the principal back and then have to decide where to put it next.

    There are three main factors that make this risk a bit more complicated:

    • Interest rates drop: When rates go down you have fewer options for getting a better return on your next investment.
    • How often you get paid: Investments that pay out interest regularly create more cash that you have to reinvest.
    • How long you’re investing for: The longer you’re in for the ride the more opportunities there are for rates to change before you need the money.

    Reinvestment risk doesn’t mean that your original investment has actually lost value – it just means that next time round you might not get the returns that you were expecting.

    Examples of Reinvestment Risk

    1. Fixed Deposit Reinvestment Risk

    Suppose you invest ₹10 lakh in a three-year fixed deposit offering 7.5% annual interest.

    Your annual interest would be ₹75,000, assuming a simple annual payout.

    When the deposit matures, the available rate for a new deposit may have fallen to 5.5%. If you reinvest ₹10 lakh at that rate, the annual interest would be ₹55,000.

    ParticularsOriginal FDNew FD
    Investment amount₹10,00,000₹10,00,000
    Annual interest rate7.5%5.5%
    Annual interest₹75,000₹55,000

    Your annual interest income would fall by ₹20,000. This illustrates how reinvestment risk can affect future income, even when the original principal is returned.

    2. Bond Reinvestment Risk

    Suppose you go out and buy a corporate bond valued at ₹5 lakh that pays 9% annual interest – and you get ₹45,000 every year.

    So, if the market interest rates suddenly drop and new bonds offering 6.5% start floating around, you might find that just throwing the ₹45,000 into a new investment isn’t going to be the cash cow you expected.

    Now, in reality this is all going to depend on the investment you actually put the ₹45,000 into – how much risk it carries and what it’s going to earn at the time you need to reinvest.

    3. Reinvestment of Interest – The Bigger Picture

    There are also people out there who get interest paid out to them every month or quarter – and this is a whole lot of folks who have got reinvestment risk to worry about.

    If you take that mouthful of cash and put it into a savings product or a bond or a deposit every time it comes in, falling interest rates can just bring the returns on those new investments right back down to earth. And that can add up big time over time – affecting the total amount that ends up in your account.

    Read Also: Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works

    What Kind of Investments Have Got Reinvestment Risk 

    The thing is reinvestment risk isn’t just a concern for a few specific investments. It’s a pretty broad problem across all the fixed income products out there.

    • Fixed Deposits: When one of these things matures, you’re going to have to decide whether to renew it on renewal terms that probably won’t be as good as the ones you lost.
    • Government Securities: Whenever those periodic interest payments come in, you’ve got to reinvest them – which is great unless market rates have dropped since you first bought the security.
    • Corporate Bonds and NCDs: Whenever you get an interest payment and need to reinvest – falling rates are your worst nightmare. And callable bonds actually give you a whole extra worry – they allow the issuer to pull the plug on you sooner rather than later and force you to put the cash back into a riskier situation.
    • Debt Mutual Funds: Fund managers have got to reinvest the maturing bonds in new ones they bought at a lower rate – which means the whole portfolio just isn’t going to be as profitable as it used to be.
    • Short-term Debt Investments: The quicker a fund comes and goes, the quicker you need to rebuy – and that gives you a lot less time to take advantage of the higher interest rates.

    Reinvestment Risk vs Interest-Rate Risk

    These risks are related, but they affect investors differently.

    FeatureReinvestment RiskInterest-Rate Risk
    MeaningRisk of earning less on reinvested cash flowsRisk of changes in an investment’s market value due to interest-rate movements
    Common triggerFalling interest ratesRising interest rates can reduce existing bond prices
    Main impactLower future income or realised returnsPotential loss if an investment is sold at a lower price
    ExampleRenewing an FD at a lower rateSelling an existing bond after its market price falls

    For example, falling rates can make it harder to reinvest interest at attractive returns. Rising rates, on the other hand, can reduce the market price of existing fixed-rate bonds.

    Both risks matter when planning a fixed-income portfolio.

    How to Reduce Reinvestment Risk

    1. Building a Bond or FD Ladder

    Investors can’t eliminate reinvestment risk entirely in most fixed-income portfolios, but they can minimize their exposure with a few practical strategies.

    1. Use a Bond or FD Ladder

    Instead of putting all your money into one maturity, consider dividing it across different tenures. Say you have a chunk of cash to invest, you could spread it across a one-year, two-year, three-year, and four-year deposit. Once each investment matures, you can then reinvest part of the cash at the rates available at the time – a good way to avoid having to reinvest the lot at a single low-rate period.

    2. Think About Cumulative Fixed Deposits

    Cumulative fixed deposits are a great option when it comes to reinvestment risk. Instead of doling out interest payments regularly, they reinvest them straight back into the deposit. This means the interest compounds and is then paid out when the deposit matures. It reduces the need to find new investments for each interest payment, but of course you’ll still need to reinvest when the deposit finally ends.

    3. Match Investments to Your Needs

    When choosing investment maturities, consider when you’ll actually need the cash. If you have a big expense looming in two years, consider investing in something that matures around that time – it’ll mean you can have the cash when you need it and avoid the hassle of pre-emptive withdrawals. Just be mindful of premature withdrawal rules and other risks that might apply.

    4. Spread Your Risk with Diversification

    Diversifying your investments across different products with different maturities and income structures can also help to reduce the impact of reinvestment risk. By spreading your money around, you’re not so reliant on a single reinvestment date or interest-rate environment. However, be aware that products like equities and equity mutual funds are not a direct substitute for fixed-income investments: they carry their own market risks and won’t necessarily guarantee returns.

    5. Don’t Forget to Review the Bond’s Terms and Yield

    When you’re looking at a bond, review all the terms and conditions, including the coupon rate, maturity, call provisions and yield-to-maturity (YTM). YTM can be a useful measure, but remember it’s just an estimate and not a guaranteed return – actual returns can vary depending on how your investments perform.

    Read Also: What is Buy Now Pay Later (BNPL)? How It Works & Benefits

    Conclusion

    Reinvestment risk is real, and it can reduce your future income if you have to reinvest at lower rates. This is especially true for investors who rely on fixed deposits, bonds, and other fixed-income products. Understanding the impact of interest rates on reinvestment can help you make better decisions, though.

    You can reduce the impact of reinvestment risk by using strategies like maturity laddering, cumulative deposits, diversification and goal-based planning. And before investing, always compare the product’s terms, liquidity, maturity and risks.

    Disclaimer: This article is for educational purposes only and is not investment advice. Investment returns and interest rates can change. Review the terms and risks of each product before investing.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Parabolic Move in Stocks: Meaning, Causes & Risks
    2Federal Reserve Interest Rate: Impact on India & Markets
    3What Is ASM in Share Market?
    4Tracking Stock: Meaning, Examples, Pros & Cons
    5What is the Magic Formula Investing?

    Frequently Asked Questions (FAQs)

    1. What does reinvestment actually mean?

      Reinvestment just means putting money you’ve received from an investment – usually interest or maturity proceeds – straight back into another investment.

    2. When is reinvestment risk usually a problem?

      Reinvestment risk tends to be a bigger problem when interest rates fall and you have to reinvest interest payments or maturing investments at lower rates.

    3. Do zero-coupon bonds keep you safe from reinvestment risk?

      Zero-coupon bonds don’t make the usual payments, so there just aren’t any coupons to keep earning and then having to reinvest. Still, when the bond eventually matures, you’re gonna need to find somewhere to put the principal back to work. And let’s be honest, the value can actually drop or rise before it’s all said and done.

    4. Can reinvestment risk just disappear?

      Getting rid of it completely is a pretty tall order , especially when you’ve got investments that kick out cash flows that you have to keep ploughing into the market. That being said, things like laddering – lining up your maturities to match your goals – and thinking about options like matching maturities to goals and or considering cumulative options can seriously help with managing it.

  • What is the Power of Compounding?

    What is the Power of Compounding?

    This is exactly what the power of compounding is. It is a simple concept that helps your money grow faster.

    We will look at a compounding effect example later, but simply put, it is like planting a tree. This magic is useful for beginners, young earners, salaried people, and anyone who wants to build savings slowly.

    In India, knowing how to make your money work for you is very important. Let us see an example of compounding and understand how it works.

    Compounding Effect Meaning

    What exactly does the compounding effect mean? In simple words, it is earning interest on your interest. When you put money in a bank, you earn interest.

    Simple interest means you only get interest on the money you first put in. But compound interest is different. Here, the interest you earn gets added to your main amount. We will check some compounding examples soon to make this clear.

    In the next year, you earn interest on both your starting money and the past interest.

    Here is the formula:

    A = P (1 + r/n)^(nt)

    Let’s explain the formula:

    • A is the final amount you get at the end.
    • P is the starting money you put in.
    • r is the annual interest rate in decimals.
    • n is how many times the interest is added every year.
    • t is the total number of years you stay invested.

    Simple Interest vs Compound Interest

    FeatureSimple InterestCompound Interest
    Interest calculated onOnly the starting amountStarting amount plus past interest
    Growth over timeSlow and steadyFaster, like a snowball
    Best used forShort term needsLong term wealth building

    Understanding this difference is important before you begin saving and investing. This tells you why your money will become more if you leave it alone.

    What is the actual power of compounding and how does it work in real life?

    The real magic depends on three main things. First is the amount you invest. Putting in more money naturally gives you a bigger base to grow.

    Second is the rate of return. A higher interest rate means your money grows faster.

    Third is the time you stay invested. Time is the true secret behind this process. The longer you wait, the more fruitful your result will be.

    Another key part is how often your returns are added. Banks or funds can add returns yearly, quarterly, or monthly. If it gets added every month, your cash will grow more quickly than if they added it every year. It is just like rolling a snowball down a snowy hill. At first, it gathers a little snow. As it keeps rolling, it picks up snow much faster.

    Compounding Examples in Simple Rupees

    Let us look at some compounding examples to make this easy to understand. We will assume a fixed return rate of 12% per year just for these calculations.

    Please remember these are only examples and not promised returns. Your actual returns will depend on where you invest.

    Suppose you invest Rs 10,000 one time and leave it.

    • After 10 years: It grows to around Rs 31,058.
    • After 20 years: It grows to around Rs 96,462.
    • After 30 years: It reaches nearly Rs 2,99,599.

    Did you notice how the jump from year 20 to year 30 was massive? This happens because your interest is earning its own interest.

    What if you invest a small amount every month? Let us say you start a monthly Systematic Investment Plan (SIP) of Rs 5,000 at the same 12% expected return.

    Time InvestedTotal Money Put InExpected Final Amount
    10 YearsRs 6,00,000Rs 11,61,695
    20 YearsRs 12,00,000Rs 49,95,739
    30 YearsRs 18,00,000Rs 1,76,49,569

    It proves that little consistent efforts can generate a huge amount of money over time.

    Read Also: What is the Magic Formula Investing?

    Start Early vs Start Late: A Compounding Effect Example

    Let us try to make it easier by taking a real-life scenario. Just imagine two friends, Rahul and Amit. Both are interested in saving for their future.

    Rahul starts saving Rs 5,000 per month from his 25th year. He continues to do so until he is 55 years old. For a period of 30 years, he saves. Given the assumption that the annual rate of interest is 10%, Rahul’s savings of Rs 18 lakhs will amount to Rs 1.13 crores.

    Amit begins only after he turns 35 years old. He makes the same investment of Rs 5,000 per month up until the age of 55. So he continues investing for a period of 20 years. The same return on investment of 10% makes his initial investment of Rs 12 lakhs become around Rs 38 lakhs.

    Rahul has almost three times more money than Amit. He did not do anything special. He just started earlier and gave his money more time to compound.

    Key Factors That Make Compounding Work

    If you want to use this power well, you need to understand the main rules.

    • Time: This is the most vital principle. More time means more money. Let your investments mature for many years.
    • Rate of Return: It is very important to get an appropriate rate of return. Small changes in the percentage make a lot of difference.
    • Regular Investing: You do not need big amounts. Small amounts put in every single month are very effective.
    • Reinvesting Your Returns: Never take out the interest. Let the profit make more profit for you.
    • How Often Returns Are Added: Monthly compounding gives better results than yearly compounding.
    • Patience: The growth looks very slow in the first few years. Do not lose hope because the big jumps happen much later.

    Where Can You See Compounding in India?

    India offers many options to grow your money safely and steadily.

    • Fixed Deposit (FD): Fixed Deposits are provided by banks wherein the interest earned is automatically compounded. Presently, the rate of interest for FDs lies around 2.50% to 8.25%.
    • Public Provident Fund (PPF): It is a very safe government scheme. The current PPF interest rate is 7.1% per year. The interest is tax-free and gets added back every year.
    • Employees Provident Fund (EPF): For salaried workers, a part of your salary goes here. The current EPF interest rate is 8.25% per year
    • Mutual Fund SIPs: You can invest in the stock market through SIPs. It does not give you guaranteed returns, but the returns tend to be higher than the rate of inflation.
    • Stocks: Investing in high-quality stocks could lead to an increase in your wealth because of their price rise.
    • National Pension System (NPS): It is a Government-sponsored pension program. Its investment is done in both stocks and secure bonds.

    Note: Kindly confirm the latest rate from the RBI, Ministry of Finance, EPFO, and/or AMFI before you invest. Also remember that market-linked returns are not fixed or guaranteed. This information is for learning only and is not financial advice. Investments are subject to market risks. 

    How To Use the Power of Compounding

    Using this power is very easy if you follow basic steps.

    • Begin Early: Do not postpone your saving until the right time comes or you get a hefty pay. Start saving what little you can now.
    • Choose How Much to Invest Every Month: You may choose to invest Rs 500 or perhaps even as much as Rs 5,000. What really counts is that you invest every month.
    • Selecting the Correct Choice Depending on Your Objective: Choose FDs or PPF in case your objective is safety.
    • Reinvestment Over Withdrawal: Whenever there are returns on your investments, ensure that these are reinvested into the same accounts.
    • Increase the Amount Gradually: As your salary grows, increase the amount you invest each month as well.
    • Review Your Goals Once or Twice Per Year: Make sure you review your goals regularly, but without reviewing your finances each and every day.

    After starting your investments, you would want to handle your finances in an easy manner. This can be achieved using applications like Pocketful, which will help you track your investments.

    One way to get this information is using the Rule of 72. The rule is very simple; all you have to do is divide the number 72 by the interest rate. In case you wish to double your investment at an 8% interest rate, 72 divided by 8 equals 9. This means it will take 9 years to double your money.

    Common Mistakes People Make With Compounding

    Many people miss out on great wealth because of simple errors.

    • Late Start: Delaying investment until you earn more reduces your end value. The time lost cannot be recovered.
    • Early Money Withdrawal: If you use your money for purchasing a phone or a car, then your chain of compounding is broken.
    • Not Taking Inflation, Taxes and Fees into Account: Your profits should always outdo inflation. Be wary of any hidden costs
    • Getting Rich Fast: Beware of any schemes that say you will get rich overnight, in just a few months because it is a lie.
    • Stopping Your SIP When Markets Fall: Markets go up and down. Stopping your investments in fear ruins the long-term plan.
    • Letting Compounding Work Against You: High-interest loans and credit card dues compound against you. Clear them first.

    Simple Tips To Make the Most of Compounding

    • Objectives: Know what your objectives for savings are. The objectives might be buying a home, retiring with ease, and providing education to your kids.
    • Get Automatic: Have an investment mandate to automatically invest your money straight from your bank account on payday.
    • First, Maintain an Emergency Reserve: Maintain savings equivalent to 3 to 6 months’ worth of your expenses in your regular savings or liquid fund. In this way, you won’t touch your long-term investments.
    • Remain Long-Term Investors: The big returns will be realized in the latter part of your investment process.
    • Track your progress without being affected by every movement in the market: You cannot expect the market to be good all the time. Just concentrate on the bigger picture.
    • Use Only Approved Platforms: Make sure the platform and the broker through which you will invest your money are registered with SEBI.

    Read Also: What is Fund of Funds (FOF)?

    Conclusion

    The generation of wealth is not dependent on mathematical knowledge or embarking on risky endeavours. The generation of wealth depends on discipline, forethought, and patience. That’s all it takes.

    To explore and track your investments in one place, download Pocketful, offering users zero brokerage on delivery trades and an easy-to-use platform designed for both beginners and experienced investors. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1How to Calculate Stock Volatility in Excel?
    2Nifty Options Profit & Loss Formula – Calculate P&L
    3What is a Basis Point (BPS)?
    4Explainer on Liquidity Ratios: Types, Importance, and Formula
    5Best SWP for Monthly Income in India

    Frequently Asked Questions (FAQs)

    1. What is the rule of 72?

      It is a simple math trick in which one needs to divide 72 by his or her annual interest rate. The quotient shows the number of years required to double one’s money.

    2. Is compound interest better than simple interest?

      Yes, compound interest is always better for building up money. Simple interest increases only the principal sum of money, whereas compound interest multiplies the principal sum as well as the previously earned interest.

    3. How can a beginner start compounding?

      One can open a PPF account or even start investing a small amount of money each month into a mutual fund through an SIP. The key point is to start as soon as possible, even investing as low as Rs 500 per month.

    4. Does compounding work in the share market?

      Yes, compounding works great with the stock market. As a company grows, its shares become more expensive. Besides, one gets dividends and buys additional shares.

    5. What happens if I stop investing for a few years?

      If you stop adding new money, your existing money will still compound. However, you will miss out on the extra growth that regular investing brings.

  • What Is IDCW in Mutual Funds and How Does It Work?

    What Is IDCW in Mutual Funds and How Does It Work?

    IDCW in mutual funds stands for Income Distribution cum Capital Withdrawal. It is an option in which a mutual fund may distribute part of its available surplus to investors rather than keep the entire amount invested.

    But this is not an additional return on your investment. So, what is this exactly? Well, read this guide to understand the details here.

    What Is IDCW in Mutual Funds?

    Income Distribution cum Capital Withdrawal (IDCW) is an option that allows the fund house to distribute a part of the scheme’s distributable surplus among eligible investors.

    The money can come from income and realised gains generated by the scheme. Regulations also recognise that an IDCW distribution can include amounts from the investor’s capital through the equalisation reserve.

    In simpler words, it is a distribution from the value already available within the mutual fund scheme.

    IDCW was earlier known as the dividend option. SEBI changed the terminology to Income Distribution cum Capital Withdrawal from April 2021 for clarity. 

    How Does IDCW Work in Mutual Funds?

    When you invest in an IDCW option, you hold units of the mutual fund just like any other investor. The difference appears when the fund declares a distribution.

    Here is how the process generally works.

    1. You Invest in the IDCW Option

    You first select the IDCW option while investing in a mutual fund scheme that provides this facility.

    IDCW is available separately from the growth option. Some schemes may also provide different frequencies or sub-options depending on their structure.

    2. The Scheme Generates Income and Gains

    The mutual fund invests the collected money according to its investment objective. Depending on the type of fund, it may earn interest, dividends or gains from selling securities.

    A portion of the amount available for distribution may then form the scheme’s distributable surplus.

    3. The Fund Declares IDCW

    The AMC or trustees may declare IDCW when sufficient distributable surplus is available.

    However, declaring IDCW is not compulsory. The amount and frequency are also not guaranteed. A scheme offering a monthly or quarterly IDCW option does not mean investors are assured of receiving a payment every month or quarter.

    4. Eligible Investors Receive the Distribution

    Investors whose names appear in the records on the applicable record date become eligible for the declared IDCW.

    Depending on the option selected, the amount may be paid to the investor or reinvested in additional units.

    5. The NAV Adjusts After IDCW

    Once IDCW is distributed, money moves out of the scheme. As a result, the NAV of the IDCW option declines. This is mainly by the amount that you distribute.

    For example, suppose you hold 1,000 units of a mutual fund. Now, lets say these are with an NAV of ₹50.

    The value of your investment is:

    1,000 × ₹50 = ₹50,000

    Now, assume the fund declares IDCW of ₹2 per unit. You become eligible for a distribution of ₹2,000 before applicable tax deductions.

    Ignoring market movement and other adjustments, the NAV may reduce from ₹50 to around ₹48 after the distribution.

    Your investment has not suddenly generated an additional ₹2,000 outside the fund. A part of the value held within the scheme has simply been distributed to you.

    Why Did SEBI Rename Dividend to IDCW in Mutual Funds?

    In April 2021, the Securities and Exchange Board of India (SEBI) renamed the dividend option in mutual funds to Income Distribution cum Capital Withdrawal (IDCW) to make the payout mechanism clearer for investors. 

    The term “dividend” often created the impression that mutual funds offered additional income, similar to dividends paid by companies. 

    However, mutual fund payouts can come from both investment gains and investors’ capital. The new name aims to improve transparency and help investors understand that payouts are not guaranteed and can reduce the fund’s Net Asset Value (NAV).

    What Are the Types of IDCW Options?

    Mutual fund schemes commonly provide IDCW through payout and reinvestment options. You can understand the same as follows:

    1. IDCW Payout

    Under the payout option, the declared amount is paid to your registered bank account after applicable tax deduction.

    For example, say you hold 2,000 units. Now, the scheme declares an IDCW of ₹1 per unit, the gross distribution would be ₹2,000.

    The NAV of the IDCW option reduces after the distribution.

    2. IDCW Reinvestment

    Under the reinvestment option, you do not receive the declared amount in your bank account. Instead, the amount remaining after applicable TDS is used to purchase additional units of the same IDCW option.

    Your number of units therefore, increases, although the NAV adjusts after the IDCW declaration. SEBI scheme documents specifically provide for both payout and reinvestment facilities under IDCW.

    This option may appear similar to the growth option because the money stays invested. However, the mechanism and the taxation differ. IDCW is considered distributed before being reinvested and may therefore have tax consequences.

    Read Also: What is R-Squared in Mutual Funds?

    What Is the Difference Between IDCW and Growth Options?

    Both options invest in the same underlying mutual fund portfolio. The main difference lies in what happens to the income and gains generated within the scheme.

    ParticularsIDCW OptionGrowth Option
    DistributionMay distribute money when IDCW is declaredNo IDCW distribution
    NAVFalls when IDCW is distributedReturns remain reflected in NAV
    CompoundingDistributions reduce the amount remaining investedReturns remain invested and can compound
    Cash flowCan provide payouts when declaredMoney is generally accessed by redeeming units
    Tax timingIDCW is taxable when distributedCapital gains tax generally arises on redemption
    PredictabilityIDCW amount and frequency are not guaranteedNo periodic distribution is promised
    Suitable forInvestors who require distributions and understand the implicationsInvestors focused mainly on wealth accumulation

    Under the growth option, income attributable to the units remains invested in the scheme and is reflected in its NAV. Under IDCW, some of that value may be distributed instead.

    Suppose two investors each invest ₹1 lakh in separate options of the same scheme. If the IDCW option distributes money regularly, less capital may remain invested under that option.

    The growth investor receives no such distribution. The entire investment remains exposed to subsequent market movements and has a greater opportunity to compound over a long period.

    This does not automatically make one option right for every investor. Your choice should depend on why you are investing and whether you actually need distributions from the investment.

    How Is IDCW Taxed?

    IDCW received from mutual funds is taxable in the hands of the investor. To understand the taxation better, here are the key points that you should know:

    • IDCW is not tax-free.
    • TDS at 10% may apply under Section 194K. This is applicable if IDCW income exceeds ₹10,000 in a financial year.
    • TDS is only a tax deduction, not the final tax liability.
    • Your final tax depends on your total taxable income and applicable slab rate.
    • If excess TDS is deducted, you can claim it later.
    • Tax rules can differ for non-resident investors.

    What Are the Benefits and Limitations of IDCW?

    IDCW can be useful in specific situations. But just like any other investment option, there are certain pros and cons of investing in the same. These are as follows:

    Benefits of IDCW

    • You may receive money without manually redeeming mutual fund units.
    • It can provide occasional cash flow when the scheme declares IDCW.
    • The payout can be used for expenses or other financial requirements.
    • Investors can also choose reinvestment where the scheme provides the option.

    Limitations of IDCW

    • The amount of IDCW is not guaranteed.
    • The frequency of distributions is also not assured.
    • NAV reduces after the distribution.
    • IDCW is taxable in the hands of the investor.
    • Frequent distributions can leave less money invested for long-term compounding.
    • A high IDCW payout does not necessarily mean that a fund has delivered a high overall return.

    All these are some of the key points that you should consider when you are willing to invest. 

    Who Should Consider the IDCW Option?

    IDCW may suit investors who:

    • Prefer occasional payouts from their mutual fund investment.
    • Understand that IDCW payments are not fixed or guaranteed.
    • Do not want to redeem units manually each time they need money.
    • Are comfortable with the tax impact of IDCW.
    • Are not relying only on long-term compounding.

    If you need a more predictable withdrawal amount, you can also compare IDCW with a Systematic Withdrawal Plan. This can help you build a strong portfolio that will generate good returns.

    Read Also: What is Stamp Duty on Mutual Fund Investments?

    Conclusion

    IDCW in mutual funds allows a scheme to distribute part of its available surplus to investors. This is not an additional return but is again a benefit that you get. But before investing, it is important that you compare all the options in front of you to make the right call and avoid investing in funds that do not meet your expectations.

    This is where a platform like Pocketful can help you with the insights. Get all the details and support you need to start investing and build your portfolio better.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Mutual Funds vs Segregated Funds: Key Differences
    2Survivorship Bias and Mutual Fund Performance
    3What is Flow of Funds (FOF)?
    4How to Start Systematic Investment Plan (SIP) in Index Funds?
    5Indexation in Mutual Funds: Meaning, Calculation & Importance

    Frequently Asked Questions (FAQs)

    1. What Is the Full Form of IDCW?

      IDCW stands for Income Distribution cum Capital Withdrawal. It is the term used for the option earlier known as the dividend option in mutual funds.

    2. Is IDCW Paid Every Month?

      Not necessarily. Some schemes may offer monthly IDCW options, but the actual distribution depends on the availability of distributable surplus and the fund’s decision. A monthly option does not guarantee monthly income.

    3. Does NAV Fall After IDCW?

      Yes. When IDCW is distributed, the NAV of the relevant option generally falls by the amount distributed per unit, subject to applicable adjustments and market movement.

    4. Is IDCW Tax-Free?

      No. IDCW is taxable in the hands of the investor. For an individual investor, it is generally added to taxable income and taxed at the applicable income tax slab rate.

    5. Which Is Better, IDCW or Growth?

      There is no single option suitable for everyone. Growth may be more suitable for investors focused on long-term compounding, while IDCW may be considered by investors who prefer distributions and understand the associated tax and NAV impact.

  • Continuous Compounding: Formula, Example & Benefits

    Continuous Compounding: Formula, Example & Benefits

    Have you ever wondered how your investments grow over time? This is generally because of compounding, but there is another concept known as continuous compounding, in which interest is added continuously rather than at fixed intervals.

    In today’s blog post, we will give you an overview of continuous compounding, its formula through an example, along with the frequency of compounding. 

    What is Continuous Compounding?

    Continuous compounding is a method of calculating the return on an investment where the interest earned by an investment is added back to the principal amount or initial capital continuously, and the interest amount also earns returns. Because of continuous compounding, the investment keeps growing every moment as the interest earned also increases, contributing to further growth. There are various frequencies of compounding depending upon the type of investment, ranging from monthly to yearly. Continuous compounding is commonly used in mathematics and investment calculations. 

    Formula to Calculate Continuous Compounding

    The formula to calculate continuous compounding is as follows:

    A = Pe^rt

    Where:

    A = Final Amount

    P = Principal Amount or Initial Investment

    e = Mathematical constant (2.71828)

    r = Interest rate

    t = Time period

    Also, to calculate the interest part only, one can use the formula mentioned below:

    Interest = A – P

    Example of Continuous Compounding

    Let’s understand continuous compounding through an example:

    Mr A invested 1,00,000 INR in a bank fixed deposit at an annual interest rate of 7% for two years. Now, let’s calculate continuous compounding using the formula.

    A = Pe^rt

    Putting the values as below:

    Initial Investment (P) = 1,00,000

    Annual Interest (r) = 7%

    Time (t) = 2 Years

    A = 1,00,000 * e^(0.07*2)

    A = 1,00,000 * 2.71828^(0.14)

    The final amount will be 1,15,027 INR

    And the interest part will be calculated as 

    A – P

    = 1,15,027 – 1,00,000

    = 15,027 INR

    This means Mr A will earn interest of INR 15,027 over 2 years at a rate of 7% p.a.

    How Does Continuous Compounding Work

    The working of continuous compounding is explained in the following steps:

    1. Starting with Investment: The first step is to invest a certain amount of money that is known as principal. The interest is calculated on this principal amount.
    2. Interest Rate: The interest rate decides how quickly your investment can grow over time. The higher the interest rate, the higher the growth.
    3. Investment Duration: This defines the period for which you wish to keep your money invested. The period is generally in years.
    4. Calculating Growth: The growth in the investment is calculated using the compounding formula. This will help in calculating the final amount of the investment.
    5. Calculating the Interest: The calculation of interest will be completed only after calculating the final value of the investment by subtracting it from the principal amount. This will help us in calculating the growth part.

    Read Also: What is the Magic Formula Investing?

    Difference Between Simple Interest and Compound Interest

    The key differences between simple interest and compound interest are as follows:

    ParticularsSimple InterestCompound Interest
    OverviewIt is calculated only on the principal amount.Compound interest is calculated on the principal amount and accumulated interest.
    Interest AmountThe amount of interest earned is fixed for the entire duration of the investment.The interest amount increases over time.
    FormulaThe formula to calculate simple interest is P*R*T/100Compound interest is calculated using the formula A = P(1+r)^t
    Growth RateIt has a constant growth rate.The principal grows faster over time due to compounding.
    UsageThis is used in calculating a few loans and interest.This is mostly used in savings accounts, deposits, investments, etc.

    Frequency of Compounding

    The frequency of compounding refers to how often the interest earned on an investment is added to the principal amount. The growth depends on the frequency at which interest is compounded, assuming other factors remain the same.

    Types of Frequency of Compounding

    The different types of compounding frequency are as follows:

    FrequencyOverviewCompounding Frequency Per Year
    AnnualInterest is added once a year1
    Semi-AnnualInterest is added every six months.2
    QuarterlyInterest is added every three months4
    MonthlyInterest is added every month12
    DailyInterest is added every day365 (Generally)
    ContinuousContinuous compounding of interestInfinite

    Importance of Continuous Compounding

    The key importance of continuous compounding is as follows:

    1. Higher Growth: Through continuous compounding, one can accumulate interest continuously. For the same principal, annual interest rate, and investment period, it generates a slightly higher final amount than daily, monthly, quarterly, or annual compounding.
    2. Investment Valuation: The concept of continuous compounding is widely used in financial mathematics and helps in calculating the future value of an investment. This helps an investor in analysing how an investment can grow over a specific period.
    3. Comparison of Different Interest Rates: Continuous compounding can be used to compare interest rates with continuous compounding. It helps an investor compare different rates with different compounding frequencies.
    4. Calculation of Present Value: Continuous compounding is also used when calculating the present value of money which one can receive in future by discounting future cash flows to their current value using continuous compounding rates.

    Conclusion

    On a concluding note, continuous compounding is a mode of calculating interest where money grows continuously over time. Unlike simple interest, continuous compounding affects returns accumulated continuously. This may offer a slightly higher return than other compounding frequencies when the principal, annual interest rate, and investment period are the same. It is widely used in financial calculations. Having a better understanding of continuous compounding helps an investor in taking informed decisions; however, it is advisable to consult your investment advisor before making any investment. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1How to Calculate Stock Volatility in Excel?
    2Nifty Options Profit & Loss Formula – Calculate P&L
    3What is a Basis Point (BPS)?
    4Explainer on Liquidity Ratios: Types, Importance, and Formula
    5Best SWP for Monthly Income in India

    Frequently Asked Questions (FAQs)

    1. What is the meaning of continuous compounding?

      Continuous compounding is a method of calculating interest in those investments where interest is assumed to be accumulated continuously rather than being added at fixed intervals. This allows us to calculate how an investment grows over time when interest is invested regularly.

    2. Is there any difference between compound interest and continuous compounding?

      Compound interest is a concept of earning interest both on the principal and accumulated interest; therefore, it is a broader concept. Whereas continuous compounding is a specific method in which interest is accumulated continuously for an indefinite period.

    3. Where is continuous compounding used?

      Continuous compounding is used in financial mathematics, interest rate calculations, and calculating the present value of money under continuous compounding rates.

    4. What is the formula to calculate continuous compounding?

      The formula to calculate continuous compounding is A = Pe^rt. Where A refers to the final amount, P is the principal amount or initial value, e is commonly known as the mathematical constant 2.71828, r is the annual interest rate in decimal form, and t refers to the time period.

    5. How does continuous compounding work?

      In continuous compounding, the interest accumulates continuously. It contributes to the growth of the investment throughout the investment period. 

  • JIO Platforms IPO Day 1: Check Latest GMP, Steps to Verify Status

    JIO Platforms IPO Day 1: Check Latest GMP, Steps to Verify Status

    Jio Platforms, one of India’s leading digital and telecommunications companies, is launching an initial public offering (IPO) to raise up to ₹30,213 crore. The issue opens for subscription on October 21, 2026, and will close on October 23, 2026, with a price band fixed at ₹1,065 to ₹1,119 per share. Since the IPO is entirely a fresh issue of shares, the company will receive the proceeds from the offering, primarily to repay debt of its subsidiary, Reliance Jio Infocomm, and for general corporate purposes. The shares are proposed to be listed on the Bombay Stock Exchange (BSE) and the National Stock Exchange (NSE) on October 28, 2026, subject to allotment and necessary regulatory approvals. 

    JIO Platforms IPO Day 1 Subscription Status

    On Day 1, Jio PlatformsIPO witnessed a good investor turnout, closing with an overall subscription of 3 times, QIB led the Subscription 9 times, The Non-Institutional Investors 1.56 times subscription Overall, indicating good participation. Among Non-Institutional Investors (NII), the bNII (above ₹10 lakh) portion was subscribed 1.70 times, while the sNII (less than ₹10 lakh) segment saw 1.28 times subscription. Shareholders category subscribed by 1.36. The Retail Individual Investors (RII) category was subscribed 0.70 reflecting healthy retail interest, the issue garnered 29,10,261 applications, with total bids amounting to approximately 66,426.70 crore, showcasing confidence across investor categories in the company’s growth potential.

    Investor CategorySubscription (x)
    Qualified Institutional Buyers (QIB)9.00
    Non-Institutional Investors (NII)1.56
    bNII (above ₹10 lakh)1.70
    sNII (less than ₹10 lakh)1.28
    Retail Individual Investors (RII)0.70
    Employees1.28
    Shareholders 1.36
    Total Subscriptions3.01

    Total Applications: 29,10,261

    Total Bid Amount (₹ Crores): 66,426.70

    How to Check Jio Platforms IPO Allotment Status?

    Jio Platforms IPO allotment can be easily checked online in two ways: from the Registrar’s website and from the NSE & BSE website. This IPO will be listed on NSE & BSE exchanges, so the allotment status will be available to all investors on both platforms.

    Method 1: Registrar’s website (KFin Technologies Limited)

    The most reliable way is to check allotment from the KFin Technologies Limited website.

    How to do:

    • Visit KFin Technologies Limited official website
    • Select “Jio Platforms” from the IPO list
    • Enter your details PAN number, Application number, or DP/Client ID
    • Click on Submit
    • You will see the allotment status on the screen.

    Method 2: Check from NSE & BSE website

    If there is more traffic on the registrar’s website, allotment status can also be checked from NSE & BSE.

    How to do:

    • Visit NSE or BSE official website
    • Select ‘Equity’ segment
    • Select “JIO Platforms” from the IPO list
    • Enter PAN number and Application number
    • Click on Search

    Objective of the JIO Platforms IPO

    For Jio Platforms IPO, the issue is a 100% fresh issue of shares, with no Offer for Sale (OFS) component. Therefore, the company will receive the entire proceeds from the IPO, amounting to approximately ₹30,213 crore at the upper end of the price band. The funds are intended to be used primarily to repay certain borrowings of its subsidiary, Reliance Jio Infocomm, and for general corporate purposes. 

    Use of IPO ProceedsAmount (₹ Cr)
    Proceeds to be received by Jio Platforms through Fresh Issue  ₹30,213

    Jio Platforms IPO – Day 1 Update

    The grey market premium (GMP) of the Jio stands at ₹113 as of October 21, 2026 (Day 1). Considering the upper end of the price band at ₹1,119 per share, the estimated listing price is around ₹1,377, reflecting a potential gain of approximately 23.06% per share in the grey market.

    DateGMPEst. Listing Price Gain 
    21-10-2026 (Day 1)₹258₹1,37723.06%

    Disclaimer: The above GMP (Grey Market Premium) is just unofficial market information, which is not officially confirmed. These figures are shared for informational purposes only and investment decisions based on these should be based on the investor’s own research and discretion. We do not conduct, recommend or support any kind of transaction in the grey market.

    Jio Platforms IPO IPO – Key Details

    ParticularsDetails
    IPO Opening DateOctober 21, 2026
    IPO Closing DateOctober 23, 2026
    Issue Price Band₹1,065 to ₹1,119 per share
    Total Issue Size27,00,000 shares (aggregating up to ₹30,213 Cr)
    Listing PlatformNSE & BSE
    RegistrarKFin Technologies Limited 
    DRHPJio Platforms

    Important Dates for Jio Platforms IPO Allotment

    EventDate
    Tentative AllotmentSeptember 26, 2026
    Refunds InitiationSeptember 26, 2026
    Credit of Shares to DematSeptember 26, 2026
    Listing Date September 28, 2026

    Overview Of Jio Platforms IPO 

    Jio Platforms Limited is one of India’s leading digital services and telecommunications companies, providing connectivity, digital applications, cloud services, and technology-driven solutions to consumers and businesses. Through Reliance Jio Infocomm, the company has built an extensive telecommunications network, serving millions of subscribers across India. Jio has established a strong position in the country’s digital ecosystem, supported by its telecom infrastructure, expanding 5G network, home broadband services, and growing enterprise solutions. With increasing demand for digital connectivity, artificial intelligence, cloud computing, and connected services, Jio Platforms remains a key player in India’s evolving digital economy. 

    Frequently Asked Questions (FAQs)

    1. What is the opening and closing date of the Jio Platforms IPO ?

      Jio Platforms IPO  will open on 21 October 2026 and will close on 23 October 2026.

    2. What is the price band of the Jio Platforms IPO ?

      Its price band is fixed from ₹1,065 to ₹1,119 per share.

    3. What is the GMP (Grey Market Premium) of the Jio Platforms IPO today?

      The GMP on 21 October 2026 is ₹258, which leads to a possible listing price of ₹1,377.

    4. What is the total issue size of the Jio Platforms IPO?

      The total issue size of the Jio Platforms IPO is ₹30,213 crore, The IPO is entirely a fresh issue

    5. What is the expected listing date of  the Jio Platforms IPO?

      This IPO is expected to be listed on NSE & BSE on September 28, 2026.
  • Short Selling vs Put Options: Key Differences

    Short Selling vs Put Options: Key Differences

    Short selling and buying put options can both be used when you expect a stock price to fall. However, both differ in terms of position, risk, and money involved.

    Short selling gives direct exposure to the stock price. A put option comes with a premium, strike price, and expiry date. Read this guide to know about both and understand the difference.

    What Is Short Selling?

    Short selling is the process of selling shares that you do not currently own, with the belief that their price will fall. You sell the shares at the current market price and buy them back later at a lower price, aiming to earn a profit from the difference.

    Example: Say a stock trades at ₹1,000. You short sell 100 shares. The price falls to ₹900, and you buy the shares back. The difference is ₹100 per share.

    Your gross profit is ₹100 × 100 shares = ₹10,000.

    Now, say price reaches ₹1,100. Now, you lose ₹10,000 when you buy back.

    This makes the risk uneven. A share can only fall to zero, so the profit has a limit. But a share can keep going up with no limit. So the loss can keep growing.

    In India, SEBI allows short selling of eligible securities. 

    How Does Short Selling Work?

    A short position has three stages.

    1. You sell the shares at the market price. In some cases the shares have to be borrowed first.
    2. You buy the shares back later. This is called covering the short.
    3. The difference between your selling price and buying price is your profit or loss, after charges.

    In an intraday short trade, you sell and buy back in the same session. If you want to carry a cash market short position to the next day, the securities must be available for settlement.

    Brokers also have to collect margin. NSE says at least 20% upfront margin is needed in the capital market segment in lieu of VaR and ELM. Other margins can also apply.

    What Is a Put Option?

    A put option is a derivative contract. Its value depends on an underlying stock or index. This is a contract. So, when you buy a put, you have the right to sell. This is at the underlying at a fixed strike price. The contract has an expiry date. You pay a premium to get this right.

    Example: Say a stock trades at ₹1,000. You buy a ₹1,000 strike put.  The same is set for a premium of ₹35.

    If the stock falls sharply, the put can gain value. If the fall does not come before expiry, the put can lose value or expire worthless.

    A put buyer can lose only the premium paid, plus trading charges. This is one of the biggest differences between short selling and put options.

    Short Selling vs Put Options: Key Differences

    To understand the difference, here are the details:

    FactorShort SellingBuying Put Options
    Market viewBearish.Bearish.
    PositionSell shares first.Buy a put contract.
    Maximum lossTheoretically unlimited.Usually limited to the premium paid.
    Maximum profitLimited, as the stock cannot fall below zero.Limited by the strike price and the premium.
    ExpiryA cash short trade has no option expiry.The contract has a fixed expiry.
    Time decayNo direct effect.Can reduce the option value.
    VolatilityMainly the stock movement matters.Implied volatility affects the premium.
    CapitalMargin and settlement needed.Premium paid upfront.
    Price movement neededA fall in price helps directly.The fall must also cover the premium.
    Hedging usePossible, but less simple.Commonly used to hedge a fall.

    Put options is on selected stocks and indices that are traded in the Indian derivatives market. The contracts, strike prices, lot sizes, and expiry cycles are all based on the exchange. 

    Short Selling vs Put Options Example

    Take a stock at ₹1,000. Now, think that trader A shorts the stock at ₹1,000. Trader B buys a ₹1,000 strike put and pays a ₹35 premium.

    The following table gives you a bit insight on the same:

    Stock Price LaterShort Selling, Per SharePut at Expiry, Per Unit
    ₹850₹150 profit.₹115 profit.
    ₹950₹50 profit.₹15 profit.
    ₹980₹20 profit.₹15 loss.
    ₹1,000No profit or loss.₹35 loss.
    ₹1,100₹100 loss.₹35 loss.

    Look at the ₹980 row. The view was right, because the stock fell. The short seller made money. The put buyer still lost, because the fall was not enough to cover the premium.

    Look at the ₹1,100 row. The short seller is down ₹100 per share. The put buyer loses only the ₹35 premium in this example.

    Read Also: GIFT Nifty vs Nifty 50: Key Differences

    How Does Risk Differ?

    Risk is the most important point in a short stock vs put option.

    A short seller is exposed as the price goes up. If a ₹1,000 stock goes to ₹1,500, the loss is ₹500 per share. If it goes higher, the loss grows more.

    A short squeeze makes this worse. Traders who want to close their shorts have to buy the stock. That adds more buying, and the price goes up further.

    A put buyer knows the premium before entering the trade. Even if the stock moves hard the other way, the loss stops at the premium.

    But this has a cost. The premium works against the buyer if the move does not come in time.

    How Do Time and Volatility Affect the Two Strategies?

    Short selling follows the stock more directly. If the stock falls ₹20, the short position gains about ₹20 per share before charges.

    A put option has more parts. Its price can change because of:

    • Movement in the underlying stock.
    • Time left before expiry.
    • Implied volatility.
    • The strike price.
    • Interest rates and other pricing inputs.

    Time decay matters more as expiry gets closer as this is the time when the option slowly loses its time value when other factors remain the same.

    Implied volatility also moves the premium. When volatility rises, option prices can go up. When it falls, they can go down.

    So trading puts is harder than just guessing if a stock will go up or down.

    When May Traders Consider Short Selling?

    Short selling may suit traders who expect a fairly direct fall in a share price, and who understand the margin and settlement rules.

    It may be considered when:

    • Bearish view is mainly about price direction.
    • Traders want direct exposure to the fall.
    • The trader can watch the position closely.
    • There is enough capital for the margins.
    • The trader understands the risk of a sudden rise.

    Risk management is very important here, because the loss has no fixed upper limit.

    When May Traders Consider Buying Put Options?

    A put option may be useful when a trader expects a decline over a certain period and wants to limit the maximum loss before entering.

    Puts are also used to hedge. An investor who holds shares can buy a put to gain protection against a decline without selling the shares.

    A put may be considered when:

    • The maximum loss on the trade needs to be fixed.
    • The trader expects a big enough fall before expiry.
    • The trader understands premiums and time decay.
    • An existing position needs protection.

    The premium matters. A costly put needs a bigger fall before the buyer reaches breakeven.

    Short Selling vs Put Options: Which Is Better?

    There is no one answer for every bearish trade.

    Short selling has a cleaner link to the stock price. A ₹50 fall gives about ₹50 profit per share before costs. But a sudden rally can cause large losses.

    A put has a fixed risk. But the trade also has to deal with expiry, premium, volatility and time decay. Being right on direction may not be enough.

    So your choice depends on the size and timing of the fall you expect, the capital you have, and how much you can afford to lose.

    Read Also: Gold ETF vs Gold Mutual Fund: Differences and Similarities

    Conclusion

    Short selling and put options both give bearish exposure. But the payoff is very different. Short selling follows the stock price directly. If not managed well, you can end up in huge losses. On the other hand, the put places a limit on the losses. This is why you need to evaluate both well before you select one.

    This is where you can gain support from Pocketful. Get all the insights and support you need to start investing better and ensure your portfolio grows well. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Mutual Fund vs ETF. Are They Same Or Different?
    2Difference Between Trading and Investing
    3ETF vs Index Fund: Key Differences You Must Know
    4Gold BeES vs Silver BeES: Which is the Better Investment?
    5Digital Gold vs Gold ETF: Which is Better?

    Frequently Asked Questions (FAQs)

    1. Is buying a put safer than short selling? 

      A put buyer has a fixed maximum loss equal to the premium paid. Short selling can lead to much larger losses if the stock price rises sharply.

    2. Can you lose money on a put even when the stock falls? 

      Yes. The stock may not fall enough to cover the premium. Time decay and changes in implied volatility can also affect the option value.

    3. What is the maximum profit in short selling? 

      The maximum profit comes if the share price falls to zero. So the profit is limited by the price at which the shares were first sold.

    4. Can put options be used for hedging? 

      Yes. Investors can buy puts on stocks or market exposure to reduce the effect of a fall. How well it works depends on the strike, the expiry and the premium.

    5. Do put buyers need margin? 

      A put buyer usually pays the option premium upfront. NSE needs upfront margins in the F&O segment. But the margin depends on the position and the exchange rules.

  • What Is Flow of Funds (FOF)? Meaning, Example & Importance

    What Is Flow of Funds (FOF)? Meaning, Example & Importance

    Ask most people where their money goes after they pay a SIP instalment or park cash in a fixed deposit, and you’ll get a blank look. The money does not vanish, of course. A bank lends it to a business, an insurer puts it into government bonds, a mutual fund buys shares. Economists track this entire movement through something called the flow of funds. 

    In India, the Reserve Bank of India compiles these accounts every year, and they show who is saving, who is borrowing, and which financial products connect the two. 

    In today’s blog, we will find out what is the flow of funds, how it actually works, and why you should understand the concept.

    What is Flow of Funds (FOF)?

    Flow of funds is a series of accounts that provide information about financial transactions among the various sectors of an economy over a period of time, typically a financial year. It provides answers to a fundamental question: how much money did each sector raise, and what did they do with it?

    Not all individual and company accounts are included. They group them. In the Indian context, you will find households, non-financial companies, financial companies (banks, insurers, mutual funds and NBFCs), the government (Centre and states combined) and the rest of the world.

    Some of these sectors have surplus money, which means that they make more money than they spend. Some spend more than they make and are in debt. The accounts record both of them, and they also record the instruments in between, such as deposits, loans, bonds, shares, insurance policies, and provident funds. 

    How Does Flow of Funds Work?

    Every sector earns income, spends part of it, and saves what remains. That saving can go towards real assets, such as a house, a machine, or a factory, or it can be lent out as a financial asset.

    1. The Net Lender/The Net Borrower

    If a sector saves more than it invests in real assets, it ends up as a net lender. If it needs more than it saves, it becomes a net borrower. Indian households have long been the biggest net lenders since they save more. Their money lies in bank deposits, LIC policies, EPF and PPF accounts, post office schemes, mutual funds, etc. Companies and the government are on the other side. They usually need more funds than they generate, for expansion in one case and for public spending in the other.

    2. The Intermediaries

    Then come the intermediaries. A bank accepts deposits from lakhs of households and turns them into loans for businesses, home buyers and, indirectly, the government through bond purchases. A mutual fund gathers small investments and spreads them across equity and debt. Insurers invest premiums, much of it in government securities. None of these institutions produces much of their own money. Their job is to move it from people who have it to people who can use it.

    3. The Foreign Sector

    When the economy borrows more than it saves, the difference comes from overseas through foreign direct investment, portfolio flows, or external commercial borrowings. That’s why the rest of the world has its own column in the accounts.

    One rule holds everything together. A financial asset for one party is always a liability for another. Your fixed deposit is your asset and the bank’s liability. A government bond held by an insurer is the insurer’s asset and the government’s liability. Because of this, if you add up the net lending and borrowing of every sector, including the foreign one, the answer is zero.

    What is a Flow of Funds Matrix

    It is a comprehensive macroeconomic accounting grid that tracks the movement of financial resources and credit across sectors of an economy. 

    It acts like a nationwide spreadsheet where everyone’s spending and income connect and balance out. 

    Columns represent economic sectors that include 

    • Households (including NPOs)
    • Non-financial companies (Commercial businesses)
    • Financial Institutions (banks, AMCs, insurance companies) 
    • Central & State Government 
    • Rest of the World

    Rows represent Financial Instruments and Transactions (tools through which money moves): 

    Currency and bank deposits are the simplest. Loans, government securities, corporate bonds, equity shares, mutual fund units, life insurance funds, and small savings follow. Each one shows up as a separate line in the matrix.

    Sources & Uses of Funds:

    Furthermore, each sector’s column is subdivided into Sources of Funds and Uses of Funds.  Sources are what a sector raises, through borrowing, issuing shares or accepting deposits. Uses are where the money goes: lending, buying securities, holding deposits and so on.

    At last comes the net financial position, which is the gap between uses and sources. It tells you in one number whether a sector is feeding money into the system or drawing it out.

    Read Also: What is Fund of Funds (FOF)?

    Example of Flow of Funds (FOF)

    Below is an easy tabular illustration for better understanding 

    SectorFunds raised (sources)Funds invested or lent (uses)Net position
    Households10110100
    Non-financial corporations12060-60
    General government5010-40
    Financial corporations2002000

    Take households first, since their numbers are the easiest to follow. 

    Over the year, they put ₹110 crore into bank deposits, insurance premiums, EPF and PPF, mutual funds and shares. However, they borrowed only ₹10 crore through home and personal loans. 

    Subtract one from the other, and you get a surplus of ₹100 crore. In simple terms, households had that much more to lend than they needed for themselves.

    Let us come to companies now. They raised ₹120 crore through bank loans, bonds and fresh equity, but they did not spend all of it. ₹60 crore stayed in financial form, in deposits or invested elsewhere. The difference is ₹60 crore, which is their net borrowing. 

    The government is in a similar position, though its numbers are smaller. It raised ₹50 crore through market borrowings and small savings schemes and held back ₹10 crore in financial assets. That leaves it ₹40 crore short.

    Banks, insurers and mutual funds lie in between all of this. They collected ₹200 crore from deposits, premiums and fund units, and they gave away the same ₹200 crore as loans and securities. Nothing was left, so their net position is zero. 

    Now put the net figures side by side. Households are ahead by ₹100 crore, while companies and the government are behind by ₹60 crore and ₹40 crore, which adds up to the same ₹100 crore. The two sides cancel out exactly, as they always must. 

    In a real RBI table, you would also see the foreign sector, and the balancing would depend on overseas capital coming in or going out. 

    Importance of Flow of Funds

    • Helps in understanding the economic activity: It helps to find how funds move between different sectors of the economy, and helps analysts understand how savings are used for investments and how borrowing supports economic activities.
    • Tracks Savings & Investments: FOF helps in explaining how savings from households and other sectors are moved into financial assets, business investments, and lending, which gives a clear picture of how available financial resources are allocated across the economy. 
    • Helios Financial Planning: Businesses can use fund flow analysis to understand their sources of funds and how they are being used, and this helps them plan future expenses, manage financial resources, and identify funding needs. 

    Conclusion 

    Flow of funds provides clear, structured insight into the movement of money in India. It demonstrates who is saving, who is borrowing, which products link them up, and the matrix provides a view of all of this in one place. The key rule, one’s asset is always another’s liability, ensures consistency in the entire system.

    If you are handling any kind of money, from being a student to an analyst to an investor, it’s worth spending some time with these accounts. 

    They describe the importance of saving in a household, the role of the banks and mutual funds in channelling the savings, and the role of government borrowing and foreign inflows. Understanding the framework makes RBI publications easier to read, and your savings and investments appear to be a small but real part of a very big picture.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4How to Start SIP Using E-Mandate?
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What is Flow of Funds?

      It tracks the flow of funds among the various sectors in an economy, including the households, the business sector, the banking sector, and the government sector. 

    2. What is the main purpose of the flow of funds?

      The primary objective is to get an understanding of where the funds are being spent, how they are being spent, and how they flow through each sector. 

    3. What are the major elements of FOF?

      The major elements are sources of funds, uses of funds, and financial transactions among sectors.

    4. Explain the difference between Flow of Funds and Cash Flow.

      While flow of funds measures the movement of financial resources and financial transactions, cash flow measures the movement of cash and cash equivalents.

    5. Who uses the Flow of Funds analysis? 

      Economists, financial analysts, businesses, government authorities, and investors use FOF to understand financial trends.

  • Open Free Demat Account

    Join Pocketful Now

    You have successfully subscribed to the newsletter

    There was an error while trying to send your request. Please try again.

    Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.