Category: Mutual Funds

  • Types of Equity SIFs & How They Work

    Types of Equity SIFs & How They Work

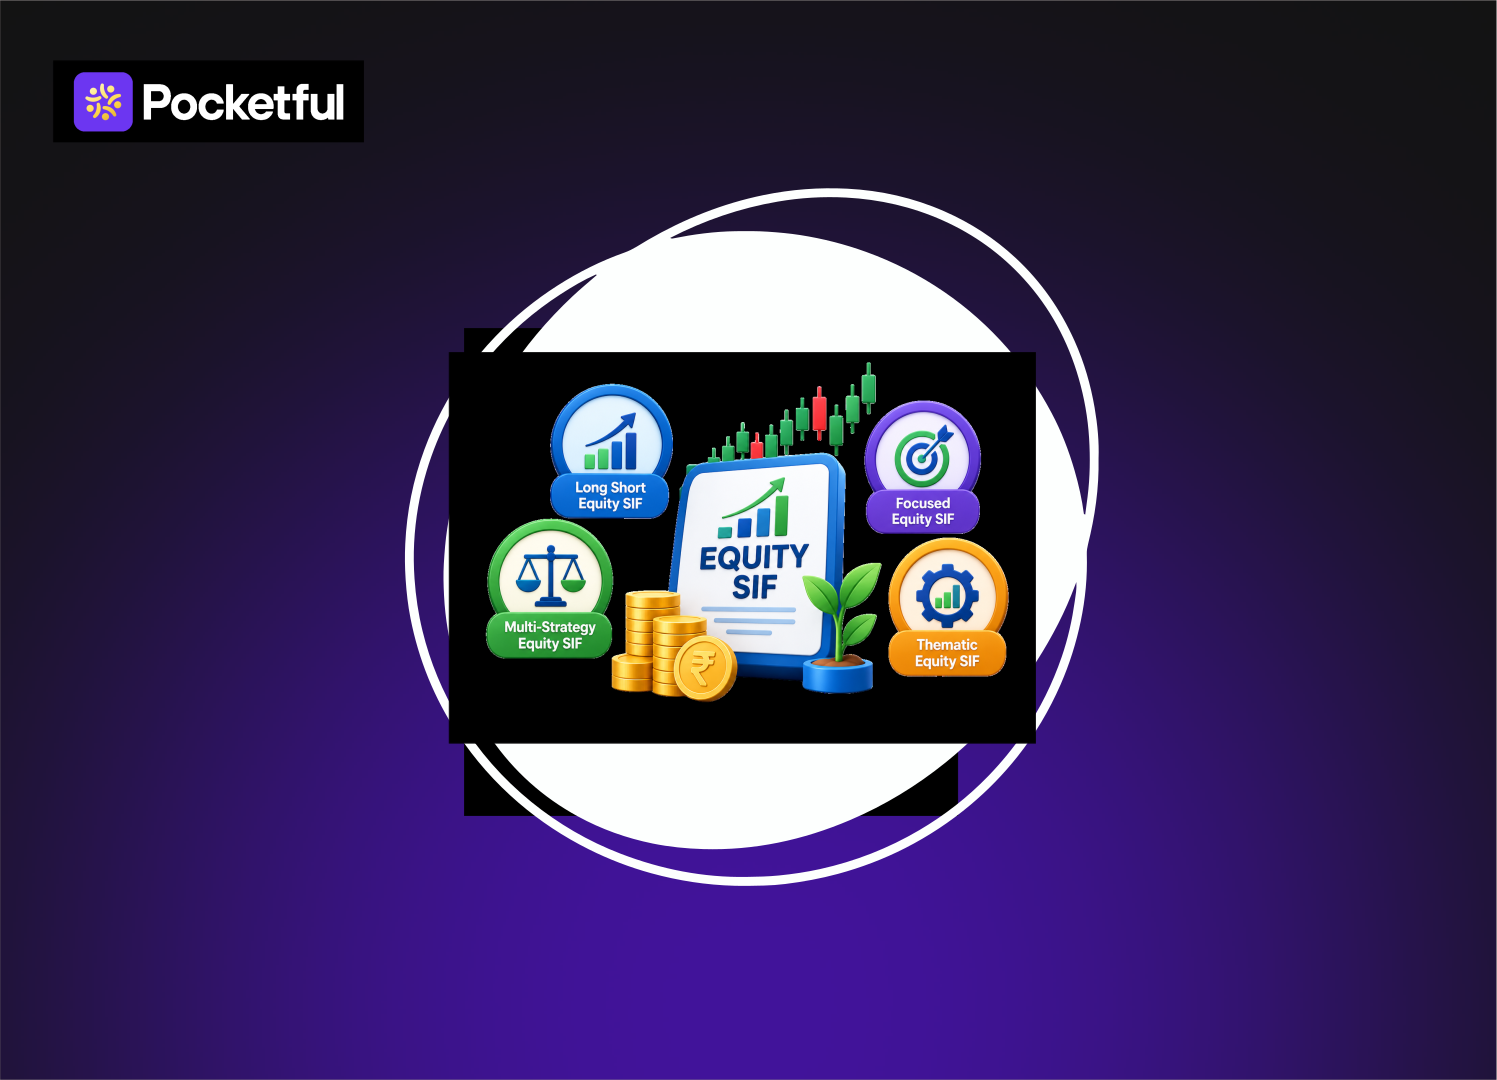
    An Equity SIF (Specialized Investment Fund) is an investment vehicle in India offering sophisticated strategies beyond standard mutual funds. While traditional funds follow a “long-only” approach, buying stocks and relying solely on rising markets, an Equity SIF uses a long-short strategy.

    Fund managers can buy promising stocks while short-selling weaker ones using derivatives. With this flexibility, investors get a safety net when the market starts to fall, allowing them to limit their losses or earn profit during a market downturn. Due to the complex, active management required, SEBI mandates a higher minimum ticket size of Rs.10 lakh. This threshold ensures participation is restricted to serious, informed investors seeking robust downside protection alongside equity upside.

    Why Equity SIFs Matter in Modern Investing

    The Indian stock market is growing fast. But it also sees sharp drops. This is why knowing the types of equity SIFs matters today. They give you a shield. Let us look at the Equity SIF Strategy Range Explained.

    • Long-Only Strategy: Some SIFs stick to a full exposure to equities without short positions. They buy shares of growing companies and hold them. However, they might focus very deeply on just a few stocks. This is different from regular funds that spread money across fifty or sixty companies.
    • Long-Short Strategy: This is where the magic happens. It combines long positions with permitted short exposure using derivatives. If the manager thinks a stock will fall, they take a short position. SEBI allows them to keep up to 25 percent of the fund in unhedged short positions.
    • Sector Rotation Strategy: Markets change seasons. Sometimes banks do well. Other times IT companies shine. A Sector Rotation Strategy uses a concentrated exposure that shifts across a limited number of sectors based on market outlook. If auto stocks look weak, the manager will exit entirely and move to pharma.

    How an Equity SIF Works

    Managing these funds is not a passive job. It requires constant attention. Here is an overview of the fund manager’s active strategy execution. They track daily market data, use complex models, and buy or sell futures and options to protect your capital.

    There are three main steps of Equity SIF investing:

    • Selecting the SIF Strategy: First, you look at your own goals. Then you pick a strategy that matches your style. You could choose a long-short fund or a sector rotation fund. Pocketful can be a great place to discover different investment options that suit your needs.
    • Making the Investment: Once you decide, you bring in the minimum required capital. For a SIF in India, SEBI says you need to invest at least Rs.10 lakh. This money is then pooled with funds from other investors.
    • Ongoing Portfolio Monitoring and Adjustment: The fund manager takes over from here. They buy stocks they like, short the ones they hate, and keep adjusting the portfolio every day to manage risks.

    How to Evaluate an Equity SIF Before Investing

    Start by looking at the fund house and the manager’s past record. See if their investment style makes sense to you.

    Next, you must read the ISID. The Investment Strategy Information Document is like a rulebook for the fund. How the ISID affects your decision is huge. It tells you exactly what the manager can and cannot do. It shows the limits on short selling and sector focus.

    Let us see an example of a long vs short position within an Equity SIF. The manager buys shares of Tata Motors because sales are up. That is a long position. At the same time, they expect a rival car company to report bad earnings. So, they short sell the rival’s futures contract. If the rival’s stock falls, the fund makes a profit on that trade.

    Finally, you need a clear interpretation of the final choice. Does this fund add value to your existing portfolio? If you already have normal mutual funds, an Equity SIF can give you that extra edge.

    Raed Also: SIF Regulations in India – SEBI Rules, Eligibility & Investment Limits

    Types of Equity SIFs in India

    SEBI has allowed a few interesting categories under the new rules. Let us look at a list of common strategy categories you can find in the market today.

    • Equity Long-Short Fund: This is the most popular type. It keeps at least 80 percent of the money in equities. The manager takes normal buy positions. But they can also take up to 25 percent in short positions using derivatives.
    • Equity Ex-Top 100 Long-Short Fund: This fund ignores the biggest 100 companies in India. It focuses only on mid-cap and small-cap stocks. At least 65 percent of the money goes into these smaller companies. It is riskier but can offer fast growth.
    • Sector Rotation Fund: This fund picks a maximum of four sectors at any time. If the manager feels banking and tech are the only good spaces right now, they will put all the money there.

    These are just a few examples. There are other equity-oriented strategies permitted under SEBI’s SIF framework as well. The market keeps bringing new ideas.

    Risks to Know Before Investing in Equity SIFs

    Every investment carries some risk. You should be fully aware of them before writing that big cheque.

    • Strategy Risk: Sometimes the manager’s core idea fails. If they bet big on the pharma sector and it crashes, the fund will suffer heavy losses.
    • Derivative and Hedging Risk: Derivatives are complex tools. If the market moves in a very unexpected way, hedging can backfire. A wrong short call can eat into the profits of the good stocks.
    • Liquidity Risk: You cannot withdraw your money from a SIF as easily as a regular mutual fund. Some SIFs only allow you to take money out once a week or once a month.
    • Market Timing Risk: Since managers actively jump in and out of sectors, they have to time the market right. If they exit a stock too early or enter too late, the returns will drop.
    • Expense Ratio Impact: Active management costs money. SIFs charge a higher fee than normal mutual funds. This high expense ratio will reduce your final take-home returns. 

    Advantages of Investing in Equity SIFs

    Despite the risks, these funds bring a lot of unique benefits to the table.

    • Flexibility Across Market Conditions: Normal funds just suffer when the Nifty falls. SIFs can adjust. They can short sell and protect your capital during bad market phases.
    • Professional and Active Management: You get access to highly skilled managers. They use advanced data and tools to run the portfolio. You do not have to worry about reading balance sheets yourself.
    • Access to Hedge Fund-Like Strategies: Earlier, only very rich people with crores of rupees could use such strategies via AIFs. Now, a 10 lakh ticket size gives you access to the same smart tools.
    • Diversification Within Your Equity Portfolio: If you already own normal mutual funds, a SIF adds a new flavour. It behaves differently from your regular funds. This brings true balance to your wealth.
    • No Need to Time the Market Yourself: The manager does the heavy lifting. They decide when to sit on cash and when to go aggressive. You just sit back and track your progress. You can even use the Pocketful platform to keep an eye on your overall financial health.

    Limitations of Equity SIFs

    Let us look at the other side of the coin. These funds are not perfect for everyone.

    • High Minimum Investment Requirement: The Rs.10 lakh entry barrier is a big hurdle. Not every retail investor has that kind of money to spare for a single fund.
    • Performance Depends Heavily on Fund Manager Skill: A regular index fund runs on autopilot. But a SIF is highly dependent on the human manager. If the manager makes bad calls, the fund will bleed money.
    • Higher Expense Ratio Than Regular Mutual Funds: You are paying for active work and complex trades. The high fees can pinch you over a long period.
    • Not Ideal for Very Short-Term Goals: You should not put your emergency fund here. SIFs need time to play out their strategies. They are built for patient investors.
    • Returns Are Never Guaranteed: Even with all the hedging and short selling, the market is the ultimate boss. You can still lose money if the market faces a massive unexpected shock. 

    Read Also: Top Specialized Investment Funds (SIFs) in India

    Common Mistakes Investors Make

    People often jump into new products without doing their homework. Avoid these common traps.

    • Treating Equity SIFs Like Regular Mutual Funds: They are completely different animals. Do not expect them to mirror the Nifty index. They will have their own unique return cycles.
    • Ignoring the Fund’s Strategy Document (ISID): Many people just look at the brochure and invest. You must read the ISID. It tells you exactly how much risk the manager is allowed to take.
    • Chasing Past Returns Blindly: A sector rotation fund might have given huge returns last year. That does not mean it will do the same this year. The market cycle might have changed.
    • Not Checking the Expense Ratio and Costs: High fees can quietly eat your profits. Always compare the costs before you sign the papers. 

    Conclusion

    In the end, Equity SIFs offer a very interesting middle ground. They sit perfectly between basic mutual funds and ultra-rich AIFs. They bring smart strategies like short selling to serious retail investors. However, they demand a good amount of capital and patience. Make sure you understand the strategy document clearly before investing. Always remember that good investing is about picking the right tool for your specific goal. We hope this guide gave you a clear picture of how these funds operate in India.

    To explore and track your investments in one place, download Pocketful, offering users zero brokerage on delivery trades and an easy-to-use platform designed for both beginners and experienced investors.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Mutual Fund vs PMS: Which is Better?
    210+ Best Investment Plan for Monthly Income in India
    3Hybrid Mutual Funds – Definition, Types and Taxation
    4What is an Open-Ended Mutual Fund & How to Invest in it?
    5Mutual Fund vs ETF. Are They Same Or Different?

    Frequently Asked Questions (FAQs)

    1. What is the minimum amount needed to invest in an Equity SIF in India?

      As per SEBI rules, you need a minimum investment of Rs.10 lakh to enter any SIF strategy. This keeps it separate from regular retail mutual funds.

    2. Can an Equity SIF completely protect my money from a market crash?

      No investment can offer complete protection. However, the short selling and hedging strategies in a SIF can help reduce your losses compared to a regular long-only mutual fund.

    3. Are Equity SIFs taxed differently than regular equity mutual funds?

      No. Equity-oriented SIFs are generally taxed just like regular equity mutual funds. Long-term capital gains above Rs.1.25 lakh are taxed at 12.5 percent, and short-term gains are taxed at 20 percent.

    4. Is it mandatory to have a Demat account for investing in SIFs?

      Just like standard mutual funds, you typically buy units of the SIF. While a Demat account helps you track everything in one place easily, check with the specific AMC for their exact holding format.

    5. How do I know which strategy the SIF is using?

      You can find all the details in the ISID. The Investment Strategy Information Document clearly explains if the fund uses long-short trades, sector rotation, or other specific methods.
  • Dynamic Bond Funds: Meaning, Benefits, Risks & Taxation

    Dynamic Bond Funds: Meaning, Benefits, Risks & Taxation

    Most fixed-income investing in India still starts and ends with fixed deposits or plain debt mutual funds. But when interest rates keep moving around, funds locked into a fixed duration often struggle to keep returns steady. That’s the gap dynamic bond funds are built to fill. Once you understand what these funds actually are, how they operate, and where they fit, they become a lot easier to use in your own debt portfolio.

    What Exactly Is a Dynamic Bond Fund?

    It’s an open-ended debt mutual fund with no fixed rule on maturity or duration. The fund manager keeps shifting between short-term and long-term debt, depending on where they think interest rates are headed next.

    With a static debt fund, you’re locked into one duration range no matter what the market does. A dynamic bond fund removes that guesswork entirely; the manager handles the timing and allocation calls actively, on your behalf.

    Dynamic Bond Funds vs Regular Debt Funds

    Here’s where the real difference shows up.

    Regular debt funds have to follow strict SEBI rules. A short-duration fund, for instance, must always keep its average portfolio duration between one and three years rates can do whatever they want, but the fund still has to stay in that band.

    A dynamic bond fund has none of that constraint. If the manager expects rates to rise, they can cut duration down to just a few months. If a rate cut looks likely, they can stretch duration out to seven or eight years.

    Feature Dynamic Bond FundsRegular Debt Funds
    Duration Mandate Flexible (No minimum or maximum limit) Fixed as per category rules
    Manager RoleHighly active duration management Mostly passive or constrained
    Ideal Horizon 3 to 5 yearsMatches specific fund duration

    Why Active Management Actually Helps Here

    The inverse relationship between bond prices and interest rates is the fundamental rule. Bond prices decline when interest rates are on the rise, with the longest-term bonds witnessing the sharpest fall. On the other hand, the lowering of rates brings an increase in bond prices, which is the way one realizes the gains.

    An active fund manager tracks all of this for you. You don’t have to sit and follow RBI policy meetings or global rate cues yourself; that’s the whole point of handing it over to someone whose job is exactly that.

    Why Fixed Income Requires Dynamic Bond Funds

    The typical Indian rate cycles cycle through three major phases, and dynamic bond funds can modify their duration accordingly for each of them.

    • Shorter duration period (raising interest rates): The bond manager shortens the fund’s duration by shifting into low-duration fixed-income instruments at the same time the central bank or RBI is hiking its policy interest rates to curb inflation, and as a result, the price of bonds will drop.
    • Medium duration phase (uncertain environment): When rates plateau, or signals are mixed, the fund holds a balanced mix of short-term and medium-term bonds, mainly to keep collecting steady interest income.
    • High duration phase (rates falling): When the RBI cuts rates to push growth, long-term bond prices rally. The manager shifts heavily into long-duration bonds here, aiming to capture both the price gain and the regular coupon.

    How the Fund Manager Actually Runs This

    Three things really drive how a dynamic bond fund operates.

    • Reading interest rate trends. The manager watches retail inflation (CPI), RBI’s policy stance, liquidity in the system, the trade deficit, and crude oil prices; all of this feeds into predicting where rates are headed before the move actually happens.
    • Adjusting portfolio duration. Once a trend is clear, the manager changes the weighted average duration of the fund, switching between money market instruments and long-dated government securities to either capture gains or limit losses.
    • Balancing credit quality. Even while chasing duration calls, the manager needs to keep credit risk low. Most dynamic bond fund managers stick to high-grade papers, so the fund’s performance comes mainly from interest rate calls, not from taking a gamble on shaky corporate debt.

    Read Also: What is a Fixed Income Mutual Fund?

    How to Evaluate One Before You Invest

    Don’t pick a dynamic bond fund just because it’s had a good run recently. Go through this instead:

    • Check historical duration movements and pull up the fund’s old fact sheets and see if the manager actually changed duration during past rate cycles, or just left it static and got lucky.
    • Review credit quality by checking how much sits in AAA-rated paper and G-Secs versus AA or lower-rated corporate bonds.
    • Compare expense ratios against similar schemes. In debt funds, even a small difference in cost eats directly into your net returns.
    • A real example of a duration shift: Say you’re looking at Fund A. In 2022, when global rates were climbing, Fund A cut its average maturity from 7 years down to just 1.2 years – protecting its NAV through that period. Later, once rate cuts looked likely, the same fund pushed maturity back up to 6.5 years. That’s active duration management doing exactly what it’s meant to do.

    What’s Actually Inside These Funds

    A dynamic bond fund typically holds a mix of:

    • Government Securities (G-Secs) are issued by the Central Government, zero credit risk, highly liquid, useful for quick duration shifts.
    • State Development Loans (SDLs) are issued by state governments, offer slightly better yields than central G-Secs, still near-sovereign in safety.
    • Corporate bonds are non-convertible debentures from private companies or PSUs.
    • Certificates of Deposit (CDs) are short-term instruments issued by banks for liquidity needs.
    • Commercial Papers (CPs) are unsecured short-term debt from large corporates, used for working capital.
    • Money market instruments are Treasury Bills and overnight repo papers, mainly for parking cash short-term.

    Risks Worth Knowing About

    These funds aren’t risk-free, so go in with eyes open.

    • Duration risk: If the manager gets the rate cycle wrong and extends duration right before rates rise, the NAV takes a hit.
    • Credit risk: If the fund holds corporate debt and that issuer gets downgraded or defaults, the portfolio value drops.
    • Liquidity risk: During serious market stress, selling long-term corporate bonds without a price cut can get difficult.
    • Market timing risk: The entire strategy rests on the manager’s judgment; a wrong call on RBI’s next move can hurt returns for a while.
    • Expense ratio impact: Active trading inside the fund tends to push costs higher than a passive debt fund.

    What Makes Them Worth Considering

    • Adapts to every rate environment: Rising, falling, or flat, the fund’s duration shifts to match.
    • Professional management: Someone with actual expertise is tracking macro data and the yield curve, not you.
    • Diversification: Spread across government debt, state loans, and top-rated corporate papers.
    • Better risk-adjusted returns, potentially: Capital gains during falling-rate periods can lift overall performance.
    • No market timing needed on your end: You’re not repeatedly entering and exiting based on rate news yourself.

    Where They Fall Short

    • Heavy reliance on the manager’s judgment: a wrong macro call can leave the fund underperforming even a simple short-duration fund.
    • Higher expense ratios: frequent rebalancing costs more than a passive, index-style debt fund.
    • Not built for short time frames: with duration swinging around, these aren’t right for an emergency fund or any goal under 1–2 years.
    • Returns aren’t guaranteed: unlike an FD, the NAV moves with the market every single day.

    Mistakes Investors Often Make

    1. Treating it like a fixed deposit: assuming your capital and returns are guaranteed, when they’re really not; market volatility can and will show up. 
    2. Ignoring credit quality: chasing past yield numbers without checking whether the fund is holding lower-rated corporate debt to get there.
    3. Chasing past returns: a great historical run usually reflects one duration call that worked well in that cycle; it won’t necessarily repeat.
    4. Skipping the expense ratio check: high recurring costs quietly eat into your yield over time, so this comparison matters.

    Keeping Track of It All

    Once you’re holding a few different debt funds, keeping tabs on allocation and rate exposure across your whole portfolio needs a decent tracking setup. Clear visibility on where your money sits helps you stay disciplined, no matter which way the market cycle turns.

    To track your investments in one place, you can use Pocketful; it offers zero brokerage on delivery trades and a clean interface built for both first-time and experienced investors. It makes it easy to manage your mutual funds, check how diversified your portfolio actually is, and stay on top of market movements from one screen.

    Read Also: Best Long-Term Bond Funds in India

    Conclusion

    Dynamic bond funds give fixed-income investors a flexible way to ride out changing interest rate cycles, without having to manually manage duration themselves. There’s manager risk involved, and some short-term volatility to expect, but their ability to adapt as the economy shifts makes them a solid piece of a well-built debt portfolio provided you’re investing with a 3 to 5-year horizon in mind.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Mutual Fund vs PMS: Which is Better?
    210+ Best Investment Plan for Monthly Income in India
    3Hybrid Mutual Funds – Definition, Types and Taxation
    4What is an Open-Ended Mutual Fund & How to Invest in it?
    5Mutual Fund vs ETF. Are They Same Or Different?

    Frequently Asked Questions (FAQs)

    1. What’s the ideal holding period for a dynamic bond fund?

      It is somewhere between 3 to 5 years. That gives the fund manager enough runway to actually play out a full interest rate cycle and capture the gains from it.

    2. How are these funds taxed in India?

      For investments made on or after April 1, 2023, gains from debt mutual funds (with equity exposure under 35%) get added to your total income and taxed as per your income tax slab.

    3. Are dynamic bond funds safer than equity funds?

      Generally, yes, debt carries lower volatility than equities. That said, dynamic bond funds are more volatile than liquid funds or short-duration debt funds, simply because their duration mandate is so flexible.

    4. Can a dynamic bond fund lose money?

      In the short term, yes. If rates rise fast and the fund is holding long-duration bonds at the time, their market value drops, which shows up as a temporary loss.

    5. How is a Gilt fund different from a Dynamic Bond fund?

      A Gilt fund only invests in government securities with zero credit risk, but a fixed duration mandate. A dynamic bond fund can hold both government and corporate paper, and change its duration freely based on the manager’s rate view.

  • Rupee Cost Averaging in SIP: Meaning, Benefits & Examples

    Rupee Cost Averaging in SIP: Meaning, Benefits & Examples

    Timing the market correctly when investing is not easy. That is why SIP is considered a simple method for regular investment. In this blog, we will understand the concept of ‘Rupee Cost Averaging’ in SIP, how it works, how to calculate it using a simple example, and its benefits and limitations. We will also explore what happens to an SIP when the market falls.

    What is Rupee Cost Averaging in SIP? 

    When you start a SIP, you invest a fixed amount every month, but the number of units you get varies. This is due to fluctuations in the NAV. You get more units when the NAV is low and fewer when it is high. Investing at different times in this manner results in an average purchase cost for your units.

    How Does Rupee Cost Averaging Work in SIP? 

    In a SIP, the investment amount is generally fixed, but the number of units acquired with each installment varies based on the NAV. This variation forms the basis of ‘Rupee Cost Averaging’ in SIPs.

    Step 1: A fixed amount is invested regularly.

    Suppose you have started an SIP of ₹2,000 per month. ₹2,000 will be invested in each installment, but the number of units you receive will depend on the fund’s NAV at that time.

    Step 2: Units are allocated based on the NAV.

    Calculating the units is easy.

    Units received = Investment amount ÷ NAV

    Check the table below for the SIP of ₹2,000: 

    MonthSIP AmountNAV Unit received
    1₹2,000₹20100
    2₹2,000₹10200
    3₹2,000₹2580
    4₹2,000₹16125
    Total₹8,000–505

    This example clearly shows that when the NAV dropped, the same ₹2,000 investment yielded more units, whereas when the NAV rose, the number of units acquired decreased. This illustrates the standard process of Rupee Cost Averaging in an SIP.

    Step 3: Reviewing total investment and units

    A total of ₹8,000 was invested over four months, resulting in the acquisition of 505 units. Now, to calculate the average purchase cost:

    • Average Cost = Total Investment ÷ Total Units
    • ₹8,000 ÷ 505 = Approximately ₹15.84 per unit

    Keep in mind that this represents only the average purchase cost. It does not guarantee a return exceeding ₹15.84 on the investment. The value of a mutual fund can fluctuate, rising or falling over time. AMFI also clarifies that Rupee Cost Averaging does not guarantee profits, nor does it protect against losses in a falling market.

    Why Does SIP Buy More Units When NAV Falls? 

    In an SIP, you invest a fixed amount each time; therefore, as the NAV fluctuates, the number of units purchased with that amount also changes.

    The investment amount remains constant

    Suppose you have a monthly SIP of ₹3,000. Regardless of whether the market NAV rises or falls, your fixed SIP amount remains ₹3,000.

    Units increase when the NAV drops

    If the NAV is ₹30 in a given month, ₹3,000 will buy you 100 units. However, if the NAV drops to ₹15, the same amount will buy you 200 units.

    Fewer units are purchased when the NAV rises

    Suppose the NAV rises to ₹40 the following month. Now, ₹3,000 will buy only 75 units. In other words, as the NAV increases, the number of units purchased through your SIP decreases.

    This results in an average purchase cost

    Since units are purchased at different NAVs across various SIP installments, an average cost per unit is established over the entire period. This process is known as ‘Rupee Cost Averaging’ in SIPs.

    More units do not guarantee a profit

    This is a crucial point. Receiving more units when the NAV is low can be beneficial if the fund’s value rises later. However, if the market continues to decline, the investment could still incur a loss. Therefore, Rupee Cost Averaging should not be viewed as a guarantee of profit.

    Read Also: Daily SIP vs Monthly SIP: Which SIP is Better?

    Benefits of Rupee Cost Averaging in SIP 

    With regular SIP investments, units are purchased at varying NAVs, reducing the need to constantly adjust your investment strategy based on market fluctuations.

    • Less worry about market timing: Determining the perfect time to invest in the market is often difficult. Since SIPs involve investing at fixed intervals, you do not need to time the market before each installment.
    • You may acquire more units during market downturns: When the NAV drops, your fixed SIP amount can purchase more units than usual. Consequently, when the NAV rises later, these additional units can positively impact the overall value of your investment.
    • Investment consistency is maintained: A practical benefit of SIPs is that the investment process continues systematically. This eliminates the need to make a fresh investment decision every month, making it easier to cultivate a consistent investment habit.
    • Decisions are less driven by emotions: Investors often tend to over-invest when the market rises and stop investing when it falls. Regular SIPs help minimize such frequent, emotion-driven decisions.
    • Investments are made at varying NAVs: Instead of deploying the entire amount at a single NAV, SIP installments are invested at different NAV levels. This ensures that your total purchase is not dependent on the market level of any single day.

    Does Rupee Cost Averaging Guarantee Profit? 

    No. Rupee Cost Averaging spreads out purchases over time, but it does not guarantee a profit.

    What happens if the market rises consistently?

    If the fund’s NAV increases over time, the value of previously purchased units may rise. However, with a rising NAV, each new SIP installment will fetch fewer units compared to earlier ones.

    What if the market fluctuates?

    With the NAV moving up and down, a different number of units is purchased with each installment. This results in an average purchase cost for the total investment, but the final return depends on the fund’s performance.

    What if the market falls continuously?

    Merely acquiring more units at a lower NAV is not an advantage in itself. If the NAV continues to fall, the current value of the investment could decrease. Therefore, Rupee Cost Averaging in SIPs cannot be considered a method that protects against losses.

    What is the bottom line?

    The advantage of Rupee Cost Averaging is that you do not have to rely on timing the market correctly every time. However, the ultimate profit or loss depends on the mutual fund you have chosen and its performance. 

    Rupee Cost Averaging vs Lump-Sum Investment 

    In both methods, money is invested in mutual funds, but the investment approach differs.

    Basis of comparisonSIP / Rupee Cost AveragingLump-Sum Investment
    Investment methodA fixed amount is invested regularly.A large amount is invested in a lump sum.
    Time to investOn different datesAt the same time
    Impact of NAVUnits are obtained at different NAVs.Units are allotted at the NAV of that time.
    Initial amountYou can start with even a small amount.A large amount of money is required at the beginning.
    Market TimingDependence on a single point in time is reduced.The initial phase of investment is more important.
    Investment behaviorRegular and systematicLump-sum and upfront

    A Practical Example: What Happens During a Market Correction? 

    You might feel like stopping your SIP when the market falls, but at such times, it is more important to understand how your next installment works. Let’s look at this with an example.

    Suppose an investor invests ₹5,000 per month via SIP, and the fund’s NAV changes as follows

    MonthNAV Unit purchased for ₹5,000
    1₹50100 
    2₹40125 
    3₹30166.67 
    4₹45111.11 

    When the NAV dropped to ₹30 in the third month, the same ₹5,000 investment yielded the highest number of units. The following month, as the NAV rose to ₹45, the number of units acquired decreased.

    It is important to understand one thing here: receiving more units when the market falls is beneficial only if the value of the investment appreciates in the future. Merely accumulating more units does not, in itself, constitute a profit.

    Therefore, during a market correction, one should not make a decision based solely on the fact that the NAV has fallen. It is also essential to consider the investment objective, the time horizon, and the suitability of the chosen fund.

    Read Also: What is Trigger SIP & How It Works?

    When Rupee Cost Averaging May Not Work as Expected 

    Investing via SIP every month is easy, but it does not eliminate market risk. It is best to understand a few things before investing.

    • Losses can occur if the market keeps falling: You get more units at a lower NAV, but if the NAV continues to fall, the value of your investment could decrease.
    • Recovery is not always quick: A fund’s NAV does not necessarily bounce back immediately after a drop; recovery can take a significant amount of time.
    • An SIP does not fix a wrong fund choice: If the chosen mutual fund does not align with your goals and risk profile, simply starting an SIP will not solve the problem.
    • Average cost is not the lowest price: Rupee Cost Averaging does not mean you have always purchased units at the lowest NAV; rather, it represents your average purchase cost derived from various installments.

    Common Mistakes Investors Make With SIP Rupee Cost Averaging

    It is important to understand Rupee Cost Averaging correctly; otherwise, a minor misunderstanding could impact your investment decisions.

    • Checking the portfolio daily: There is no need to panic over daily fluctuations in the NAV; this does not alter the SIP strategy.
    • Stopping the SIP when the market falls: Halting an SIP simply because the market has dropped can be a hasty decision. It is better to first assess whether the investment aligns with your goals and the chosen fund.
    • Choosing a fund based on a low NAV: A fund with an NAV of ₹10 is not necessarily cheaper or better than one with an NAV of ₹100. The NAV figure alone does not determine the quality of the fund.
    • Mistaking SIPs for guaranteed returns: An SIP is merely a method of investing. The returns depend on market performance; there is no fixed profit.

    Conclusion

    Rupee Cost Averaging in SIPs eliminates the need to time the market. Investing at varying NAVs results in an averaged purchase cost. However, this does not guarantee profits. The right fund, an appropriate time horizon, and regular investing are the keys to using SIPs wisely.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What is Rupee Cost Averaging in SIP?

      In an SIP, investing a fixed amount regularly results in purchasing units at varying NAVs, thereby creating an average purchase cost.

    2. Does Rupee Cost Averaging guarantee profit?

      No. It does not guarantee profit, and losses can occur if the market falls.

    3. Do I get more units when NAV falls?

      Yes. If the SIP amount remains constant, a lower NAV allows you to purchase more units for the same amount.

    4. Is SIP better than lump-sum investment?

      Not necessarily. Both have their own advantages. The right choice depends on your capital, financial goals, and investment situation.

    5. Can I stop my SIP during a market fall?

      It is not necessary to stop an SIP simply because the market is falling. The decision should be based on your financial goals and the chosen fund.

  • What is a Capital Protection Fund?

    What is a Capital Protection Fund?

    Many people want their investments to increase in value, but they also do not want to take any unnecessary risks with their hard-earned money. This is where Capital Protection Funds come into the picture. The funds are intended for investors who need to protect their capital and get returns.

    But the phrase ‘capital protection’ shouldn’t be interpreted as a promise that your investment won’t lose value. The degree of protection varies depending on the structure of the product and the investments involved. 

    It is important to know how they work, what risks are involved, and if they are suitable for your financial goals before you invest in them. Let us discover these points in detail today. 

    What are Capital Protection Funds?

    These are hybrid mutual funds with a goal to protect the investor’s original capital while still offering the potential for some additional return through limited equity exposure.

    It is not a savings account, neither a fixed deposit; instead, it is a mutual fund.

    Features of Capital Protection Fund 

    1. Hybrid asset allocation

    A Capital Protection Fund is not a pure debt fund, nor is it a pure equity fund. It works by diversifying the investment across both, with a large portion in debt instruments and a smaller portion in equities, so the fund can pursue safety and growth at the same time, rather than choosing one over the other.

    2. Close-ended structure

    Most of these funds are close-ended, which means new investments are only accepted during the initial offer period, that is, the NFO window. Once that window closes, investors cannot add fresh money, and existing investors generally need to stay invested until the scheme matures. Reason being capital protection strategy depends on holding the underlying debt instruments to maturity, so an open-ended structure would not really work here. This also affects the liquidity of the fund

    3. Oriented rather than guaranteed

    SEBI does not permit mutual funds to promise guaranteed returns, so these schemes are officially termed “Capital Protection Oriented Funds.” The word “oriented” matters as it signals that the fund is structured with the intention of protecting capital, not that protection is assured the way it would be with a bank deposit.

    4. Credit rating for capital protection

    Rating agencies such as CRISIL or ICRA often assign these funds a specific rating that reflects how likely the scheme is to preserve investor capital, based on the credit quality of its debt holdings. This rating is a useful reference point.

    5. Debt-oriented taxation

    Since the majority of the portfolio sits in debt instruments, these funds are taxed in line with debt mutual fund rules. Under the rules effective from April 2023, gains are added to the investor’s income and taxed at their applicable slab rate, with no indexation benefit available.

    Example

    To understand this, let us take an easy example, since that usually makes the concept click faster than any explanation.

    Say an investor puts in ₹10 lakh into a Capital Protection Fund with a three-year horizon. The fund manager doesn’t split this randomly

    A large chunk, say ₹8.5 lakh, goes into debt instruments like government bonds and high-rated corporate papers. This portion will not chase returns. It’s only meant for stability, to earn steady interest, and to grow back to roughly ₹10 lakh by the time the three years are up. Think of it as the anchor that holds the whole structure together.

    The remaining ₹1.5 lakh goes into equities. This portion of your investments will contribute to the growth. If the markets perform well over those three years, this part could grow, pushing the total value of the investment above ₹10 lakh. If markets are volatile or underperform, this same portion could shrink, or in a bad scenario, lose value entirely.

    Read Also: Stable Value Fund: Meaning, Benefits, Risks & How It Works

    Who Should Invest in Capital Protection Funds?

    1. Conservative investors who want some equity exposure

    Many investors are not comfortable with the ups and downs of pure equity funds, but they also feel that debt funds or fixed deposits alone don’t offer enough growth. This fund can be a good fit.

    2. Investors with a medium-term goal

    Since these funds are usually meant for 3 to 5 years, they work well for goals that fall within that window. This could be something like building a corpus for a child’s education a few years down the line, saving toward a planned purchase, or keeping aside money for a milestone that is neither immediate nor very far off.

    3. First-time mutual fund investors

    For someone who has only used FDs or recurring deposits so far and is a little hesitant about equity markets, this fund can serve as a good entry point. It offers limited market exposure without putting the entire investment at risk.

    On the other hand, this fund may not be the right fit for investors chasing high growth over the long term, since the limited equity allocation caps the upside. It also isn’t suitable for anyone who might need liquidity in the short run, given the lock-in nature of most schemes.

    Points to Remember 

    Before putting money into a Capital Protection Fund, check a few things.

    1. Look at the credit quality of the debt holdings

    The entire protection strategy rests on the debt portion, so it is important to check whether the fund is holding high-rated instruments like AAA bonds and government securities, or whether it is chasing slightly higher yields with lower-rated paper.

    2. Understand the lock-in period clearly

    Since most of these funds are closed-ended, know exactly when the scheme matures and what happens if money is needed before that. It is better to be clear on this upfront than to assume the money can be redeemed whenever needed.

    3. Do not skip the tax calculation

    Gains from these funds are taxed at the investor’s income slab rate, with no indexation benefit. Check this through your own tax bracket before investing, since it can reduce what looks like a decent return on paper.

    4. Read the Scheme Information Document

    The SID lays out the exact allocation range between debt and equity, the rating approach, and the specific risks the fund house has flagged. Marketing material highlights only the upside, so this document gives a complete picture.

    5. Keep expectations realistic

    The portion invested in equity is small, so the potential upside is limited too. This fund is not meant to deliver high growth; it is meant to offer a bit more than a fixed deposit, with a bit more risk. Going in with that understanding avoids confusion at maturity.

    Do These Funds Still Exist?

    Capital Protection Oriented Funds are still a recognised category under SEBI’s hybrid fund framework, and nothing has removed them from the rulebook. 

    But in practice, they have become close to a legacy product. The biggest reason is the 2023 debt tax overhaul. 

    For years, closed-ended debt and capital protection funds were attractive largely because of the long-term capital gains benefit with indexation. That changed in April 2023, when the government removed indexation benefits for mutual funds holding less than 35% in equity. 

    Capital gains from these funds are now taxed directly at the investor’s income slab rate, which took away much of what made this category appealing in the first place.

    These funds are closed-ended with fixed tenures. AMCs can only bring them to market through a New Fund Offer, and only after getting a strong credit rating for the underlying structure. With several open-ended alternatives now available, fund houses rarely find it worthwhile to launch a fresh series

    Some of the funds that were offered earlier are as follows;

    1. SBI Capital Protection Oriented Fund Series A: from SBI Mutual Fund 
    2. Nippon India Capital Protection Oriented Fund II: from Nippon India Mutual Fund 
    3. HDFC Capital Protection Oriented Fund 

    Read Also: What is Fund of Funds (FOF)?

    Conclusion 

    Capital Protection Funds offer a middle path for investors who want more than a fixed deposit but aren’t ready to deal with the wild swings of the stock market. The idea is simple: keep most of your money safe in debt instruments, and let a small equity portion try to add a bit extra. 

    However, while investing, you need to remember the lock-in period, the lack of any real guarantee, and the way gains get taxed. As with most financial decisions, it comes down to matching the product to your own goal, investment horizon, and comfort with risk, rather than going by the name alone.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top Gold Mutual Funds in India
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. Are Capital Protection Funds completely safe?

      Not completely. They are designed to protect your capital, but there is no guarantee, since they are still market-linked.

    2. How do Capital Protection Funds work?

      Most of your money goes into debt instruments that grow back to your original investment by maturity, while a small part goes into equities for potential upside.

    3. Can Capital Protection Funds lose money?

      Yes, in rare cases, especially if the equity portion performs badly or the debt holdings face credit issues.

    4. Are Capital Protection Funds better than FDs?

      Not necessarily better. FDs offer fixed, guaranteed returns, while these funds can offer higher returns with slightly more risk.

    5. What is the investment horizon for Capital Protection Funds?

      It is usually three to five years, since most of these schemes are closed-ended with a fixed maturity period.

  • How to Start SIP Using E-Mandate?

    How to Start SIP Using E-Mandate?

    To start a SIP using an e-mandate, choose your mutual fund scheme, enter your SIP details, select e-mandate as the payment method, and authenticate it through your bank. Once the mandate is approved, your SIP amount can be debited automatically on the scheduled dates. This makes recurring SIP payments easier without requiring manual payment each month.

    What Is an E-Mandate?

    An e-mandate is a digital instruction that authorises recurring debits from your bank account. For a SIP, it allows the approved amount to be automatically debited according to the investment schedule.

    In India, NACH is one of the systems used for recurring mutual fund payments. NPCI describes NACH as a centralised system for repetitive and periodic electronic transactions. Mutual fund investments are among its supported use cases.

    The mandate is registered after you provide the required details and authenticate the request. Depending on the facility and participating bank, authentication can be completed using supported digital methods. NPCI’s NACH guidelines, for example, provide for online mandate authentication through net banking or debit card credentials.

    An e-mandate only handles the payment instruction. It does not affect the mutual fund’s NAV, investment strategy, market risk, or potential returns.

    Why Use an E-Mandate for SIP?

    An e-mandate makes recurring SIP payments more convenient because you do not have to initiate every installment separately.

    Some of its key benefits include:

    • SIP instalments can be debited automatically after mandate approval.
    • It reduces the need to remember and make monthly payments manually.
    • Registration can be completed digitally where the facility is supported.
    • You can authorise a maximum mandate amount for recurring debits.
    • It can be useful when managing multiple future SIP installments.
    • The mandate can generally be cancelled through the available bank or investment platform process.

    The main benefit is payment convenience. An e-mandate does not increase SIP returns or reduce the investment risk of the selected scheme.

    How to Start SIP Using E-Mandate?

    The exact screens can vary between investment platforms and fund houses. However, the basic process of starting a SIP using an e-mandate remains similar.

    1. Complete Your KYC

    Complete the required KYC process before registering your mutual fund SIP. KYC compliance is required for mutual fund investments in India.

    If you have already completed valid KYC through a SEBI-registered intermediary, you may not have to complete the entire process again.

    Make sure your PAN, mobile number, email address, and other required details are correctly updated.

    2. Select the Mutual Fund Scheme

    Choose the mutual fund scheme in which you want to start a SIP.

    Consider factors such as:

    • Your financial goal.
    • Investment horizon.
    • Risk tolerance.
    • Scheme category.
    • Investment strategy.
    • Expense ratio and other applicable costs.

    Do not choose a fund simply because the payment process is convenient. The scheme should fit your investment requirements.

    3. Enter the SIP Details

    Choose SIP as the investment mode and enter the required details. These generally include the SIP amount and investment frequency.

    Monthly SIPs are common, but available frequencies can vary between schemes and AMCs. The minimum SIP amount can also differ by scheme.

    4. Choose the SIP Date and Duration

    Select the date on which you want the SIP instalment to be processed.

    You may also need to select whether the SIP should continue for a fixed period or according to the tenure options offered by the platform or scheme.

    Keep the selected date in mind when managing your bank balance. The required amount should be available when the debit is presented.

    5. Select E-Mandate as the Payment Option

    Choose the available e-mandate or supported auto-debit option.

    You will usually need to select or provide the bank account from which future SIP instalments will be debited.

    Check that the bank account belongs to the eligible investor and that the details match the information required for your mutual fund investment.

    6. Set the Mandate Amount

    Enter the maximum amount that can be debited under the mandate.

    The mandate amount should be at least sufficient to cover your intended SIP transactions under that mandate. Avoid setting a limit below the amount required for your SIP.

    Remember that the mandate limit is not necessarily the amount that will be debited every month. It represents the authorised maximum, while the actual debit depends on the SIP instruction.

    7. Authenticate the E-Mandate

    Complete the authentication using the method supported by your bank and platform.

    For NACH API e-mandates, NPCI provides mechanisms that can use net banking or debit card-based authentication.

    Review the account details, mandate amount, and other information before confirming the request.

    8. Check the Mandate Status

    After authentication, the mandate needs to be accepted before recurring debits can begin.

    NPCI states that the debit can be initiated only after the mandate has been accepted through the relevant process. It also provides for customers to receive confirmation regarding mandate registration.

    Check the status on your investment platform before assuming that your SIP auto-debit is active.

    Read Also: What Is One Time Mandate (OTM) in SIP?

    How Does E-Mandate Work for SIP?

    An e-mandate connects your approved recurring payment instruction with your bank account. Once it is registered, the authorised debit can be presented according to your SIP schedule.

    NACH is operated by the National Payments Corporation of India. It was developed as a centralised system for high-volume, repetitive, and periodic transactions. It also consolidated multiple earlier ECS systems into a common framework.

    The process can be understood simply:

    1. You register a SIP with your investment platform or mutual fund.
    2. You provide a mandate for recurring payments.
    3. You authenticate the mandate through an available method.
    4. The mandate is processed and registered.
    5. The SIP debit is presented according to the selected schedule.
    6. If the debit succeeds, the SIP investment is processed according to applicable mutual fund rules.

    The actual NAV applicable to your investment depends on prevailing mutual fund transactions and cut-off rules. Registering an e-mandate does not guarantee a particular NAV.

    What to Check Before Setting Up an E-Mandate?

    Small errors in bank or mandate details can result in registration or debit failures. Check the information carefully before submitting your request.

    DetailWhat to Check
    Bank accountMake sure the account details are correct and eligible for the mandate.
    Bank supportConfirm that your bank supports the e-mandate method offered by the platform.
    SIP amountCheck that the amount matches your planned investment.
    Mandate limitKeep the authorised limit sufficient for the intended SIP debit.
    SIP dateChoose a date when you are likely to maintain sufficient balance.
    KYCEnsure that your applicable KYC requirements are complete.
    Contact detailsKeep your registered mobile number and email updated for alerts.

    Also check the mandate status after completing authentication. A submitted mandate and an active mandate are not necessarily the same thing.

    Common E-Mandate Issues and How to Fix Them

    Most e-mandate problems involve registration details, authentication, mandate limits, or insufficient funds.

    1. Incorrect Bank Details

    A mismatch in bank details can cause mandate registration to fail.

    Check the account information entered during registration. If the mandate has already been rejected, you may need to submit a fresh request with the correct details.

    2. Insufficient Bank Balance

    Your SIP debit may fail if your account does not have sufficient funds when the debit is presented.

    Maintain an adequate balance around the SIP debit date. Also check whether your bank applies any charges for failed auto-debit instructions.

    3. Authentication Failure

    An e-mandate may fail during authentication because of incorrect credentials, OTP issues, unsupported account types, or bank-side problems.

    Retry using a supported authentication method. If the problem continues, check with your bank or investment platform.

    4. Mandate Limit Is Too Low

    The debit may not go through if the amount requested exceeds the permitted mandate amount.

    Check your mandate limit against the SIP amount. Depending on the available facility, you may need to modify or register a new mandate.

    5. Mandate Is Not Active

    Completing the authentication step does not always mean the mandate is immediately ready for debits.

    Check whether its status shows that registration has been completed or accepted before relying on it for the next SIP.

    6. Mandate Registration Is Delayed

    Mandate processing time can vary depending on the bank and registration route.

    NPCI’s eSign mandate FAQ, for example, specifies processing timelines for the participating banks while noting that these timelines can change.

    If the status remains pending beyond the expected period shown by your platform, contact the platform or bank.

    E-Mandate Limits and Important Rules

    The rules applicable to an e-mandate can depend on the mandate type, payment system, bank, and platform. Therefore, you should check the limits displayed when registering your mandate rather than relying on a single limit for every digital recurring payment method.

    For NACH eSign mandates, NPCI’s published FAQ states a mandate amount cap of ₹1 lakh. NPCI also maintains lists of banks and entities participating in its e-mandate infrastructure.

    Keep these points in mind:

    • Your bank must support the relevant mandate facility.
    • A mandate must be accepted before debits can be initiated under it.
    • Incorrect or non-compliant mandate data can result in rejection.
    • Applicable mandate limits can depend on the payment route being used.
    • Cancellation and modification processes can vary by bank and platform.

    Do not confuse NACH e-mandates with every other type of recurring digital payment. Different payment systems can operate under different rules and transaction limits.

    E-Mandate vs Traditional Mandate

    Both methods can authorise recurring payments, but the registration process is different.

    FactorE-MandateTraditional Mandate
    RegistrationDigital.Paper-based.
    AuthenticationThrough supported electronic authentication.Physical signature and documentation may be required.
    PaperworkMinimal or none for the mandate process.Physical mandate form may be required.
    ProcessingElectronic registration.Depends on physical submission and processing.
    ConvenienceCan generally be completed remotely where supported.May involve physical documentation.
    Status trackingUsually available digitally through the relevant platform.Tracking can depend on the institution’s process.

    Read Also: Smart SIP: Meaning, How It Works, Benefits & Risks

    Conclusion

    Starting a SIP using an e-mandate involves choosing your scheme, setting the SIP details, authorising recurring bank debits, and waiting for the mandate to become active. Once registered, it can automate future SIP payments and reduce the need for manual transactions.

    You can use Pocketful to explore mutual funds and set up your investments digitally. Before confirming your SIP, review the scheme details, mandate limit, bank information, and payment schedule carefully.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Top-up SIP?
    2What Is SWP in Mutual Funds?
    3Power SIP: Meaning, How It Works, Benefits & Risks
    4SIP vs Recurring Deposit (RD)
    5What is STP in Mutual Funds?

    Frequently Asked Questions (FAQs)

    1. What Is an E-Mandate in SIP?

      An e-mandate authorises automatic SIP debits from your registered bank account on scheduled dates.

    2. How Long Does an E-Mandate Take to Activate?

      Activation time varies by bank and platform. Check the mandate status before your first SIP date.

    3. Can I Cancel an E-Mandate?

      Yes. You can cancel an e-mandate through the available bank, AMC, or investment platform process.

    4. What Happens if an E-Mandate Debit Fails?

      The SIP instalment may not be processed. Check your balance, mandate status, and debit limit before the next due date.

    5. Is an E-Mandate Safe for SIP Payments?

      Yes. E-mandates use banking authentication and regulated payment infrastructure for recurring transactions.

  • What Is Clawback in Mutual Funds?

    What Is Clawback in Mutual Funds?

    The mutual fund in which you have invested reaches you through a distribution network that includes the AMC and distributor. The mutual fund distributor gets a commission for bringing mutual funds to you. But in case you withdraw funds before a stipulated time period, the commission given to the distributor will be taken back by the asset management company, and this provision is known as “Clawback”.

    What is Clawback in Mutual Funds?

    Clawback meaning in mutual funds is a method of recovering the commission or incentive that has already been paid to the distributor of a mutual fund. These are recovered only when certain conditions are not met, such as when the investor withdraws their investments before a stipulated time period. It does not impact the investors; it applies only to distributor commission. This clawback ensures that commissions and incentives are paid only when conditions attached to them are fulfilled. This was implemented to discourage the practice of unnecessary churning of investors’ portfolios.

    Key Elements of Clawback in Mutual Funds

    The key elements of clawback in mutual funds are as follows:

    1. Commission: The commission or incentive of the distributor is linked to bringing a new investor or servicing an existing investment.
    2. Trigger Event: The clawback generally triggers only when certain conditions are not fulfilled. These events include early redemption by the investor, etc.
    3. Recovery: Once the specific events are triggered, the AMC may recover the eligible amount of commission or incentive from the distributor.
    4. AMC Specific Conditions: The clawback conditions are not common across all mutual fund schemes or AMCs. The applicable conditions of clawback depend on the AMC and its conditions.
    5. Clawback Clause Meaning: Whenever the conditions specified under the distributor agreement are triggered, the provisions related to clawback may apply. Simply put, the clawback clause means the set of conditions that determines when an AMC can recover the commission already paid to the distributor. 

    How Does Clawback Work in a Mutual Fund?

    The clawback in the mutual fund works in the following manner:

    1. Investment: The first step is when an investor purchases the units of a mutual fund scheme through a distributor.
    2. Receiving Commission: The AMC pays the commission based on the investment amount of the investor. The commission structure depends on the agreement between the AMC and the distributor.
    3. Clawback Conditions: Whenever the investor withdraws their money before the stipulated time period, the provisions related to clawback apply.
    4. Recovery of Amount: If the clawback conditions are triggered, the AMC can recover the relevant commission from the distributor.
    5. Redemption Proceeds: The investor receives the redemption amount according to the applicable NAV rate.

    Examples of Clawback Clause

    Let’s understand the concept of clawback through an example. 

    There is a mutual fund distributor named ABC Limited who has been engaged in the mutual fund distributor business for the last few years. There is an investor of ABC Limited named Rahul who has invested 10 Lakh INR in a mutual fund scheme through ABC Limited. For his investment, the distributor received a commission of INR 10,000 INR.

    After a few months of investment, Rahul withdrew his entire investment. This redemption triggers a clawback condition. Now the AMC in which Rahul has invested his money wants the commission amount back, and it may recover the eligible 10000 INR commission from the distributor.

    Benefits of Clawback

    The key benefits of clawback in mutual funds are as follows:

    1. Reduces Mis-selling: The provision of clawback discourages the recommendation of products based only on commission and unnecessary churning of the portfolio.
    2. Long-Term Investing: The clawback holds investors from making unnecessary short-term transactions and encourages the investor to build long-term investor relationships.
    3. Investor Interest: Clawback is a mechanism between the AMC and distributor, but it can indirectly benefit investors by creating a favouring investor suitability.
    4. Improve Transparency: Clawback makes distributors more accountable for the incentives they receive. It acts as a disciplinary mechanism for mutual fund distributors.

    Read Also: Side Pocketing in Mutual Funds Explained

    Challenges of Clawback 

    The key challenges while implementing clawback are as follows:

    1. Complex Structure: The commission and incentive structure of mutual funds involves various conditions, periods, calculations, etc. Therefore, applying the clawback provision can be very difficult sometimes, especially when the distributor deals with various AMCs.
    2. Administrative Work: Tracking redemptions, their dates, and amounts can be difficult for a distributor to manage. This tracking requires regular monitoring that increases the distributor’s administrative burden.
    3. Different Conditions: The clawback provisions may differ depending on the AMC, type of scheme, etc. Due to this, the distributor needs to understand the terms and conditions related to every AMC.
    4. Financial Pressure on Distributor: Whenever a clawback is applicable, the distributor may need to return the part of the commission that they had already received. In case of such reversal, it can impact the cash flow of distributors.

    Regulatory Guidelines of Clawback

    The regulations related to clawback guidelines are as follows:

    1. Mutual Funds: SEBI allows AMCs to structure the commission distributed to distributors. This clawback clause applies to distributors and depends on the agreement between the AMC and the distributor.
    2. Listed Companies: According to the Companies Act 2013 and the SEBI corporate governance framework, clawback provisions, etc. are applied in case of any fraud, misstatement of accounts, etc.
    3. Banking and NBFCs: The Reserve Bank of India states that banks and financial institutions include malus and clawback clauses according to various payment structures.
    4. Bank: For banks, at least 50% of their variable pay of senior management must be deferred. This deferred portion is then subject to malus or clawback during the retention period in case of any misconduct, etc.
    5. NBFCs: There is no fixed 50% requirement for variable pay. It requires that deferred commissions are applicable under conditions such as weak financial performance, etc.

    Conclusion 

    On a concluding note, clawback in mutual funds is a technical term that often does not directly impact the investor. However, this provision is made to protect the interest of the investor. In this mechanism, the asset management company can recover the amount of commission or incentive paid earlier to the mutual fund distributor if certain conditions are triggered. This clawback is applicable only when the investor withdraws their fund before a stipulated time period. The key objective is to encourage responsible distribution practices and reduce unnecessary churning of the portfolio. However, it is always advisable to consult your investment advisor before making any investment in mutual funds.  

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What Is An IPO Mutual Fund? Should You Invest?
    2Mutual Fund Taxation – How Mutual Funds Are Taxed?
    3Is Your Mutual Fund Investment Safe?
    4What is an Open-Ended Mutual Fund & How to Invest in it?
    5How to Cancel Mutual Fund SIP?

    Frequently Asked Questions (FAQs)

    1. Is clawback deducted from the investor’s investment?

      No, clawback is not deducted from the investor’s investment. It is related to the commission paid to the distributor.

    2. What is the meaning of Clawback?

      Clawback refers to the condition in which the investor redeems their investment before a stipulated time period, and the AMC recovers the commission that was paid previously to the mutual fund distributor.

    3. Can clawback impact the returns of a mutual fund?

      No, clawback does not directly impact the returns of a mutual fund. It only affects the commission paid to the distributor.

    4. Is clawback applicable to both direct and regular mutual fund schemes?

      Clawback applies only to regular mutual fund schemes in which a distributor is involved, and a commission is paid to them. It does not apply to direct mutual fund schemes, as it does not involve a distributor.

    5. Who decides the clawback conditions?

      The clawback conditions are generally decided by asset management companies under the relevant regulatory framework defined by AMFI and SEBI.

  • What Is One Time Mandate (OTM) in SIP?

    What Is One Time Mandate (OTM) in SIP?

    To maintain an SIP over the long term, installments must be deposited on time every month. In this context, the ‘One-Time Mandate’ (OTM) offers a convenient way to simplify SIP payments. In this blog, we will explore what OTM is, how it works with SIPs, how to set it up, and the key points to keep in mind while using it.

    What is One Time Mandate (OTM) in SIP? 

    A One Time Mandate (OTM) for an SIP is a payment authorization where an investor grants permission to debit SIP installments from their bank account based on pre-set terms. Once set up, there is no need to provide a separate cheque or payment instruction for each installment. OTMs are typically used for recurring SIP payments via the NACH (National Automated Clearing House) facility.

    Why is it called a “One Time” Mandate?

    Because the mandate does not need to be registered repeatedly. Once the OTM is successfully registered, SIP installments can be debited within the specified validity period and limit. However, the OTM itself is not an investment; it is simply an authorization granted for SIP payments.

    Example: Suppose you start a monthly SIP of ₹5,000 and register an OTM for it. Once the mandate becomes active, ₹5,000 can be debited from your registered bank account on the scheduled date every month. You will not need to make a separate payment each month.

    How Does OTM Work for SIP? 

    To understand how OTM works, let’s look at the process in simple terms. While the method may vary slightly across different AMCs or platforms, the general workflow remains largely the same:

    Step 1: Select SIP details

    First, the mutual fund scheme, SIP amount, frequency, and debit date are determined. These details are subsequently used for the SIP instruction.

    Step 2: Register the OTM

    Next, an OTM/NACH mandate is registered against your bank account for SIP payments. This involves providing the necessary details regarding the bank account and the mandate.

    Step 3: Mandate verification

    The bank and the relevant payment system verify the mandate details. The OTM can only be used once the registration is successfully completed. Activation for a physical OTM may take time; some AMCs indicate a timeframe of approximately 25–30 calendar days in their documentation.

    Step 4: SIP due date arrives

    Once the mandate is active, the fund house or authorized entity sends a debit request based on the registered mandate on your scheduled SIP date. NACH is used for recurring and periodic payments, including mutual fund investments.

    Step 5: Amount debited from the bank account

    If the mandate conditions are met and there is sufficient balance in the account, the SIP amount is debited from the bank account. Subsequently, the SIP investment proceeds according to the standard transaction process.

    OTM vs e-Mandate vs UPI AutoPay: What is the Difference? 

    All three aim to simplify recurring payments, though their operational methods may differ. OTM/NACH is a mandate used for mutual fund SIP payments, whereas e-Mandate can be considered its digital counterpart. UPI AutoPay enables recurring payments via UPI and, according to the NPCI, can also be used for mutual fund payments.

    BaseOTM / NACHe-Mandate / eNACHUPI AutoPay
    Main ObjectiveAuthorization for bank debits for recurring payments like SIPs.Creating a recurring debit mandate digitallyAuthorizing recurring payments via UPI
    Payment systemThrough NACHElectronic mandate processUPI 
    Used in SIPYesYes, wherever the AMC/platform supports it.Yes, where available
    Setup procedureDepends on the physical or available digital process.Generally, an online/electronic process.Through a UPI-enabled app
    Manual payment every monthGenerally not needed.Generally not needed.Generally not needed.
    Can the amount be debited from the account?Yes, in accordance with the registered mandate.Yes, in accordance with the authorized mandate.Yes, in accordance with the approved AutoPay instruction.

    Why is OTM Used for SIP? 

    The primary objective of OTM is to simplify the payment of regular SIP installments, enabling the designated amount to be automatically debited in accordance with the active mandate.

    • Eliminates the need for separate monthly payments: Once the OTM is active, there is no need to manually make payments for SIP installments every month. This streamlines the regular investment process.
    • Reduces the risk of missing SIP installments: Investors might sometimes forget to make SIP payments due to busy schedules. The auto-debit facility helps mitigate this issue.
    • Facilitates long-term SIP investments: If you wish to continue your SIP over several years, recurring debits can be executed via a registered mandate instead of repeating the payment process each month. NACH is used for such recurring and periodic transactions.
    • Offers convenience in the payment process: Once the mandate is successfully activated, the investor generally does not need to provide separate payment instructions for each SIP installment. However, it is essential to maintain a sufficient balance in the bank account for the SIP debit to go through.

    Read Also: Smart SIP: Meaning, How It Works, Benefits & Risks

    Example How OTM Works With a Monthly SIP 

    Suppose Neha starts a monthly SIP of ₹5,000 and registers an OTM with a mandate limit of ₹10,000 for payments. Once the mandate is active, a debit request for ₹5,000 can be initiated on the scheduled SIP date. Here, the mandate limit is ₹10,000, while the actual SIP installment is ₹5,000 the two are not the same.

    InformationExample
    SIP amount₹5,000 per month
    Mandate limit₹10,000
    SIP frequencyMonthly 
    Payment methodOTM/NACH
    Debit accountRegistered bank account
    Manual payment every monthNot required if the mandate is active.

    How to register OTM for SIP?

    Registering for an OTM is not difficult. You simply need to provide the correct details of the bank account from which the SIP installment will be deducted and approve the mandate. The process generally proceeds as follows:

    • Select Your Bank Account: First, choose the bank account you wish to use for your SIP installments. It is crucial that the account details are accurate, as future debits will be made from this specific account.
    • Set the Mandate Amount: An OTM involves specifying a debit amount or a maximum limit. For instance, if your SIP is for ₹5,000, you can set a higher limit in the mandate, provided the platform’s terms allow it.
    • Approve the Mandate: Next, you must authorize the mandate using the prescribed method. This can be done via a physical form or a digital process; the available method depends on your AMC or investment platform.
    • Check Registration Status: After submitting the mandate, you must wait for it to become active. Do not assume that the SIP payment will happen automatically before the OTM is active. It is advisable to check the status of both the mandate and the SIP before the first installment is due.
    • Maintain Sufficient Balance Before the First Installment: Even after the mandate becomes active, it remains your responsibility to maintain a sufficient balance in your bank account to cover the SIP amount. If the balance is insufficient, the debit may fail, and applicable charges may be levied.

    What Happens if There is Not Enough Money in the Bank? 

    If there is insufficient balance in your account on the SIP due date, the debit via OTM (One Time Mandate) may fail. Consequently, that specific SIP instalment will not be processed. Depending on the bank’s or platform’s policy, charges may also be levied for a failed transaction. Therefore, it is advisable to maintain the required balance in your account beforehand.

    Does the entire SIP get cancelled?

    No, the failure of a single instalment does not mean that your entire SIP or the mutual fund units you have already purchased are automatically cancelled. However, if instalments fail repeatedly, the specific terms and conditions of the AMC or the platform may apply.

    Is a failed SIP retried?

    This varies across platforms. Some platforms do not retry failed payments, so one should not assume that the money will be debited again automatically. Be sure to check the policy of your AMC or investment platform.

    Can You Cancel or Change an OTM?

    Yes, an OTM (One Time Mandate) can be cancelled or modified if needed. However, stopping an SIP and cancelling an OTM are not the same thing. Stopping an SIP halts the investment instruction, whereas the mandate remains linked to the bank’s permission for recurring debits.

    When might you need to cancel an OTM?

    It may be advisable to cancel the OTM if you have stopped the SIP, changed your bank account, or no longer require the old mandate, especially if other SIPs are also linked to that same mandate.

    How can an OTM be modified?

    To change mandate details, you usually need to submit a new or modified mandate. The specific details that can be changed and the procedure involved depend on the rules of the respective bank, AMC, or investment platform.

    What should you check before cancelling an OTM?

    Before cancelling, verify which SIPs are linked to that mandate. If multiple SIPs rely on the same mandate, cancelling it could affect them as well. Therefore, if necessary, arrange an alternative valid payment method or mandate for the affected SIPs beforehand.

    OTM for SIP: Advantages and Limitations 

    OTM can simplify SIP payments, but it is also important to understand its practical limitations before using it.

    BenefitsBoundaries
    There is less need to make separate payments for each installment.It may take some time for the mandate to get activated.
    It helps in keeping SIP payments regular.It is necessary to maintain a sufficient balance in the bank account.
    It is convenient to run an SIP for the long term.Charges may apply depending on the bank or platform if the debit fails.
    It eliminates the hassle of repeatedly entering payment details.Rules may vary across different AMCs, banks, and platforms.
    Managing eligible recurring payments with a single mandate can be easy.There may be a separate process to cancel or modify the mandate.

    Read Also: What Is Stock SIP?

    Conclusion

    A One-Time Mandate for SIPs can make your monthly investment payments simple and organized. Once the mandate is set up, SIP installments can be paid automatically. Just keep an eye on the mandate details, validity, and bank balance to ensure your investment continues without unnecessary interruptions.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Top-up SIP?
    2What Is SWP in Mutual Funds?
    3Power SIP: Meaning, How It Works, Benefits & Risks
    4SIP vs Recurring Deposit (RD)
    5What is STP in Mutual Funds?

    Frequently Asked Questions (FAQs)

    1. What is a One Time Mandate (OTM) for SIPs?

      OTM is a payment authorization that allows the scheduled SIP installment to be debited from your bank account.

    2. Is an OTM mandatory for SIPs?

      No, an OTM is not mandatory for every SIP; available payment options depend on the AMC or the platform.

    3. How does an OTM work for SIPs?

      Based on the active OTM, an authorized debit request is sent to the bank on the SIP due date.

    4. Can I cancel my OTM?

      Yes, the OTM can be cancelled by following the applicable process.

    5. What happens if my OTM fails?

      If the debit is unsuccessful, the payment for that SIP installment may fail, and applicable charges may be levied.

  • What is Trigger SIP & How It Works?

    What is Trigger SIP & How It Works?

    A Trigger SIP is a mutual fund investment facility where a predefined condition determines when a transaction takes place. The condition may be linked to NAV, an index level, investment value, or a specific date. Unlike a regular SIP that invests on a fixed schedule, a trigger-based facility acts when the selected condition is met.

    What Is Trigger SIP?

    What is Trigger SIP can be understood as a rule-based approach to mutual fund transactions. You define a condition in advance, and the specified action is initiated when that condition is met.

    A regular SIP works on a fixed schedule. For example, you may invest ₹5,000 on the 10th of every month. The investment continues regardless of whether the market is rising or falling.

    A trigger facility works differently. Depending on the AMC and scheme, it may initiate an investment, redemption, or switch when the selected condition occurs.

    For example, you may choose a particular NAV level as your trigger. Once the scheme reaches the specified level, the predefined transaction is initiated.

    Trigger facilities are not standard across all mutual funds. Their availability, conditions, and permitted transactions can differ between AMCs and schemes.

    How Does a Trigger SIP Work?

    A Trigger SIP connects a predefined condition with an investment instruction. Instead of making a decision after a market movement, you decide beforehand what should happen. To understand this better, here are the steps that you should know:

    1. Select the Mutual Fund Scheme

    First, choose a mutual fund scheme that offers the trigger facility you need. Not every scheme provides the same trigger options.

    2. Choose the Trigger Condition

    Next, select the condition that will activate the transaction. This could be based on anything like NAV, date, risk, or anything else as well.

    3. Define the Transaction

    You then specify what should happen once the trigger is reached. Depending on the scheme, this could involve an investment, redemption, or switch.

    4. Wait for the Trigger

    The trigger remains active according to the applicable terms. When the condition is met, the specified transaction is initiated.

    However, the trigger level should not be confused with the final transaction NAV. Mutual fund transactions remain subject to applicable NAV and cut-off rules.

    Read Also: Stable Value Fund

    Types of Trigger SIP

    The triggers available depend on the AMC and mutual fund scheme. Some commonly available conditions include:

    1. NAV-Based Trigger

    This trigger is linked to the Net Asset Value of a mutual fund scheme. Suppose the current NAV is ₹120 and you set a trigger at ₹100. The selected transaction can be initiated if the NAV reaches the specified level, subject to the scheme conditions.

    Some facilities may also allow triggers based on a specified percentage of NAV appreciation or depreciation.

    2. Index-Based Trigger

    An index-based trigger depends on the movement of a market index, such as the Nifty 50 or Sensex.

    For example, an investor could set a transaction to activate when an eligible index reaches a specified level. This connects the investment decision with broader market movement rather than only the scheme’s NAV.

    3. Investment Value Trigger

    Here, the condition depends on how much the value of your existing investment changes.

    For example, a trigger could be linked to a specified percentage increase or decrease in investment value. Once that level is reached, the selected transaction may be initiated.

    4. Date-Based Trigger

    A date-based trigger activates on a predefined date.

    It can be useful when you already know when you want a particular transaction to take place. Processing remains subject to business-day and scheme-specific rules.

    Trigger SIP vs Regular SIP vs Step-Up SIP

    The three approaches differ mainly in how investments are scheduled and managed.

    FactorTrigger SIPRegular SIPStep-Up SIP
    BasisPredefined condition.Fixed schedule.Fixed schedule with increases.
    TimingDepends on trigger.Regular intervals.Regular intervals.
    AmountDepends on facility.Usually fixed.Increases periodically.
    Market-linked conditionCan be used.No.Usually no.
    MonitoringComparatively higher.Low.Low after setup.
    PurposeRule-based transactions.Consistent investing.Increasing investments over time.

    Benefits and Limitations of Trigger SIP

    A Trigger SIP offers more control over when certain transactions take place. But there are certain pros and cons associated with the same as well. SO, let us understand the same in detail over here.

    Benefits of Trigger SIP

    • Predefines investment decisions before market movements occur.
    • Links transactions to specific NAV, index, or investment conditions.
    • Helps automate tactical investment decisions.
    • Reduces the need to manually place a transaction when the condition is met.
    • May support investments, switches, or redemptions, depending on the scheme.

    Limitations of Trigger SIP

    • Requires you to identify a suitable trigger level in advance.
    • May leave your money uninvested if the selected trigger is never reached.
    • Does not guarantee that the transaction will happen at the exact trigger NAV.
    • Can activate before the market rises or falls further.
    • Trigger options and rules vary across AMCs and schemes.
    • Requires more planning and monitoring than a regular SIP.

    Does Trigger SIP Give Better Returns?

    A Trigger SIP does not automatically generate better returns than a regular SIP.

    Its performance depends on the trigger selected and what happens after the transaction. A trigger that activates during a market correction may allow you to purchase more units at a lower NAV. However, waiting for a correction that never arrives can also delay your investment.

    Regular SIPs already respond indirectly to market movements through rupee-cost averaging.

    Consider an investor putting ₹5,000 into a fund every month:

    MonthNAVUnits Purchased
    January₹50100
    February₹40125
    March₹25200
    April₹50100

    When NAV falls to ₹25, the same ₹5,000 automatically buys 200 units. The investor does not need to predict the fall beforehand.

    This is one reason regular SIPs are widely used for long-term investing. They focus on consistency rather than finding the ideal entry point.

    Trigger-based investing serves a different purpose. It allows investors to automate a specific market view or portfolio rule. Whether that improves the final outcome depends on the accuracy and suitability of that rule.

    Who May Consider a Trigger SIP?

    A Trigger SIP may suit investors who want more control over when specific mutual fund transactions take place. Since triggers depend on predefined conditions, investors should understand how NAV movements, market levels, and trigger rules work before using them.

    It may be considered by investors who:

    • Understand mutual fund NAV and basic market movements.
    • Regularly monitor their investments and market conditions.
    • Have a clear reason for choosing a particular trigger level.
    • Prefer rule-based decisions instead of reacting to short-term market movements.
    • Are comfortable waiting if the selected trigger takes time to activate.
    • Understand that reaching a trigger does not guarantee a favourable investment outcome.

    Read Also: SIF Regulations in India

    Things to Check Before Setting a Trigger SIP

    Before setting a Trigger SIP, understand what will activate it and what happens afterwards. The trigger should fit your investment plan rather than simply react to short-term market movements.

    • Check Whether the Facility Is Available: Not every AMC or mutual fund scheme offers the same trigger options. Check which trigger facilities are available for your chosen scheme before setting one.
    • Understand the Trigger Condition: Be clear about what needs to happen for the trigger to activate. Check whether the NAV or index status. See the movements to understand better. 
    • Know What Happens After the Trigger: Understand the transaction linked to the trigger. Depending on the facility, it may initiate an investment, redemption, or switch.
    • Check the Applicable NAV Rules: The trigger level may not be the NAV at which your transaction is completed. The applicable NAV depends on transaction type, cut-off timings, and relevant mutual fund rules.
    • Consider Exit Load and Tax: If the trigger leads to redemption or switching, check the possible tax and exit-load implications. A switch generally involves redemption from one scheme and a fresh investment into another.
    • Choose the Trigger Level Carefully: Avoid selecting a NAV or index level simply because it looks attractive. Your trigger should have a clear purpose and align with your investment goal and time horizon.

    Conclusion

    What is Trigger SIP essentially comes down to linking an investment action with a predefined condition. It can provide more control over when certain mutual fund transactions happen, but it also adds complexity and market-timing risk.

    For long-term investors who value consistency, a regular SIP remains a simpler approach. Investors who actively follow markets may use trigger facilities for specific rule-based decisions. With Pocketful, you can explore mutual funds, monitor your investments, and manage your funds in a way better manner. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What Is a Trigger SIP in Simple Terms?

      A Trigger SIP links an investment action to a predefined condition. When that condition is met, the specified transaction is initiated according to the AMC’s rules.

    2. Does a Trigger SIP Guarantee Better Returns?

      No. Returns depend on market movements and the trigger selected. A trigger may provide a favourable entry in some situations, but it can also delay investing.

    3. What Types of Triggers Can Be Used?

      Depending on the AMC, triggers may be based on NAV, market indices, investment value, percentage appreciation or depreciation, or a specified date.

    4. Is Trigger SIP Suitable for Beginners?

      It can be more complex than a regular SIP because you need to choose and understand market-linked conditions. Beginners may find regular SIP investing easier to manage.

    5. Can I Cancel a Trigger SIP?

      Cancellation or modification rules depend on the AMC and scheme. Check the applicable mutual fund terms before changing an existing trigger instruction.

  • What Is EUIN in Mutual Fund: Meaning & Uses

    What Is EUIN in Mutual Fund: Meaning & Uses

    When you invest in a mutual fund through a distributor, you may notice ARN and EUIN fields on the application form. While ARN identifies the distributor, EUIN identifies the person involved in selling or distributing the mutual fund. Understanding the EUIN meaning can help you know why this small code matters for investor protection and accountability.

    What Is EUIN in Mutual Fund?

    The EUIN full form in mutual fund is Employee Unique Identification Number. It is a unique identification number allotted by the Association of Mutual Funds in India (AMFI) to eligible individuals involved in mutual fund distribution.

    It identifies the employee, relationship manager, salesperson, or other eligible individual associated with a mutual fund distributor who interacts with investors for selling mutual fund products.

    SEBI requires mutual funds to capture EUIN along with the distributor’s AMFI Registration Number (ARN) where applicable. The purpose is simple: if there is a complaint related to mis-selling or deficiency in service, the individual involved in the transaction can be identified.

    So, what is EUIN number in mutual fund? It is essentially an identification number connected to the individual rather than only the distribution firm.

    AMFI treats EUIN as a unique and permanent identity number. If an employee changes employment, the EUIN itself remains unchanged. However, it needs to be mapped to the ARN of the new employer.

    Why Was EUIN Introduced?

    A distributor’s ARN identifies the entity through which a mutual fund transaction is routed. However, a large distributor may employ many relationship managers and sales personnel.

    ARN alone would not tell you which person interacted with the investor. EUIN addresses this gap by identifying the individual associated with the transaction.

    The system helps with:

    • Identifying the person involved in selling or distributing a mutual fund.
    • Creating greater accountability in mutual fund distribution.
    • Helping trace complaints involving mis-selling or service deficiencies.
    • Maintaining an audit trail even when an employee changes employers.
    • Improving transparency for investors using distributors.

    SEBI introduced the EUIN requirement as an additional identification mechanism alongside ARN. It therefore does not replace ARN.

    EUIN vs ARN in Mutual Funds

    EUIN and ARN are both used in mutual fund distribution, but they identify different participants. ARN generally identifies the registered mutual fund distributor, while EUIN identifies the individual associated with the distribution activity.

    ParticularARNEUIN
    Full formAMFI Registration Number.Employee Unique Identification Number.
    Issued byAMFI.AMFI.
    IdentifiesMutual fund distributor.Individual employee, salesperson, relationship manager, or eligible individual.
    Main purposeIdentifies the registered distributor.Identifies the individual associated with the transaction.
    Used forMutual fund distribution.Tracking individual involvement in mutual fund distribution.
    Job changeBelongs to the registered ARN holder.Remains with the individual and can be mapped to a new employer’s ARN.

    Who Needs an EUIN?

    EUIN is relevant to people engaged in the sale or distribution of mutual fund products. Depending on the distribution structure, this can include:

    • Employees of mutual fund distributors involved in distribution.
    • Relationship managers interacting with mutual fund investors.
    • Sales personnel engaged in selling mutual fund products.
    • Eligible employees of banks or other non-individual distributors.
    • Individual mutual fund distributors, who are allotted EUIN with their ARN by default.

    Employees and sub-distributors involved in mutual fund distribution are required to meet applicable NISM certification and AMFI registration requirements.

    An investor does not need to obtain an EUIN merely to invest in mutual funds. EUIN relates to the distributor or individual involved in selling or distributing the product.

    How Is an EUIN Obtained?

    AMFI handles ARN and EUIN registration, with CAMS carrying out end-to-end registration and renewal activities.

    The broad process is:

    1. The applicant must meet the applicable NISM certification requirement.
    2. The applicant applies for EUIN through the AMFI online registration system.
    3. PAN and Aadhaar are required for the online application and authentication process.
    4. The required registration details and applicable fees are submitted.
    5. After successful registration, the EUIN is allotted.
    6. For employees, the EUIN is mapped to the relevant employer’s ARN.

    Individual mutual fund distributors are generally allotted EUIN along with ARN automatically, without a separate EUIN application or additional charge.

    AMFI registration through ARN or EUIN is generally valid for three years. Its validity for an individual is also co-terminus with the person’s applicable NISM certificate. Therefore, the required certification needs to remain valid for renewal.

    What Happens When an Employee Changes Their Job?

    The employee does not receive a completely new EUIN merely because they join another distributor.

    AMFI treats EUIN as a permanent identity number. When employment changes, the existing EUIN must be mapped to the ARN of the new employer through the prescribed process.

    This creates continuity. It also helps maintain a record of the periods during which the individual was associated with different ARN holders.

    Read Also: Stable Value Fund

    Where Is EUIN Used in a Mutual Fund Transaction?

    When a mutual fund investment is routed through a distributor, the application or transaction form generally contains fields for distributor information.

    Depending on the form, you may see:

    • ARN of the distributor.
    • Sub-distributor or related code, where applicable.
    • EUIN.
    • EUIN declaration where the EUIN field is intentionally left blank.

    SEBI requires the EUIN to be captured for relevant distributor-routed transactions. Investors should therefore check that the details entered on the form correctly reflect the person and distributor involved.

    Is EUIN Mandatory?

    Yes. EUIN is required where applicable when a transaction is routed through a distributor and an employee, relationship manager, salesperson, or other relevant person interacts with the investor.

    However, there can be situations where the EUIN box is intentionally left blank. For example, the investor may execute a transaction without interaction or advice from the distributor’s employee or salesperson.

    In such cases, the applicable declaration needs to be provided instead of simply leaving the field unexplained.

    What Does EUIN Declaration Mean?

    EUIN declaration means the investor confirms why the EUIN field has intentionally been left blank.

    A current mutual fund application may ask investors to confirm that the transaction was executed without interaction or advice from the employee, relationship manager, or salesperson of the distributor or sub-broker. The exact wording can vary across forms.

    For example, suppose you already know which mutual fund scheme you want. You approach a distributor only to execute the transaction and receive no recommendation from its employee. Where applicable, the EUIN field may be left blank and the prescribed declaration completed.

    The declaration therefore, establishes why an individual EUIN has not been quoted.

    What Happens If EUIN Is Missing or Incorrect?

    AMFI provides a remediation mechanism where EUIN is not mentioned in an application or electronic transaction feed along with the applicable ARN details.

    The concerned ARN holder can generally remediate the transaction within 30 days from the transaction date. This may be done by providing the correct EUIN or submitting the prescribed investor-signed declaration stating that EUIN was intentionally left blank.

    If the required EUIN or declaration is not provided within the prescribed period, the commission on the relevant purchase transaction can be permanently forfeited.

    This makes correct EUIN reporting important for distributors as well as investors.

    If you are investing through a distributor, check the information before submitting the application. A wrong EUIN could associate the transaction with someone who did not actually interact with you.

    Why EUIN Matters for Mutual Fund Investors

    EUIN may look like a minor administrative detail, but it serves a clear regulatory purpose. It makes mutual fund distribution more traceable at the individual level.

    • Helps Identify Who Interacted With You: A distributor may have hundreds or even thousands of employees. EUIN helps identify the particular person associated with your transaction rather than relying only on the firm’s ARN.
    • Supports Action Against Mis-Selling: Mis-selling can involve unsuitable recommendations, misleading statements, omitted material facts, or inadequate disclosure of risks. If a complaint arises, EUIN can help trace the person associated with the transaction.
    • Creates an Audit Trail: An employee may leave one distributor and join another. Since the EUIN remains associated with the individual, their identity does not disappear when employment changes.
    • Improves Accountability: The presence of an individual identification number creates an additional layer of accountability. Both the distributor and the individual associated with a transaction can be identified where applicable.
    • Makes Investor Records Clearer: ARN and EUIN together provide more information than either identifier alone. ARN tells you which distributor was involved, while EUIN can identify the relevant individual.

    Read Also: SIF Regulations in India

    Conclusion

    The EUIN full form is Employee Unique Identification Number. It helps identify the individual involved in mutual fund distribution and supports greater traceability in distributor-routed transactions.

    As an investor, you do not need to obtain an EUIN for yourself. However, knowing the EUIN meaning can help you understand the information recorded when you invest through a mutual fund distributor.

    With Pocketful, you can explore and invest in mutual funds digitally while keeping track of your investments from one platform. Always understand the scheme, its risks, and your investment objective before making an investment decision.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Smart SIP: Meaning, How It Works, Benefits & Risks
    2Power SIP: Meaning, How It Works, Benefits & Risks
    3Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    4Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works
    5What Is a Balanced Fund? Meaning, Benefits & Risks

    Frequently Asked Questions (FAQs)

    1. What is the EUIN full form in mutual funds?

      The EUIN full form in mutual fund is Employee Unique Identification Number. AMFI allots it to eligible individuals involved in mutual fund distribution.

    2. Is EUIN the same as ARN?

      No. ARN identifies the registered mutual fund distributor, while EUIN identifies the individual associated with the distribution activity. Both serve different identification purposes.

    3. Do mutual fund investors need an EUIN?

      No. Investors do not need to obtain an EUIN simply to invest in mutual funds. It applies to eligible individuals engaged in mutual fund distribution.

    4. What does an EUIN declaration mean?

      An EUIN declaration confirms why the EUIN field was intentionally left blank. It is used in applicable cases where the transaction occurs without the relevant interaction or advice from the distributor’s employee or salesperson.

    5. Does EUIN change when an employee changes jobs?

      No. EUIN is treated as a unique and permanent identity number. When an employee changes employers, the existing EUIN is mapped to the ARN of the new employer through the prescribed process.

  • What Is RIA in Mutual Fund? Meaning, Fees & RIA Code

    What Is RIA in Mutual Fund? Meaning, Fees & RIA Code

    RIA in mutual fund stands for Registered Investment Adviser. It is a person or entity registered with SEBI to provide investment advice. 

    An RIA charges clients for advisory services instead of earning commissions from the mutual fund products recommended. Read this guide to know the details.

    What Is RIA in Mutual Fund?

    A Registered Investment Adviser provides investment advice. It is based on your financial goals, risk profile, investment horizon, and financial position. RIAs operate under the SEBI Investment Advisers Regulations, 2013. It is along with subsequent amendments.

    SEBI requires an investment adviser to act in a fiduciary capacity towards clients. This means:

    • Customer interest is always first.
    • All conflicts should be disclosed.
    • Follow suitability requirements.

    RIA Full Form in Mutual Fund

    The RIA full form in mutual fund is Registered Investment Adviser. It can refer to an individual or an eligible entity registered under SEBI’s investment advisory framework.

    A mutual fund distributor operates differently. Distributors are registered with AMFI and generally use an AMFI Registration Number, or ARN, to distribute mutual funds. They may earn commissions through regular mutual fund plans.

    What Is RIA Code in Mutual Fund?

    If you are wondering what is RIA code in mutual fund, it generally refers to the SEBI registration number of the Registered Investment Adviser.

    You can use these registration details to verify whether an adviser is registered before paying for investment advice. An RIA’s SEBI registration number should not be confused with the ARN used by mutual fund distributors.

    Why Does This Difference Matter?

    The main difference comes down to the nature of the service and how it is paid for.

    An RIA charges you for providing investment advice. A mutual fund distributor may receive commissions linked to the regular mutual fund plans you purchase through them.

    Neither arrangement automatically tells you whether a particular investment is suitable. However, knowing the compensation model helps you understand potential conflicts and the cost of the service.

    RIA vs Mutual Fund Distributor

    RIAs and mutual fund distributors may both help investors with mutual funds, but their primary roles are different.

    FactorRIAMutual Fund Distributor
    RegistrationSEBI investment advisory framework.AMFI registration.
    Primary roleProvides investment advice.Distributes mutual funds.
    CompensationAdvisory fee paid by the client.May earn commission from regular plans.
    Mutual fund routeDirect plans can be used for advisory clients.Generally distributes regular plans.
    ResponsibilityFiduciary responsibility towards advisory clients.Follows applicable distribution rules.
    ConflictConflicts must be disclosed and managed.Commission structure can create potential conflicts.

    Direct mutual fund plans do not include distributor commissions and generally have lower expense ratios than corresponding regular plans. Regular plans include distribution-related expenses.

    This does not necessarily mean every investor should choose an RIA. If you need personalised financial advice, an adviser may be useful. If you only need help completing mutual fund transactions, your requirements may be different.

    Role and Responsibilities of an RIA

    An RIA does more than simply suggest a mutual fund. The exact responsibilities depend on the advisory agreement and services selected.

    Common responsibilities include:

    • Understanding your financial position and investment goals.
    • Assessing your willingness and ability to take risk.
    • Recommending investments suitable for your risk profile.
    • Helping structure investments around financial goals.
    • Reviewing investments when circumstances change.
    • Disclosing fees and relevant conflicts of interest.
    • Maintaining records related to advice and suitability.
    • Explaining risks associated with recommendations.

    Risk profiling is particularly important. An adviser needs to understand how much financial risk you can take and how comfortable you are with market fluctuations before making recommendations.

    Agreement Between an RIA and Client

    The advisory relationship is governed by an agreement between you and the RIA. It establishes what services you will receive and how the adviser will be compensated.

    The agreement generally covers:

    • Scope of advisory services.
    • Fees and payment terms.
    • Rights and responsibilities.
    • Risk profiling and suitability.
    • Conflict-of-interest disclosures.
    • Termination conditions.
    • Grievance and dispute resolution.

    Reading the agreement can prevent misunderstandings later.

    Read Also: RIAs vs MFDs: Who Is Better?

    Who Can Become an RIA?

    A person who is in the business of providing investment advice for consideration generally needs registration under SEBI’s Investment Advisers framework unless an exemption applies.

    Certain professionals and intermediaries can provide incidental investment advice without separate RIA registration under specified circumstances. For example, a mutual fund distributor may provide advice that is incidental to their primary distribution activity.

    Therefore, discussing mutual funds does not automatically make someone a Registered Investment Adviser.

    Eligibility to Become an RIA

    SEBI sets qualification, certification, deposit, and other requirements for investment advisers.

    The framework changed significantly in December 2024. Specified graduate and postgraduate qualifications in areas such as finance, commerce, economics, banking, insurance, business management, and related fields can satisfy the educational requirements.

    Relevant NISM certification is also required and must remain valid.

    The earlier five-year experience requirement for individual investment advisers and principal officers was removed. The previous minimum net-worth requirements were also replaced by a deposit-based system.

    The current deposit requirement depends on the adviser’s number of clients:

    Number of ClientsMinimum Deposit
    Up to 150₹1 lakh.
    151 to 300₹2 lakh.
    301 to 1,000₹5 lakh.
    More than 1,000₹10 lakh.

    These changes are worth noting because older information about RIA eligibility may still mention the previous ₹5 lakh and ₹50 lakh net-worth requirements.

    RIA Fee Structure Under SEBI Rules

    SEBI regulates the fees investment advisers can charge individual and HUF clients. Two primary fee models are available.

    1. AUA Model

    Under the Assets Under Advice model, the maximum fee is 2.5% of AUA per annum per family of client.

    Suppose your Assets Under Advice are ₹40 lakh and your RIA charges 1% annually. Your annual advisory fee would be:

    ₹40,00,000 × 1% = ₹40,000

    The actual rate can be lower than the maximum limit based on your agreement with the adviser.

    2. Fixed-Fee Model

    Under the fixed-fee model, an adviser can charge up to the applicable annual regulatory ceiling per family of client. The ceiling was revised to ₹1,51,000 under the updated framework and can be adjusted periodically using the Cost Inflation Index.

    The earlier restriction preventing an adviser from changing the fee mode for 12 months has also been removed.

    3. RIA Fees vs Distributor Costs

    An RIA fee is usually easier to identify because you pay the advisory charge directly.

    A distributor may not send you a separate advisory bill. Instead, commissions may form part of the expenses of a regular mutual fund plan. This is one reason regular plans generally have higher expense ratios than their direct-plan counterparts.

    When comparing the two, look at the total cost as well as the service you receive. An investor who needs comprehensive financial planning may have different requirements from someone comfortable researching and managing investments independently.

    RIA Full Form in Banking

    The RIA full form in banking is also generally Registered Investment Adviser. The meaning does not change simply because the service is connected with a bank.

    However, banks can provide investment-related services through different arrangements. A bank may distribute mutual funds while investment advisory services are offered under an appropriately registered and segregated structure.

    Therefore, a mutual fund recommendation from someone working at a bank should not automatically be treated as RIA advice.

    Before investing, ask:

    • Is this an advisory or distribution service?
    • What registration applies?
    • Who pays for the service?
    • Is the mutual fund a direct or regular plan?
    • What fees or commissions apply?

    These questions make the compensation and service structure much easier to understand.

    How to Choose an RIA

    Registration is an important starting point. But the things that you should know are:

    1. Verify SEBI Registration: Check whether the person or entity is registered to provide investment advisory services. Do not rely only on social media profiles or claims of being a financial expert.
    2. Understand the Fees: Ask how the advisory fee is calculated and what services are included. The cost should be clear before you enter the advisory relationship.
    3. Check the Scope of Services: Some advisers focus mainly on investment portfolios, while others provide broader financial planning. Choose according to the support you actually require.
    4. Understand the Advisory Process: Ask how recommendations are selected. Your goals, liabilities, existing investments, time horizon, and risk profile should form part of the assessment.
    5. Avoid Guaranteed Returns: RIA registration does not remove investment risk. Be cautious of anyone promising guaranteed market returns or presenting future investment performance as certain.
    6. Read the Agreement: Review fees, services, responsibilities, termination conditions, and grievance procedures before signing the advisory agreement.

    Read Also: Stable Value Fund: Meaning, Benefits, Risks & How It Works

    Final Thoughts

    Understanding what is RIA in mutual fund investing helps you know who is providing advice and helps you invest better. If you prefer researching and managing investments yourself, Pocketful can help. Open a demat account here and get the details you need. Analyse your goals, risk, and return needs and invest better.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1SIF Regulations in India
    2Smart SIP: Meaning, How It Works, Benefits & Risks
    3Power SIP: Meaning, How It Works, Benefits & Risks
    4Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid
    5What is STP in Mutual Funds?

    Frequently Asked Questions (FAQs)

    1. What Is RIA Full Form in Mutual Fund Advisory?

      The RIA full form in mutual fund advisory is Registered Investment Adviser. It refers to an individual or eligible entity registered under SEBI’s Investment Advisers framework to provide investment advice.

    2. How Is an RIA Different From a Mutual Fund Distributor?

      An RIA primarily provides investment advice and charges clients advisory fees. A mutual fund distributor primarily distributes mutual fund schemes and may earn commissions associated with regular plans.

    3. What Fee Can an RIA Charge?

      For applicable individual and HUF clients, an RIA can use the AUA or fixed-fee model within SEBI’s prescribed limits. Under the AUA model, the maximum fee is 2.5% per annum per family of client.

    4. What Is RIA Code in Mutual Fund Documents?

      The phrase what is RIA code in mutual fund generally refers to the SEBI registration details of a Registered Investment Adviser. Investors can use these details to verify the adviser’s registration status.

    5. Does RIA Mean Something Different in Banking?

      No. The RIA full form in banking generally remains Registered Investment Adviser. However, banks can provide both advisory and distribution services, so check which type of service you are receiving.

  • Open Free Demat Account

    Join Pocketful Now

    You have successfully subscribed to the newsletter

    There was an error while trying to send your request. Please try again.

    Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.