Category: Mutual Funds

  • Power SIP: Meaning, How It Works, Benefits & Risks

    Power SIP: Meaning, How It Works, Benefits & Risks

    If you regularly invest via SIP, hearing the term “Power SIP” might make you wonder how it differs from a standard SIP. How exactly is the investment amount determined, and is it the right choice for you? In this blog, we will explain Power SIP in simple terms and take a look at how it works and the key points to consider.

    What is Power SIP? 

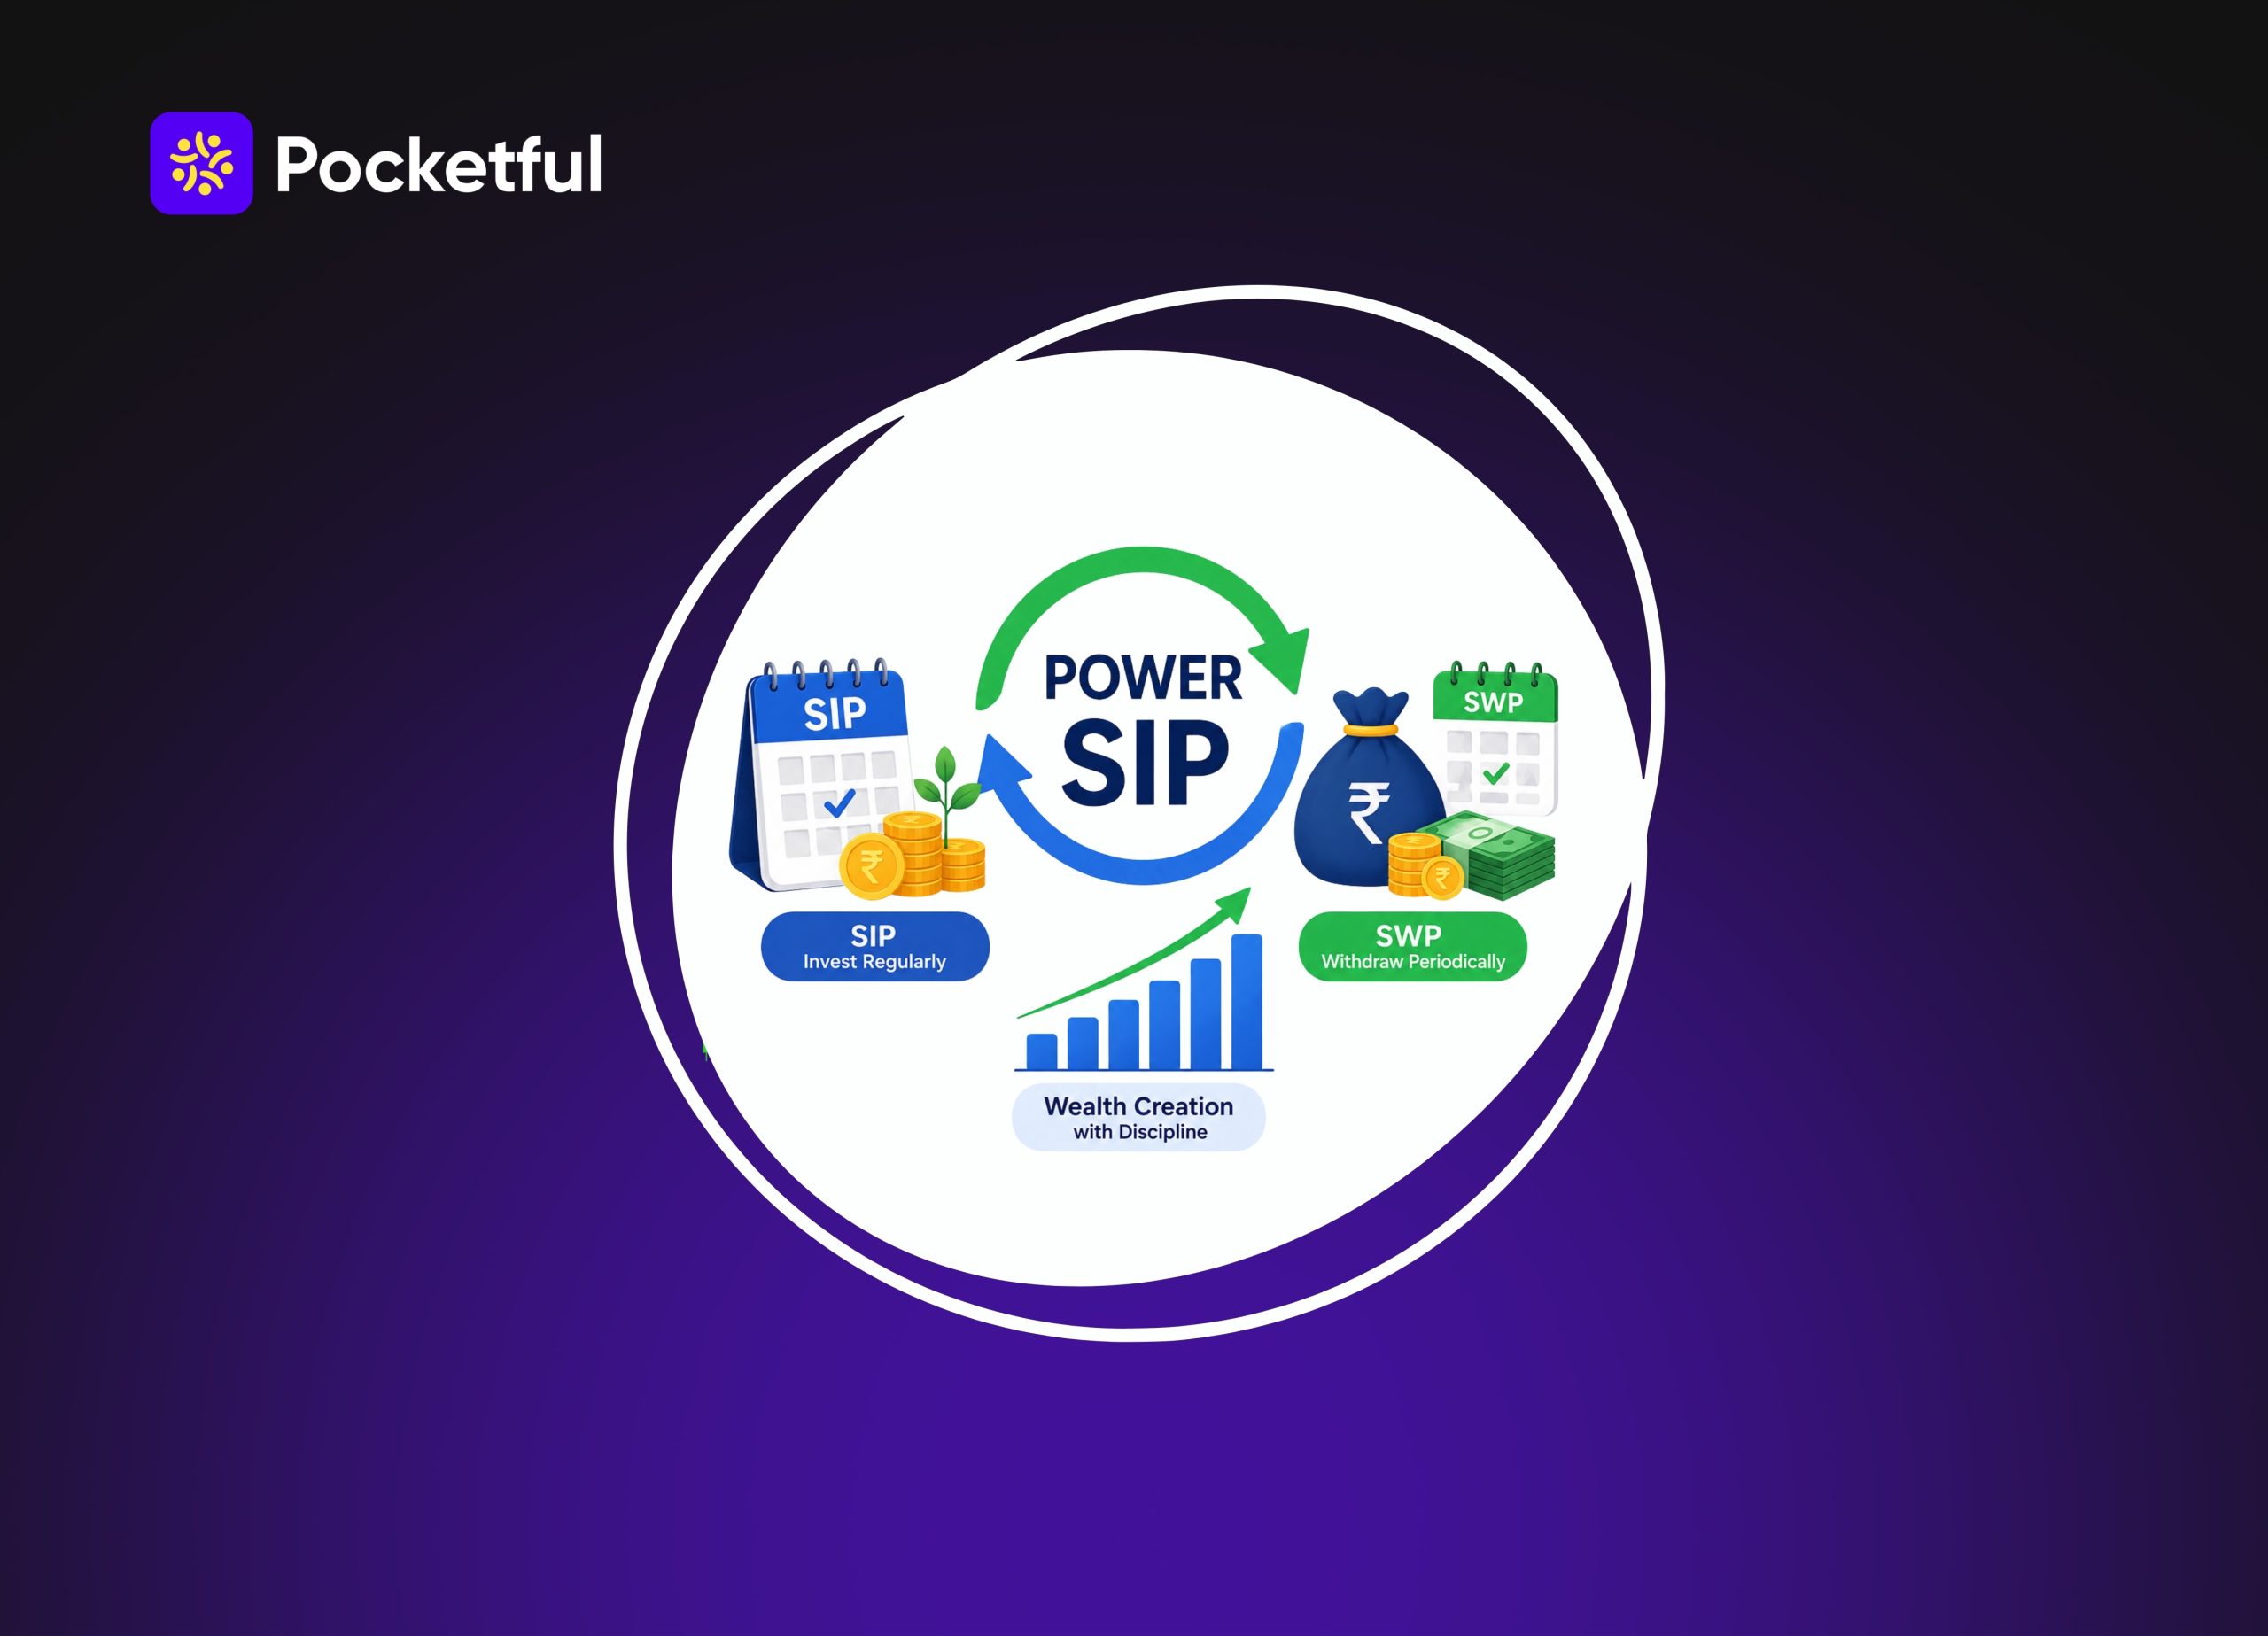
    Power SIP is a mutual fund facility that integrates SIP and SWP into a pre-planned structure. Simply put, an investor first invests money through regular SIPs for a specified period. Once the SIP tenure concludes, an SWP can be initiated based on predetermined rules, allowing for regular withdrawals from the same investment. Mahindra Manulife Mutual Fund’s official Power SIP facility is based on this SIP-cum-SWP structure.

    Example: Suppose a person invests ₹10,000 monthly via an SIP for 10 years, with the aim of gradually increasing their investment over this period. With ‘Power SIP’, once the SIP tenure concludes, a monthly SWP (Systematic Withdrawal Plan) can be initiated from the accumulated investment, based on the pre-selected option and applicable terms. In other words, the first phase involves accumulating funds, while the subsequent phase allows for regular withdrawals from that same corpus.

    How Does Power SIP Work? 

    In Power SIP, investment is first made through a SIP, and upon completion of the specified tenure, an SWP can be initiated in accordance with the rules of the chosen facility.

    Step 1: Select SIP and SWP

    When initiating a Power SIP, the SWP facility is selected alongside the SIP in an eligible mutual fund scheme. Both can be set up within the same scheme or across different eligible schemes.

    Step 2: Determine the SIP tenure

    The investor makes monthly SIP investments for their chosen duration. Mahindra Manulife’s Power SIP facility offers a predefined SIP tenure ranging from 8 to 30 years.

    Step 3: Investment accumulation via SIP

    Throughout the chosen tenure, the SIP amount is invested monthly, and mutual fund units are accumulated in the investor’s name.

    Step 4: Transition after SIP tenure completion

    If the SIP and SWP have been selected for different schemes, a portion of the accumulated units is switched to the target scheme designated for the SWP, in accordance with the facility’s rules.

    Step 5: Commencement of regular SWP

    Once the SIP tenure concludes, the SWP begins as per the established rules. Under the Power SIP, the SWP date is typically linked to the chosen SIP date, and withdrawals take place on a monthly basis.

    Note: Power SIP rules may vary by AMC. Therefore, please read the official terms of the specific facility before investing. Mutual fund returns and the corpus remaining after the SWP depend on market performance.

    Power SIP vs Regular SIP 

    Investments in both Regular SIP and Power SIP begin with an SIP. However, Power SIP may also include an SWP facility following the SIP, based on a pre-determined structure.

    BaseRegular SIPPower SIP
    Investment methodA fixed amount is invested at regular intervals.The SWP facility is also registered alongside the SIP.
    Main ObjectiveGradually building an investment corpusInvesting first and planning for regular withdrawals later
    Investment periodAn investor can continue the SIP according to their needs.The available facility may include a pre-determined SIP tenure.
    After the investmentThe investor can separately choose further investments, redemptions, or SWPs.Upon completion of the SIP tenure, an SWP can be initiated based on the selected facility.
    Selection of SchemeAn SIP is undertaken in a selected scheme.SIP and SWP can be in the same or different eligible schemes.
    Suitable for whom?For those who wish to invest regularlyFor those who wish to plan for both investment and regular future withdrawals.
    Guarantee of returnThere is no guarantee.There is no guarantee.

    Why Do Investors Consider Power SIP? 

    Power SIP can be beneficial for investors who wish to plan for future regular withdrawals alongside their investments.

    • Better Financial Planning: It allows investments and future withdrawals to be viewed as a structured plan, simplifying long-term planning.
    • Goal-Based Planning: It helps in planning the investment journey for goals such as retirement or securing a regular future income.
    • Planning for Regular Income from the Corpus: One can plan to build a corpus through SIPs initially and subsequently arrange for regular withdrawals from that same investment.
    • Ease of Managing Different Stages: If the facility offers an integrated SIP and SWP structure, the need to set up withdrawals separately at a later stage may be eliminated.
    • Useful for Long-Term Investors: It serves as a practical option for individuals aiming to invest over the long term and utilize the accumulated corpus at a later date.

    Read Also: What Is Stock SIP?

    Benefits of Power SIP 

    The key advantage of a Power SIP is that it allows for planning that considers future financial needs alongside the investment itself. However, specific features may vary depending on the service provider.

    • Better Financial Planning: It enables you to plan for both the initial investment via SIP and the future utilization of the accumulated corpus. This leads to more organized long-term financial planning.
    • Preparing for Future Income: If an individual anticipates a need for regular income in the future, they can plan for withdrawals in advance alongside their investment strategy.
    • Goal-Oriented Planning: Investments intended for retirement or other long-term requirements can be aligned with future fund utilization under a single, unified plan.
    • Fostering Investment Discipline: Regular SIPs cultivate a long-term investment habit and provide a disciplined approach to building a corpus.
    • Ease of Planning: By factoring in both SIP contributions and future withdrawal needs at the outset, one can formulate an investment strategy that simplifies future financial decision-making.

    Risks and Limitations of Power SIP 

    Before starting a Power SIP, it is important to understand its practical risks and limitations. This facility may not be suitable for every investor.

    • Market risk persists: Since Power SIP investments are made in mutual funds, the NAV and the investment value can fluctuate based on market performance.
    • The future corpus is not guaranteed: Market returns are not predetermined. Therefore, it is impossible to accurately estimate the final corpus amount upon the completion of the SIP.
    • SWP can deplete the corpus: When regular withdrawals begin, the number of redeemed units decreases. If there is no proper balance between the withdrawal rate and fund performance, the corpus can deplete rapidly.
    • Features vary across providers: The structure, tenure, and rules regarding switching and withdrawals for Power SIPs can differ depending on the provider. Therefore, one should not assume the features based solely on the name.
    • Understanding early exit rules is crucial: Before stopping the SIP, switching schemes, or redeeming the investment, it is essential to understand the applicable exit loads, lock-in periods, and tax implications.

    Who Should Consider a Power SIP? 

    Before opting for a Power SIP, it is important to assess whether its investment and future withdrawal planning align with your financial needs.

    • Investors with Long-Term Financial Goals: It may be suitable for individuals looking to build a corpus for a future goal through long-term investment.
    • Individuals Planning for Retirement: Those who wish to invest regularly during their working years and plan for a steady income from the accumulated corpus later on might consider this option.
    • Investors Requiring Future Regular Income: If there is a likelihood of needing funds monthly or at fixed intervals in the future, this structure can assist with financial planning.
    • Disciplined Investors: This approach can be more practical for individuals who can invest consistently over a set period and do not prematurely halt their investments unless there is an actual need.

    Things to Check Before Starting a Power SIP 

    Simply looking at the features of a Power SIP is not enough before starting one. Understanding a few key aspects will help you make a decision that best suits your needs.

    • Understand the Underlying Mutual Fund: Do not choose a fund based solely on the Power SIP feature. Make sure to examine the fund’s investment objective, portfolio, and risk level.
    • Know the SIP and Withdrawal Rules: Understand the required investment tenure and the rules governing withdrawals later on.
    • Assess Your Financial Capacity: Set an SIP amount that you can comfortably sustain over the long term. Do not invest money meant for essential expenses or your emergency fund.
    • Check Exit and Tax Rules: Early redemption may attract an exit load. It is also important to understand the tax rules applicable to withdrawals.
    • Read the Terms and Conditions: The structure of a Power SIP can vary across providers; therefore, ensure you check all applicable rules before getting started.

    Common Myths About Power SIP 

    There are several common misconceptions regarding Power SIPs. It is important to have accurate information so that investment decisions are not based solely on the name or marketing claims.

    Myth: Power SIPs offer higher returns

    A Power SIP does not automatically guarantee higher returns. Returns primarily depend on the underlying mutual fund and market performance.

    Myth: It is a distinct mutual fund category

    A Power SIP is generally an investment facility or structure, not a separate mutual fund category. Its features may vary depending on the service provider.

    Myth: It carries no risk

    The underlying investment in a Power SIP can be market-linked. Therefore, the NAV and the value of the investment are subject to fluctuation.

    Myth: All Power SIPs are the same

    This is not necessarily true. Terms regarding the investment period, withdrawals, and other rules can vary across different providers.

    Myth: Future withdrawals will always be fixed

    The amount available for withdrawal in the future depends on the accumulated corpus, market performance, and the specific withdrawal plan. Therefore, it should not be viewed as guaranteed income.

    Read Also: Micro SIP in Mutual Funds: Meaning, Benefits, Features & How to Start

    Conclusion

    Power SIP can help you plan your investments and future withdrawals in a disciplined, goal-oriented, and structured manner, allowing you to build wealth gradually while maintaining flexibility for future needs. It can be particularly useful for long-term financial planning, as it encourages consistency and helps navigate market fluctuations over time. However, before investing, it is important to thoroughly understand how Power SIP works, including its terms, conditions, potential risks, and the characteristics of the underlying fund, so you can make informed decisions that align with your financial goals and risk appetite.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Top-up SIP?
    2What Is SWP in Mutual Funds?
    3How to Increase SIP Amount: Smart Strategies
    4Practical Tips for Investing in Mutual Funds for Beginners
    5Best Brokers for Mutual Funds

    Frequently Asked Questions (FAQs)

    1. What is Power SIP?

      Power SIP allows future withdrawal planning along with SIP.

    2. How does Power SIP work?

      First, an investment is made through SIP; then withdrawal planning can be done as per the prescribed structure.

    3. Is Power SIP the same as a regular SIP?

      No, a regular SIP focuses only on investment, whereas Power SIP also allows future withdrawal planning.

    4. Is Power SIP a mutual fund?

      No, it is usually an investment facility or structure.

    5. Does Power SIP guarantee returns?

      No, returns depend on fund and market performance.

  • Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid

    Mutual Fund Churning: Meaning, Causes, Risks & How to Avoid

    Many investors frequently switch funds in hopes of better returns. While making changes when necessary can be appropriate, constant buying and selling without a solid reason can lead to “mutual fund churning,” which may adversely affect the investment strategy. In this blog, we will explore what churning is, how it happens, and how to avoid it. SEBI also advises aligning investments with one’s financial goals and risk appetite.

    What Is Mutual Fund Churning? 

    Mutual fund churning refers to the excessive or unjustified frequent buying, selling, or switching of mutual fund investments. This can manifest as an investor constantly moving money between different schemes. Meanwhile, the buying and selling of securities within a fund is measured by the Portfolio Turnover Ratio (PTR). According to SEBI, high portfolio turnover can lead to increased brokerage and other transaction costs.

    Understand Mutual Fund Churning Simply

    Suppose an investor invests in an equity mutual fund. A few months later, they switched to another fund solely because of its better recent returns. Then, when the next fund performs well, they switch again. If these changes occur repeatedly without a clear investment-related reason, it can be considered unnecessary churning.

    SituationGeneral changesPotential Churning
    Reason for changing the fundActual change in goal or strategySwitching based solely on recent returns.
    Decision-making processAfter careful reviewRepeatedly and in haste
    Portfolio activityAs neededExcessive transactions
    Investor focusLong-term investment planShort-term performance

    Types of Mutual Fund Churning 

    Mutual fund churning can occur primarily at two levels: the fund portfolio level and the investor level. While both involve a high volume of transactions, the nature of these transactions differs.

    1. Portfolio-Level Churning

    At this level, the fund manager buys and sells shares or other securities within the scheme’s portfolio. High portfolio turnover can be normal for certain funds due to their investment strategies; therefore, high trading activity alone does not necessarily imply improper practice.

    2. Investor-Level Churning

    This occurs when the investor frequently switches funds or redeems investments across different mutual fund schemes. When such changes are made without regard to investment goals, risk profiles, or other valid reasons, it can amount to unnecessary churning.

    3. Not Every Fund Change Constitutes Churning

    Modifying your portfolio is appropriate if your financial needs, goals, or risk appetite have changed. SEBI also advises investors to align their investments with their objectives and risk appetite, and to periodically review their financial goals.

    How Does Mutual Fund Churning Work? 

    Mutual fund churning occurs when an investor repeatedly switches funds without a valid reason. This process typically unfolds as follows

    Step 1: Investing in a Mutual Fund

    An investor puts money into a mutual fund with a specific goal in mind or in anticipation of better returns.

    Step 2: A Short-Term Trigger Occurs

    After some time, the fund’s performance appears to dip, the market falls, or another fund seems to offer better returns. This is where the idea of ​​switching arises.

    Step 3: The Fund is Redeemed or Switched

    The investor withdraws money from the current fund or switches it to invest in a different scheme. According to SEBI regulations, a ‘switch-out’ is treated as a redemption, while a ‘switch-in’ is treated as a purchase.

    Step 4: A New Fund is Selected

    Often, the new fund is chosen based on its recent performance or ranking, without verifying whether it is truly better suited to the investor’s investment goals.

    Step 5: The Process Repeats

    After a while, the new fund may fail to perform as expected, or a third fund might appear more attractive. Another switch occurs, and this cycle of repeated activity can turn into mutual fund churning.

    Read Also: Top Reasons Why Mutual Funds Are Going Down

    What Is Portfolio Turnover Ratio in Mutual Funds? 

    The Portfolio Turnover Ratio (PTR) indicates how frequently securities within a mutual fund’s portfolio are bought and sold over a specific period. It helps in understanding the fund’s trading activity. SEBI mandates the disclosure of PTR for equity-oriented schemes.

    Understanding the Portfolio Turnover Ratio in simple terms

    A high PTR generally implies significant buying and selling activity within the portfolio, whereas a low PTR may indicate relatively fewer changes. However, a fund cannot be judged as good or bad based solely on its PTR.

    Is a high PTR always bad?

    No. In some actively managed funds, the fund manager may make significant changes to the portfolio based on investment opportunities or shifting market conditions. On the other hand, trading in index funds is primarily driven by changes in the index or fund flows. Therefore, it is important to evaluate the PTR in the context of the fund’s strategy.

    Fund TypeHow to understand PTR
    Index FundGenerally, limited changes to the portfolio may occur, such as those resulting from index adjustments.
    Active Equity FundThe PTR can be higher due to stock selection.
    Long-Term Strategy FundIt is important to understand the fund’s strategy when the Portfolio Turnover Ratio (PTR) is very high.
    Debt FundChanges may occur due to maturity, interest rate, and credit strategy.
    Tactical FundIncreased trading could be part of the fund’s stated strategy.

    Mutual Fund Churning vs Normal Portfolio Rebalancing 

    Both involve changes to the investment portfolio; however, ‘mutual fund churning’ often entails changes made without a valid reason, whereas portfolio rebalancing is undertaken to maintain a defined investment strategy.

    BaseMutual Fund ChurningNormal Portfolio Rebalancing
    Main ObjectiveFrequent fund changes, often without apparent needRebalancing the portfolio according to the defined asset allocation.
    Basis of the decisionRecent returns, market noise, or emotional reactions.Investment goals, risk level, and asset allocation
    Method of changeFrequent and unplannedAs per need or scheduled review.
    When is it done?If another fund looks betterWhen the portfolio allocation changes from the prescribed limit
    Impact on investment strategyThe long-term plan may change repeatedly.It helps maintain the original investment plan.

    Why Does Mutual Fund Churning Happen? 

    There can be several reasons for mutual fund churning, but it often stems from frequently changing investment decisions without having complete information.

    • Impact of Fund Rankings: Investors might immediately switch to a fund that appears to be performing better based on new rankings, without realizing that rankings fluctuate over time.
    • Acting on Recommendations Without Verification: Sometimes, investors switch funds based on someone’s advice without considering whether the move is actually suitable for their portfolio.
    • Ease of Switching: Switching funds has become easy thanks to online platforms. However, this convenience can often lead to an excessive number of transactions.
    • Lack of Awareness Regarding Costs: Some investors fail to check factors like exit loads and tax implications before switching. Therefore, it is crucial to understand the total cost involved before making any changes.

    What Are the Effects of Mutual Fund Churning? 

    Frequent mutual fund churning can impact not only the volume of transactions but also the overall efficiency of the investment.

    • Additional Costs: Excessive buying and selling within the fund can drive up brokerage and other transaction costs, which may negatively affect returns.
    • Exit Load and Tax Impact: Some schemes may levy an exit load on redemptions made before a specified period. Additionally, switching funds may be treated as a redemption for tax purposes.
    • Impact on Compounding: Frequent withdrawals or changes in strategy prevent the investment from having sufficient time to grow over the long term.
    • Decisions made at the wrong time can be costly: Redeeming in haste can prevent an investor from benefiting from a market recovery or the fund’s future performance.

    Conclusion

    Changing mutual funds isn’t always wrong, but constantly switching solely based on seemingly better returns is not the right approach either. To avoid ‘mutual fund churning,’ investors should understand the reason behind any change before making it. The right decision is one that aligns with your investment goals and needs.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Trail Commission in Mutual Funds?
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. What is Mutual Fund Churning?

      Mutual fund churning refers to the frequent buying, selling, or switching of mutual funds without a valid reason.

    2. Is switching mutual funds always bad?

      No; if your financial goals, risk profile, or the fund’s strategy have changed, switching might be the right move.

    3. What is Portfolio Turnover Ratio?

      It indicates how frequently the fund manager has bought and sold the securities within the portfolio over a specific period.

    4. Does a high Portfolio Turnover Ratio mean a bad fund?

      Not necessarily. Some actively managed funds may have a high PTR due to their specific investment strategy.

    5. Can Mutual Fund Churning affect returns?

      Yes; frequent transactions can increase costs and impact the investment plan.

  • Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works

    Dividend Reinvestment Plan (DRIP): Meaning, Benefits & How It Works

    A dividend reinvestment plan, or DRIP, is an automatic system that allows you to purchase additional shares or mutual funds from the dividends that you earn. The dividend is not cashed out here.

    The amount you earn as a dividend is reinvested so that it can grow over time for you. This is where you get the benefit of compounding as well. 

    The dividend under a dividend reinvestment plan is treated as an automatic investment plan that saves time and ensures your wealth grows over time. As an investor, knowing and understanding DRIP is very important. So, read this guide to know the details you need.

    What Is a Dividend Reinvestment Plan?

    A dividend reinvestment plan (DRIP) is an investment facility that automatically uses the dividends to earn additional units of stock. This is something that works on its own once you set the plan in motion. 

    You know that when a dividend is announced, investors get money in their accounts. But when you register in the DRIP, the same amount helps you to buy additional shares. Now these shares will grow with your existing shares and offer you compounding benefits. 

    This is in mutual funds as well. Here, the distributed amount can be reinvested to purchase additional units under the IDCW Reinvestment option.

    This allows your investment to grow and build wealth.

    Key Features of a Dividend Reinvestment Plan

    FeatureDescription
    Automatic reinvestmentDividends are used to purchase additional shares or units automatically.
    No manual investingInvestors do not need to reinvest every dividend themselves.
    CompoundingFuture dividends are earned on the increased investment.
    Long-term focusBest suited for investors with a longer investment horizon.
    Flexible availabilityOffered by companies, brokers, and mutual funds, depending on the product.

    Why Do Investors Choose Dividend Reinvestment?

    Dividend reinvestment allows investors to have steady growth of their investment without actually being involved a lot. The fund offers you better returns than the usual minimum value you get by placing money in your savings account. 

    Some common reasons include:

    • Building wealth through compounding
    • Increasing ownership without investing additional money
    • Maintaining investment discipline
    • Automating the investment process
    • Avoiding the need to manually purchase additional shares

    This is a great long-term strategy for investors who do not need funds or are rather saving for the future.

    How Does a Dividend Reinvestment Plan Work?

    The process behind a dividend reinvestment plan is fairly straightforward. Whenever a company or mutual fund declares a dividend, eligible investors receive the benefit based on the number of shares or units they own. Instead of receiving the amount in cash, the dividend is automatically used to purchase additional shares or units.

    Working of a Dividend Reinvestment Plan

    StepWhat Happens
    Dividend is declaredThe company or mutual fund announces a dividend.
    Record date is fixedEligible shareholders or unit holders are identified.
    Dividend amount is calculatedBased on the number of shares or units held.
    Dividend is reinvestedAdditional shares or units are purchased automatically.
    Portfolio growsFuture dividends are calculated on the increased holding.

    Example of a Dividend Reinvestment Plan

    Say you have 300 shares of Company A. Now, the company announces a dividend of ₹8 per share.

    Your total dividend works out to:

    300 × ₹8 = ₹2,400

    Now, say that the market price of the shares is ₹240. If you have DRIP active, you will get 10 additional shares.

    Your holding increases from 300 shares to 310 shares without making any fresh investment.

    So, now the next time the dividend is announced, you will get even more. You can invest this as well and create a chain of compounding that will grow for you.

    Types of Dividend Reinvestment Plans

    Although the concept remains the same, dividend reinvestment plans can differ depending on who offers them.

    1. Company-Sponsored Dividend Reinvestment Plans

    Some listed companies provide their own dividend reinvestment programme to shareholders.

    These plans generally allow investors to:

    • Automatically reinvest dividends.
    • Purchase additional shares directly.
    • Enroll voluntarily before participating.

    In certain global markets, companies may even offer shares at a discounted price under these programmes.

    2. Broker-Sponsored Dividend Reinvestment Plans

    Several brokerage platforms provide automatic dividend reinvestment as an account feature. This allows the broker to purchase on behalf of the client with the least intervention.

    This simplifies the investment process, especially for long-term investors who prefer automation over manually placing buy orders after every dividend payment.

    3. IDCW Reinvestment in Mutual Funds

    In mutual funds, dividend options are now known as Income Distribution cum Capital Withdrawal (IDCW).

    If you select the IDCW Reinvestment option:

    • The distributable amount is not credited to your bank account.
    • It is automatically invested in the same scheme.
    • Additional mutual fund units are allotted based on the applicable NAV.

    Although the terminology has changed, the underlying principle remains similar to a dividend reinvestment plan.

    4. Optional Dividend Reinvestment

    The choice to select between dividend cash-out and reinvestment is offered to investors. This is through companies and brokers alike. This flexibility allows the investors to decide what they want. This is very good for retirees, as this allows them to pay out when needed. 

    Factors That Influence Dividend Reinvestment

    Not every dividend payment results in the same number of additional shares or units. Several factors determine how much gets reinvested.

    Some of the key factors that you should know are as follows:

    • Dividend amount declared by the company
    • Current market price of the stock
    • Applicable NAV in mutual funds
    • Number of shares or units already held
    • Reinvestment option selected by the investor

    Common Misconceptions About Dividend Reinvestment

    Many new investors can get confuse on what the DRIP is all about. This is where you should get clarity on certain common myths as follows:

    MythReality
    Dividend reinvestment gives free shares.Shares are purchased using your own dividend amount.
    Reinvestment guarantees higher returns.Returns still depend on market performance.
    Dividends become tax-free if reinvested.Tax rules may still apply depending on prevailing regulations.
    Every company offers DRIPs.Availability varies across companies and brokers.
    Reinvestment removes investment risk.Market risk remains even after reinvestment.

    Who Should Choose a Dividend Reinvestment Plan?

    A dividend reinvestment plan may not be perfect for all investors. This means that you should understand your goals and needs well before you decide to go ahead with them. 

    Here are some aspects that can help you decide if the DRIP is good for you or not:

    Investor TypeIs a DRIP Suitable?Reason
    Long-term investorsYesHelps maximise compounding over time.
    Young investorsYesA longer investment horizon allows compounding to work effectively.
    Retirement corpus buildersYesSupports gradual wealth accumulation.
    Passive investorsYesAutomatic reinvestment requires minimal effort.
    Income-focused investorsNoCash dividends may better meet regular income needs.
    Short-term tradersNoLimited benefit over a short investment period.

    Before choosing a DRIP, consider what your priority is and what you need the money for. This will help you gain a better insight into which option is good for you. 

    Things to Consider Before Choosing a Dividend Reinvestment Plan

    While a dividend reinvestment plan is perfect for long-term investing, here are some factors that you should consider before you start to decide on:

    • Investment objective: Choose reinvestment if your primary goal is long-term capital appreciation rather than regular income.
    • Dividend history: Companies with a consistent record of paying dividends are good for DRIP. So, ensure you check the same.
    • Financial strength: Review the company’s fundamentals before relying on dividend income for reinvestment.
    • Tax implications: Reinvested dividends may still be taxable under the applicable tax laws.
    • Portfolio diversification: Avoid allowing one stock to become an excessively large portion of your portfolio through repeated reinvestment.
    • Liquidity needs: If you expect to need cash in the near future, receiving dividends directly may be a better option.

    Review your investments periodically to ensure your chosen dividend option continues to support your financial goals.

    How to Invest Through Pocketful

    Investing in dividend-paying stocks and mutual funds through Pocketful is simple. You will need to follow the steps below:

    1. Download the Pocketful app or sign up on the website.
    2. Open a free demat and trading account.
    3. Complete your KYC verification.
    4. Add funds to your trading account.
    5. Research dividend-paying stocks or mutual funds using Pocketful’s tools.
    6. Place your buy order and start building your portfolio.
    7. Track your investments regularly.
    8. Make changes as needed and ensure that you align with your goals.

    Conclusion

    A dividend reinvestment plan is a practical option for investors who want to grow their wealth through the power of compounding. This process is automatic, which means the investor intervention needed is very low.

    But when you decide to start with DRIP, you must ensure that you are well aware of your goals and also the dividend value that you wish to reinvest. To select such companies, you need the right information. Pocketful provides a easy platform to research, invest, and manage your portfolio with ease. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Best Long-Term Mutual Funds to Invest in India
    210+ Best Investment Plan for Monthly Income in India
    3Best Gilt Mutual Funds in India
    4Best Precious Metal Mutual Funds to Invest in India
    5Best SWP for Monthly Income in India

    Frequently Asked Questions (FAQs)

    1. What is a dividend reinvestment plan?

      A dividend reinvestment plan automatically uses dividends to purchase additional shares or mutual fund units. This helps with compounding.

    2. Is a dividend reinvestment plan better than receiving cash dividends?

      It depends on your financial goals. Reinvestment is generally suitable for long-term wealth creation, while cash dividends may be preferable if you need regular income.

    3. Is the dividend taxable under a dividend reinvestment plan?

      Yes. Reinvested dividends are taxed according to the rules, even when they are not cashed out. Check with an expert before planning ahead.

    4. Can I switch from dividend reinvestment to cash payouts?

      In many cases, yes. The availability of this option depends on the company, broker, or mutual fund offering the dividend facility.

    5. Who should opt for a dividend reinvestment plan?

      Long-term investors who want to benefit from compounding and do not require immediate dividend income are generally the most suitable candidates for a dividend reinvestment plan.

  • What Is a Balanced Fund? Meaning, Benefits & Risks

    What Is a Balanced Fund? Meaning, Benefits & Risks

    When it comes to investing, it is always advisable not to put all your eggs in one basket; that is, to diversify your funds across different assets. However, investing separately in equity and debt requires a huge amount of money. But the balanced fund has solved this problem, through which an investor can get direct exposure to equity and debt through a single investment.

    Today, we will give you an overview of balanced funds and their key benefits. 

    What are Balanced Funds?

    A Balanced fund is a category of mutual fund that invests in a mix of equities and debt or fixed instruments such as government securities, corporate bonds, etc. The main objective of this fund is to create a balance between growth and stability. Equity investment comes with volatility; hence, it is not suitable for investors seeking stability in the portfolio. Then SEBI came up with an idea to introduce a fund known as Balanced, in which a fund manager can also take exposure to debt along with equity to provide stability in the portfolio. 

    Key Features of Balanced Fund

    The key features of a balanced fund are as follows:

    • Mix of Equity and Debt: This is one of the key features of a balanced fund that it has an allocation in both equity and debt that provides stability with growth.
    • Professional Management: The portfolio of a balanced fund is managed by a professional fund manager who decides which securities to buy and sell based on market conditions.
    • Moderate Investors: Investors who have a moderate risk profile can consider investing in a balanced advantage fund.
    • Rebalancing: The fund manager regularly rebalances the portfolio between equity and debt depending on the market conditions to generate higher returns.
    • Market Linked Performance: The returns of the portfolio depend on the market performance because a major portion of the portfolio is allocated towards equity.

    Best Balanced Fund

    1. HDFC Balanced Advantage Fund
    2. ICICI Prudential Balanced Advantage Fund
    3. SBI Balanced Advantage Fund
    4. Kotak Balanced Advantage Fund
    5. Edelweiss Balanced Advantage Fund
    FundsNet Assets (Cr)1 Yr Ret (%)3 Yr Ret (%)5 Yr Ret (%)Base Expense Ratio (%)Exit Load (Period)
    HDFC Balanced Advantage Fund – Regular Plan1,07,7663.8413.1314.891.091.00 (365)
    ICICI Prudential Balanced Advantage Fund72,4869.0012.2411.181.141.00 (365)
    SBI Balanced Advantage Fund – Regular Plan41,5135.5710.30—1.281.00 (365)
    Kotak Balanced Advantage Fund – Regular Plan17,4295.159.688.881.431.00 (180)
    Edelweiss Balanced Advantage Fund – Regular Plan13,0317.7010.499.331.461.00 (90)

    Overview of Best Balanced Fund

    The overview of the best balanced fund is as follows:

    1. HDFC Balanced Advantage Fund: This is one of the oldest funds in the balanced advantage category. It was launched by HDFC AMC in 2000. It follows a dynamic asset allocation strategy in which the fund manager changes the equity exposure based on market conditions. This fund is suitable for investors with medium to long duration.
    2. ICICI Prudential Balanced Advantage Fund: This fund was launched in December 2006. The fund dynamically adjusts its allocation in equity and debt based on market valuations. The fund strategy attempts to generate returns in the long run while keeping risk limited.
    3. SBI Balanced Advantage Fund: This is a new fund in this category launched in 2021. The category of the fund gives it the flexibility to take more aggressive bets when the opportunity arises in the market, and the fund manager becomes defensive when the market turns challenging.
    4. Kotak Balanced Advantage Fund: This fund was launched in 2018 and aims to provide investors with a diversified portfolio of equity and debt. This helps an investor make informed decisions, and the fund manager decides when to increase equity exposure and when to become more defensive.
    5. Edelweiss Balanced Advantage Fund: The fund was launched in 2009 by Edelweiss Asset Management Company. One of the key advantages of investing in this fund is to strike a balance between growth and stability in the portfolio by adjusting the asset allocation. It is suitable for long-term investors having a moderate risk profile. 

    Read Also: Mutual Fund Factsheet: Definition And Importance

    How do Balanced Funds Work

    A balanced fund works by investing investors’ money in equity and debt, and the fund manager can change the allocation based on market conditions. The allocation to equity by the fund manager generates capital appreciation in the portfolio, whereas the allocation to debt in the portfolio provides stability. The periodic rebalancing is done by the fund manager, and the NAV of the fund depends on the performance of the fund. 

    Benefits of Investing in Balanced Fund

    The key advantages of investing in a balanced fund are as follows:

    • Long-Term Wealth Creation: Investment in this fund allows an investor to create wealth in the long-run. As balanced funds have equity in their portfolio, therefore it is suitable for long-term investors.
    • Reduce Dependency: Market conditions affect asset classes in a different manner. While equity goes through a tough phase, debt in the portfolio provides stability; therefore, this fund reduces dependency on a single asset class.
    • Convenient: Investment in a balanced fund can be started with a small amount. This makes it accessible for the investor who does not wish to invest a large amount.

    Risk of Investing in a Balanced Fund

    The key risks of investing in a balanced fund are as follows:

    • Market Risk: As the fund manager invests a significant portion of the portfolio in equity, if the market falls, the investment value can also fall.
    • Credit Risk: Balanced funds invest in fixed income securities such as corporate bonds, etc., that are exposed to credit risk such as default or delay in payments by the issuer of the securities.
    • Exit Load: There are various balanced fund that carries exit load; therefore, if the investor withdraws the money before a defined time period, the fund may charge an exit load.

    How to Invest in Mutual Fund

    To invest in mutual funds, one can follow the steps mentioned below:

    1. Open Account: The first step towards investing in a balanced fund is to open an account with Pocketful.
    2. Completing KYC: To open an account, one is required to complete the KYC, which generally takes 5-10 minutes. For this, one is required to have basic documents such as PAN, Aadhaar, etc.
    3. Look For Mutual Fund: After logging in to the mobile application, you need to visit the mutual fund section of the mobile application.
    4. Choose Fund: In the mutual fund section, you can look for the balanced fund of your choice. The fund can be chosen based on the risk profile and fund performance.
    5. Choose Investment Option: Once the fund is chosen, you can select the investment option such as SIP or Lumpsum.
    6. Periodic Review: An investor should periodically review their portfolio to enhance its return by removing underperforming funds from the portfolio.

    Who Can Invest in a Balanced Fund?

    Investment in a balanced fund is suitable for investors who want to have a mix of both growth and stability in their portfolio and do not want to take the risk associated with pure equity funds. Investors having a short-term investment horizon, generally up to 4-5 years, can invest in this fund. This fund allows an investor to have diversification across equity and debt through a single investment. However, choosing a balanced category of mutual fund depends on the investor’s risk profile and goals. 

    Read Also: Dynamic Asset Allocation Funds India

    Conclusion

    On a concluding note, investment in a balanced fund can be a good option for investors seeking stable returns along with moderate growth in the portfolio. Instead of investing in different asset classes such as equity and debt, one can get direct exposure by investing in a single fund. However, these funds are not completely risk-free and carry certain risks such as market risk, credit risk, etc. Therefore, it is advisable to consult your investment advisor before making any investment in a balanced fund.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top 10 Fund Managers in India
    2Best Corporate Bond Funds in India
    3Best Index Funds in India
    4Best Target Maturity Mutual Funds in India to Invest
    5Best Silver Mutual Funds to invest in India
    6Top 10 Mutual Fund Distributors in India
    7Top 10 High-Return Mutual Funds in India
    8Best Money Market Mutual Funds in India
    9Best Thematic Mutual Funds in India
    10Best Gilt Mutual Funds to invest in India

    Frequently Asked Questions (FAQs)

    1. What is a balanced fund?

      The balanced fund meaning refers to a category of mutual fund in which a fund manager primarily invests in equity and debt based on the market conditions.

    2. Among a balanced fund and an equity fund, which is more risky?

      An equity fund carries more risk as a major portion of its portfolio invests in equity. Whereas, on the other side a balanced fund invests a portion in debt that increases stability in the portfolio.

    3. Do balanced funds give guaranteed returns?

      No, a balanced fund does not give guaranteed returns as its portfolio contains a significant portion in equity; therefore, its returns are dependent on market returns.

    4. Can I withdraw money anytime from a balanced fund?

      Yes, you can withdraw money from a balanced fund anytime. However, there are some balanced advantage funds that carry exit load.

    5. Balanced Advantage Funds are suitable for which types of investors?

      Balanced Advantage Funds are suitable for moderate and conservative investors. These investors wish to have stability along with moderate returns in the portfolio.

  • What Is Blue Chip Funds?

    What Is Blue Chip Funds?

    Investing in individual blue-chip stocks requires a large sum of money; alternatively, it carries high risk. Now you can also invest in a basket of blue-chip companies through a single investment, along with professional management, through Blue-chip Funds.

    In today’s blog post, we will give you an overview of blue-chip funds along with the list of best blue-chip funds.

    What are Blue-Chip Funds?

    A blue-chip fund is a category of equity-oriented mutual fund that primarily invests investors’ money in large-cap companies, as measured by market capitalisation. This categorisation of mutual funds is defined by SEBI. These large-cap stocks are the top 100 stocks listed on the stock exchange based on market capitalisation. The large-cap fund invests at least 80% of its fund into large-cap stocks. The stocks in blue-chip funds are from different sectors such as banking, IT, pharma, etc. This fund is suitable for investors who seek long-term growth in the portfolio along with moderate risk.

    Key Features of Blue-Chip Funds

    The key features of blue-chip funds are as follows:

    • Investment in Large Cap Stocks: The blue-chip fund primarily invests your money in the biggest listed companies based on market capitalisation.
    • Diversification: The fund manager diversifies the fund across different large-cap companies. That reduces the portfolio concentration risk, allowing a user to have a diversified portfolio.
    • Professional Fund Management: The amount invested in blue-chip funds is managed by the professional fund manager, who has an expert research team.
    • No Guaranteed Returns: The returns from the investment in blue-chip funds are not guaranteed and are dependent on the market.

    Best Blue-Chip Funds

    1. ICICI Prudential Large Cap Fund
    2. SBI Large Cap Fund
    3. Nippon India Large Cap Fund
    4. HDFC Large Cap Fund
    5. Mirae Asset Large Cap Fund
    FundsNet Assets (Cr)1 Yr Ret (%)3 Yr Ret (%)5 Yr Ret (%)Base Expense Ratio (%)Exit Load (Period)
    ICICI Prudential Large Cap Fund80,9601.1612.6812.661.131.00 (30)
    SBI Large Cap Fund55,4314.4710.5010.561.210.25 (30)
    Nippon India Large Cap Fund54,2252.0112.5014.691.221.00 (7)
    HDFC Large Cap Fund – Regular Plan40,1982.5810.7712.401.291.00 (365)
    Mirae Asset Large Cap Fund – Regular Plan38,7292.959.719.131.301.00 (365)
    (Fig as of 12th Aug 2026)

    Overview of Best Blue-Chip Funds

    The overview of the best blue-chip funds is as follows:

    1. ICICI Prudential Large Cap Fund: It was introduced by ICICI AMC in 2008. This is an open-ended scheme which mainly invests in large-cap stocks. Earlier, it was called ICICI Prudential Bluechip Fund and in the year 2025 it was renamed as ICICI Prudential Large Cap Fund. The fund’s approach is to hold large-cap stocks with a long-term view.
    2. SBI Large Cap Fund: The fund was launched in 2006 by SBI Asset Management Company and is an open-ended fund in which an investor can invest and withdraw anytime. The primary aim of the fund is to generate long-term capital appreciation and primarily invests in large-cap companies. Investment in this fund gives an investor exposure to established companies listed on the stock exchange.
    3. Nippon India Large Cap Fund: This is a fund offered by Nippon AMC which was launched in the year 2007. The investment strategy is diversified and provides exposure to the largest companies. An active fund manager takes active measures to perform best relative to the benchmark. This fund is for an investor with a long term investment period.
    4. HDFC Large Cap Fund: This is one of the oldest funds in the blue-chip category. The fund was launched in 1996, and since its launch, the fund has gone through various market cycles. It has consistently posted market-beating returns. The fund aims to participate in the long-term growth of large-cap companies.
    5. Mirae Asset Large Cap Fund: It is an open-ended scheme which was launched in 2008 and invests in the large cap segment of the stock market. The fund manager’s emphasis is on finding opportunities within existing large cap stocks. The fund was earlier named Mirae Asset India Equity Fund and it was renamed to Mirae Asset Large Cap Fund in 2019.

    Read Also: Top 10 Blue Chip Stocks in India

    Benefits of Investing in Blue-Chip Funds

    The key benefits of investing in blue-chip funds are as follows:

    • Lower Volatility: Investment in blue-chip funds comes with lower volatility than mid and small cap funds. Because it invests in established companies.
      Different Sectors: The portfolio of blue-chip funds contains stocks from different sectors such as banking, IT, pharma, etc.
    • Liquidity: Blue-chip funds come with higher liquidity as large-cap stocks are actively traded by traders. Therefore, this fund provides better liquidity than small-cap funds.
    • Long-Term Wealth Creation: The key objective of the blue-chip fund is to create wealth in the long-run. This fund is opted by investors having an investor horizon of more than 5 years.

    Risk of Investing in Blue-Chip Funds

    The key risk of investing in blue-chip funds is as follows:

    • Market Risk: This is the key risk that comes while investing in blue-chip funds. When the overall market falls, the NAV of this fund also declines.
    • Sector Risk: As the fund carries stocks belonging to different sectors. Any significant downfall in any particular sector can impact the performance of blue-chip funds.
    • Performance Risk: The returns of this fund are dependent on the performance of the fund manager. If the fund manager fails to select the stocks that can perform better, the overall performance of the fund may fall.
    • Exit Load: Certain funds come with an exit load, which means if an investor withdraws money before a stipulated time period, the fund may charge an exit load on it.

    Who Should Invest in Blue-Chip Funds?

    These funds are best for investors who wish to invest in the long-term growth of well-established companies with a solid financial background. Investors who have a long-term investment horizon with a moderate risk profile can opt for investing in blue-chip funds. Investors, however, should not invest in these funds if they are looking for a fund that provides stable returns. as blue-chip funds can be volatile during market downturns.

    How to Invest in Blue-Chip Funds?

    To invest in blue-chip funds, one can follow the steps mentioned below:

    1. Visit Pocketful Website: The first step towards investment in a blue-chip fund is to visit the website of Pocketful. After which you are required to open a demat account by completing your KYC. The process will only take 5 min.
    2. Look for the Mutual Fund Section: After login into your mobile application, there is a section known as invest in Mutual Fund. You can explore the blue-chip funds there.
    3. Fund Selection: There will be a list of blue-chip funds in which you can invest. However, scheme selection should be based on various parameters such as its performance, etc.
    4. Choose Investing Mode: Once you identify the fund in which you want to invest, the next step will be choosing the mode of investment. As there are two modes of investment, SIP and lump sum, you can identify one based on your need.
    5. Monitor: Regular and periodic monitoring of the portfolio is necessary so that the underperforming funds can be removed from the portfolio.

    Conclusion

    On a concluding note, blue-chip funds are a suitable option for investors who want to invest in the top 100 companies of India. Investing in these stocks individually requires a large sum of money. Then come the blue-chip funds offered by various asset management companies, in which the fund manager identifies the stocks from the top 100 companies of India. However, investment in these stocks does not mean that you get guaranteed returns. However, before making any investment in blue-chip company, it is advisable to consult your investment advisor and evaluate your risk profile. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Best Long-Term Mutual Funds to Invest in India
    210+ Best Investment Plan for Monthly Income in India
    3Best Gilt Mutual Funds in India
    4Best Precious Metal Mutual Funds to Invest in India
    5Best SWP for Monthly Income in India

    Frequently Asked Questions (FAQs)

    1. What are Blue-chip fund?

      It is a category of mutual fund that primarily invests 80% of its capital in shares of large-cap companies. These are the top 100 companies listed on the Indian stock exchange based on market capitalisation.

    2. What is the ideal investment duration for a blue-chip fund?

      These funds are generally suitable for investors with a longer investment horizon of more than 5 years.

    3. Do we need a demat and trading account to invest in blue-chip funds?

      No, it is not essential to have a demat and trading account to invest in blue-chip funds. One can opt for investing in blue-chip funds in SOA form.

    4. How do blue-chip funds and blue-chip stocks differ from each other?

      Blue-chip stocks are the individual stocks of a company commonly known as large-cap. On the other hand, blue-chip funds are a pool of large-cap shares.

    5. What affects the performance of a blue-chip fund?

      The key factors that affect the performance of a blue-chip fund are market movement, earnings of companies, economic conditions, etc.

  • What is STP in Mutual Funds?

    What is STP in Mutual Funds?

    Timing the market is every investor’s dream, but predicting where it will go next is nearly impossible. This is where a Systematic Transfer Plan becomes useful, offering a disciplined way to invest your money step by step. In this article, we will explain the full form of STP in mutual fund investing, how it works, and key details you should know in simple terms.

    STP Full Form? 

    STP stands for Systematic Transfer Plan. It is a mutual fund facility wherein your money is automatically transferred from one scheme to another at fixed intervals (such as monthly or weekly). Typically, this facility is available between different schemes offered by the same AMC.

    What is STP in Mutual Funds?

    An STP in mutual fund investing is a facility that lets you move a lump sum of money from one scheme to another over time. For example, many people first park their funds in a liquid scheme and then shift a fixed amount into an equity fund every month. This strategy helps reduce the risk of putting all your money into the market at once.

    Example: Suppose you have ₹3 lakh to invest. Instead of putting the whole amount into an equity fund right away, you first invest it in a liquid fund. Then, using an STP, you transfer ₹25,000 each month into an equity fund under the same AMC. Your full investment gets deployed gradually over 12 months, saving you from exposing the entire sum to market volatility on day one. 

    How Does a Systematic Transfer Plan Work? 

    Once you set up an STP, your money is automatically transferred from one mutual fund scheme to another at scheduled intervals.

    Step 1: Invest a lump sum amount

    First, invest your lump sum amount in a Liquid Fund or Debt Fund. This serves as your ‘Source Fund’ from which money will be transferred subsequently.

    Step 2: Select a Target Fund

    Next, choose the mutual fund scheme from the same Asset Management Company (AMC) into which you wish to invest gradually. Many investors opt for Equity Funds for long-term investment.

    Step 3: Determine the amount and frequency

    Decide the transfer amount and the frequency of the transfers. You can choose from weekly, monthly, or quarterly options based on your requirements.

    Step 4: Start the STP

    Once the STP begins, the specified amount is automatically moved from the Source Fund to the Target Fund on the scheduled dates. There is no need to make separate investments each time.

    Step 5: The process continues until the investment is complete

    The process continues until the designated total amount is transferred or the chosen tenure concludes. You can also modify or stop the STP midway if the need arises.

    Types of Systematic Transfer Plan 

    Not all STPs are the same. You can choose the right option based on your investment style and goals.

    1. Fixed STP

    In a Fixed STP, a predetermined amount is transferred each time. The transfer amount remains unchanged regardless of whether the market rises or falls. This is why most investors prefer this option.

    Example: If you have invested ₹1,20,000 and opted to transfer ₹10,000 monthly, that same amount will be moved to the target fund every month.

    2. Flexi STP

    In a Flexi STP, the transfer amount is not fixed in advance. It can increase or decrease based on market conditions or rules set by the AMC. This option is suitable for investors who actively monitor the market.

    Example: Suppose ₹10,000 is being transferred under normal circumstances. If there is a significant market dip, the transfer amount could increase to ₹20,000, in accordance with the scheme’s rules.

    3. Capital Appreciation STP

    With this option, your original investment amount remains intact, and only the profit earned on it is transferred to another fund. This ensures the principal investment stays in the source fund.

    Example: You invested ₹3 lakh, and after some time, it generated a profit of ₹8,000. In this case, only the ₹8,000 profit would be transferred to the other fund, while the ₹3 lakh principal would remain in the source fund.

    Read Also: Mutual Fund Riskometer: Meaning, Risk Levels & Guide

    Why Investors Prefer STP in Mutual Fund 

    If you have a lump sum amount, an STP offers an easy way to invest it gradually. This is why many investors incorporate it into their investment strategy.

    • Helps mitigate market timing risk: Investing the entire amount on a single day can expose you to a significant impact if the market falls. With a Systematic Transfer Plan, money is invested at different times, which helps reduce the risk associated with investing at a single price point.
    • Offers the benefit of Rupee Cost Averaging: Each transfer takes place at a different Net Asset Value (NAV). This results in investments being made at varying prices, helping to balance out the average purchase cost.
    • Utilizes idle money effectively: Until the entire amount is transferred to the equity fund, it remains invested in the source fund. This ensures your money does not simply sit idle in a bank account.
    • Maintains investment discipline: Transfers under an STP happen automatically. This reduces the need to constantly monitor the market to make investment decisions, ensuring that investing continues according to the plan.
    • Simplifies long-term investing: If your goal is long-term investment, an STP provides an opportunity to invest in equities gradually. This minimizes the likelihood of making hasty decisions.

    STP vs mutual vs SWP – Understand the Difference 

    STP, SIP, and SWP are all mutual fund facilities, but they serve different purposes.

    ParameterSTP (Systematic Transfer Plan)SIP (Systematic Investment Plan)SWP (Systematic Withdrawal Plan)
    Source of MoneyExisting Mutual Fund SchemeBank AccountExisting Mutual Fund Investment
    Primary PurposeTransfer money from one mutual fund scheme to anotherInvest a fixed amount regularlyWithdraw a fixed amount at regular intervals
    Best ForInvestors with a lump sum amountRegular monthly investorsInvestors seeking regular income
    ProcessAutomatic transfer between mutual fund schemesAutomatic investment from bank accountAutomatic withdrawal to bank account
    Common Use CaseGradually moving lump sum into equity fundsBuilding wealth through regular investingCreating a steady cash flow after investment
    Money FlowMutual Fund – Mutual FundBank Account – Mutual FundMutual Fund – Bank Account
    Market Timing RiskHelps reduce lump sum timing riskHelps through rupee cost averagingNot applicable, as it is used for withdrawals

    When Should You Use a Systematic Transfer Plan? 

    An STP is not essential for every investor. It is particularly useful when you have a large lump sum and wish to invest it gradually.

    • Upon receiving a bonus: If you have received a bonus from your company, investing the entire amount into an equity fund at once might not be ideal; instead, investing it in a phased manner via an STP could be a better option.
    • After selling a property: Instead of immediately investing the large sum received from a property sale, you can use an STP to gradually transfer the funds into equity mutual funds.
    • After Fixed Deposit (FD) maturity: If you wish to invest in mutual funds after your FD matures, an STP allows you to enter the market gradually, thereby avoiding the risks associated with a lump-sum investment.
    • When investing your retirement corpus: Rather than investing the substantial amount received upon retirement into equities all at once, a phased investment approach via an STP can offer a more balanced strategy.
    • Upon receiving a large inheritance or gift: If you have received a significant sum as an inheritance or gift, you can invest it gradually in alignment with your investment plan using an STP.
    • During market volatility: If the market is highly volatile and you are uncertain about the right time to invest, a Systematic Transfer Plan can be a practical option for investing gradually.

    Key Benefits of STP Mutual Fund 

    If you have a lump sum amount, an STP offers an easy way to invest it without rushing.

    • Automated investing: Once the STP is set up, every transfer occurs automatically on the scheduled date. This eliminates the need to make separate investments every month.
    • Customizable plans: You can determine the transfer amount, timing, and duration based on your needs. This makes it easier to manage your investments in alignment with your financial goals.
    • Easy portfolio adjustments: If you wish to change your investment strategy over time, an STP allows you to gradually transfer funds from one scheme to another.
    • No pressure to make a one-time decision: Since you do not have to invest the entire amount at once, making investment decisions becomes easier. It also reduces the likelihood of making hasty choices.Useful for long-term planning: If you have a long-term goal, an STP helps you proceed with your investments in a systematic manner, allowing the entire process to run smoothly with minimal effort.

    Risks and Limitations of STP 

    An STP can simplify investing, but it is incorrect to view it as entirely risk-free. Before starting, it is important to be aware of certain limitations.

    • No guarantee of better returns: While a Systematic Transfer Plan (STP) can help mitigate the risk associated with market timing, there is no guarantee of higher returns. Returns are always dependent on market performance.
    • Tax may apply to each transfer: In an STP, funds are withdrawn from the source fund each time; consequently, every transfer is treated as a redemption. As a result, capital gains tax may be applicable in accordance with prevailing rules.
    • Exit load may be applicable: If the source fund scheme carries an exit load and you transfer funds before the stipulated period, you may be required to pay an exit load in certain cases. Therefore, it is essential to review the scheme’s terms and conditions before initiating an STP.
    • Market risk is not entirely eliminated: An STP merely helps reduce the risk associated with investing a lump sum. If the market remains weak for an extended period, your investment could still be impacted.

    Taxation Rules for STP in Mutual Funds 

    It is important to understand the tax rules before starting an STP, as every transfer is considered a separate transaction from a tax perspective.

    Tax AspectTax Rules (Latest)
    Capital Gains TaxIn an STP, every transfer from the source fund is treated as a redemption. If a profit is made, applicable capital gains tax may have to be paid.
    Equity Mutual Fund TaxIf the source fund is an equity mutual fund, STCG (20%) applies to gains if held for up to 12 months, while LTCG at 12.5% ​​applies to gains exceeding ₹1.25 lakh if ​​held for more than 12 months.
    Debt Mutual Fund TaxGains on most debt mutual funds purchased on or after April 1, 2023, are taxable according to the investor’s income tax slab rate.
    Exit LoadIf an exit load applies to the source fund, an exit load may also be levied on the amount transferred during an STP. This depends on the rules of the specific scheme.
    Holding PeriodWith every transfer, a new purchase date is assigned to the units of the Target Fund purchased; consequently, the calculation of their holding period also begins from that date.

    Read Also: SIP Installment Failed? Reasons, Bank Charges & Solutions

    Conclusion

    If you have a lump sum amount to invest, a Systematic Transfer Plan (STP) can be a useful option. It facilitates phased investment; however, it is equally important to understand your goals, risk appetite, and tax implications before making a decision.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1SIP vs Recurring Deposit (RD): Which Is Better
    2Mutual Fund Portfolio Tracking: A Complete Guide
    3How to Increase SIP Amount: Smart Strategies
    4Micro SIP in Mutual Funds
    5Bond ETFs vs Bond Mutual Funds: Which Is Better?
    6What is Top-up SIP?

    Frequently Asked Questions (FAQs)

    1. What is STP in Mutual Funds?

      It is a facility to transfer a regular amount from one scheme to another.

    2. What is the full form of STP?

      The full form of STP is Systematic Transfer Plan.

    3. Who can use STP?

      Those who have a lump sum amount to invest.

    4. Is STP better than SIP?

      It depends on your investment needs.

    5. Is STP taxable?

      Yes, tax rules may apply to each transfer.

  • Mutual Fund Riskometer: Meaning, Risk Levels & Guide

    Mutual Fund Riskometer: Meaning, Risk Levels & Guide

    Let us talk about growing your wealth safely in the financial markets. Every step you take toward investing brings a mix of exciting opportunities and unpredictable changes. We all want our hard earned money to grow steadily without losing sleep over market crashes.

    Having a clear and visual safety gauge helps us navigate this financial journey with confidence. It acts like a guiding light for everyday investors entering the complex world of finance.

    This ensures that every investment decision aligns perfectly with your personal comfort level. We will explore how to read and use this important tool to make smarter choices.

    What is Riskometer?

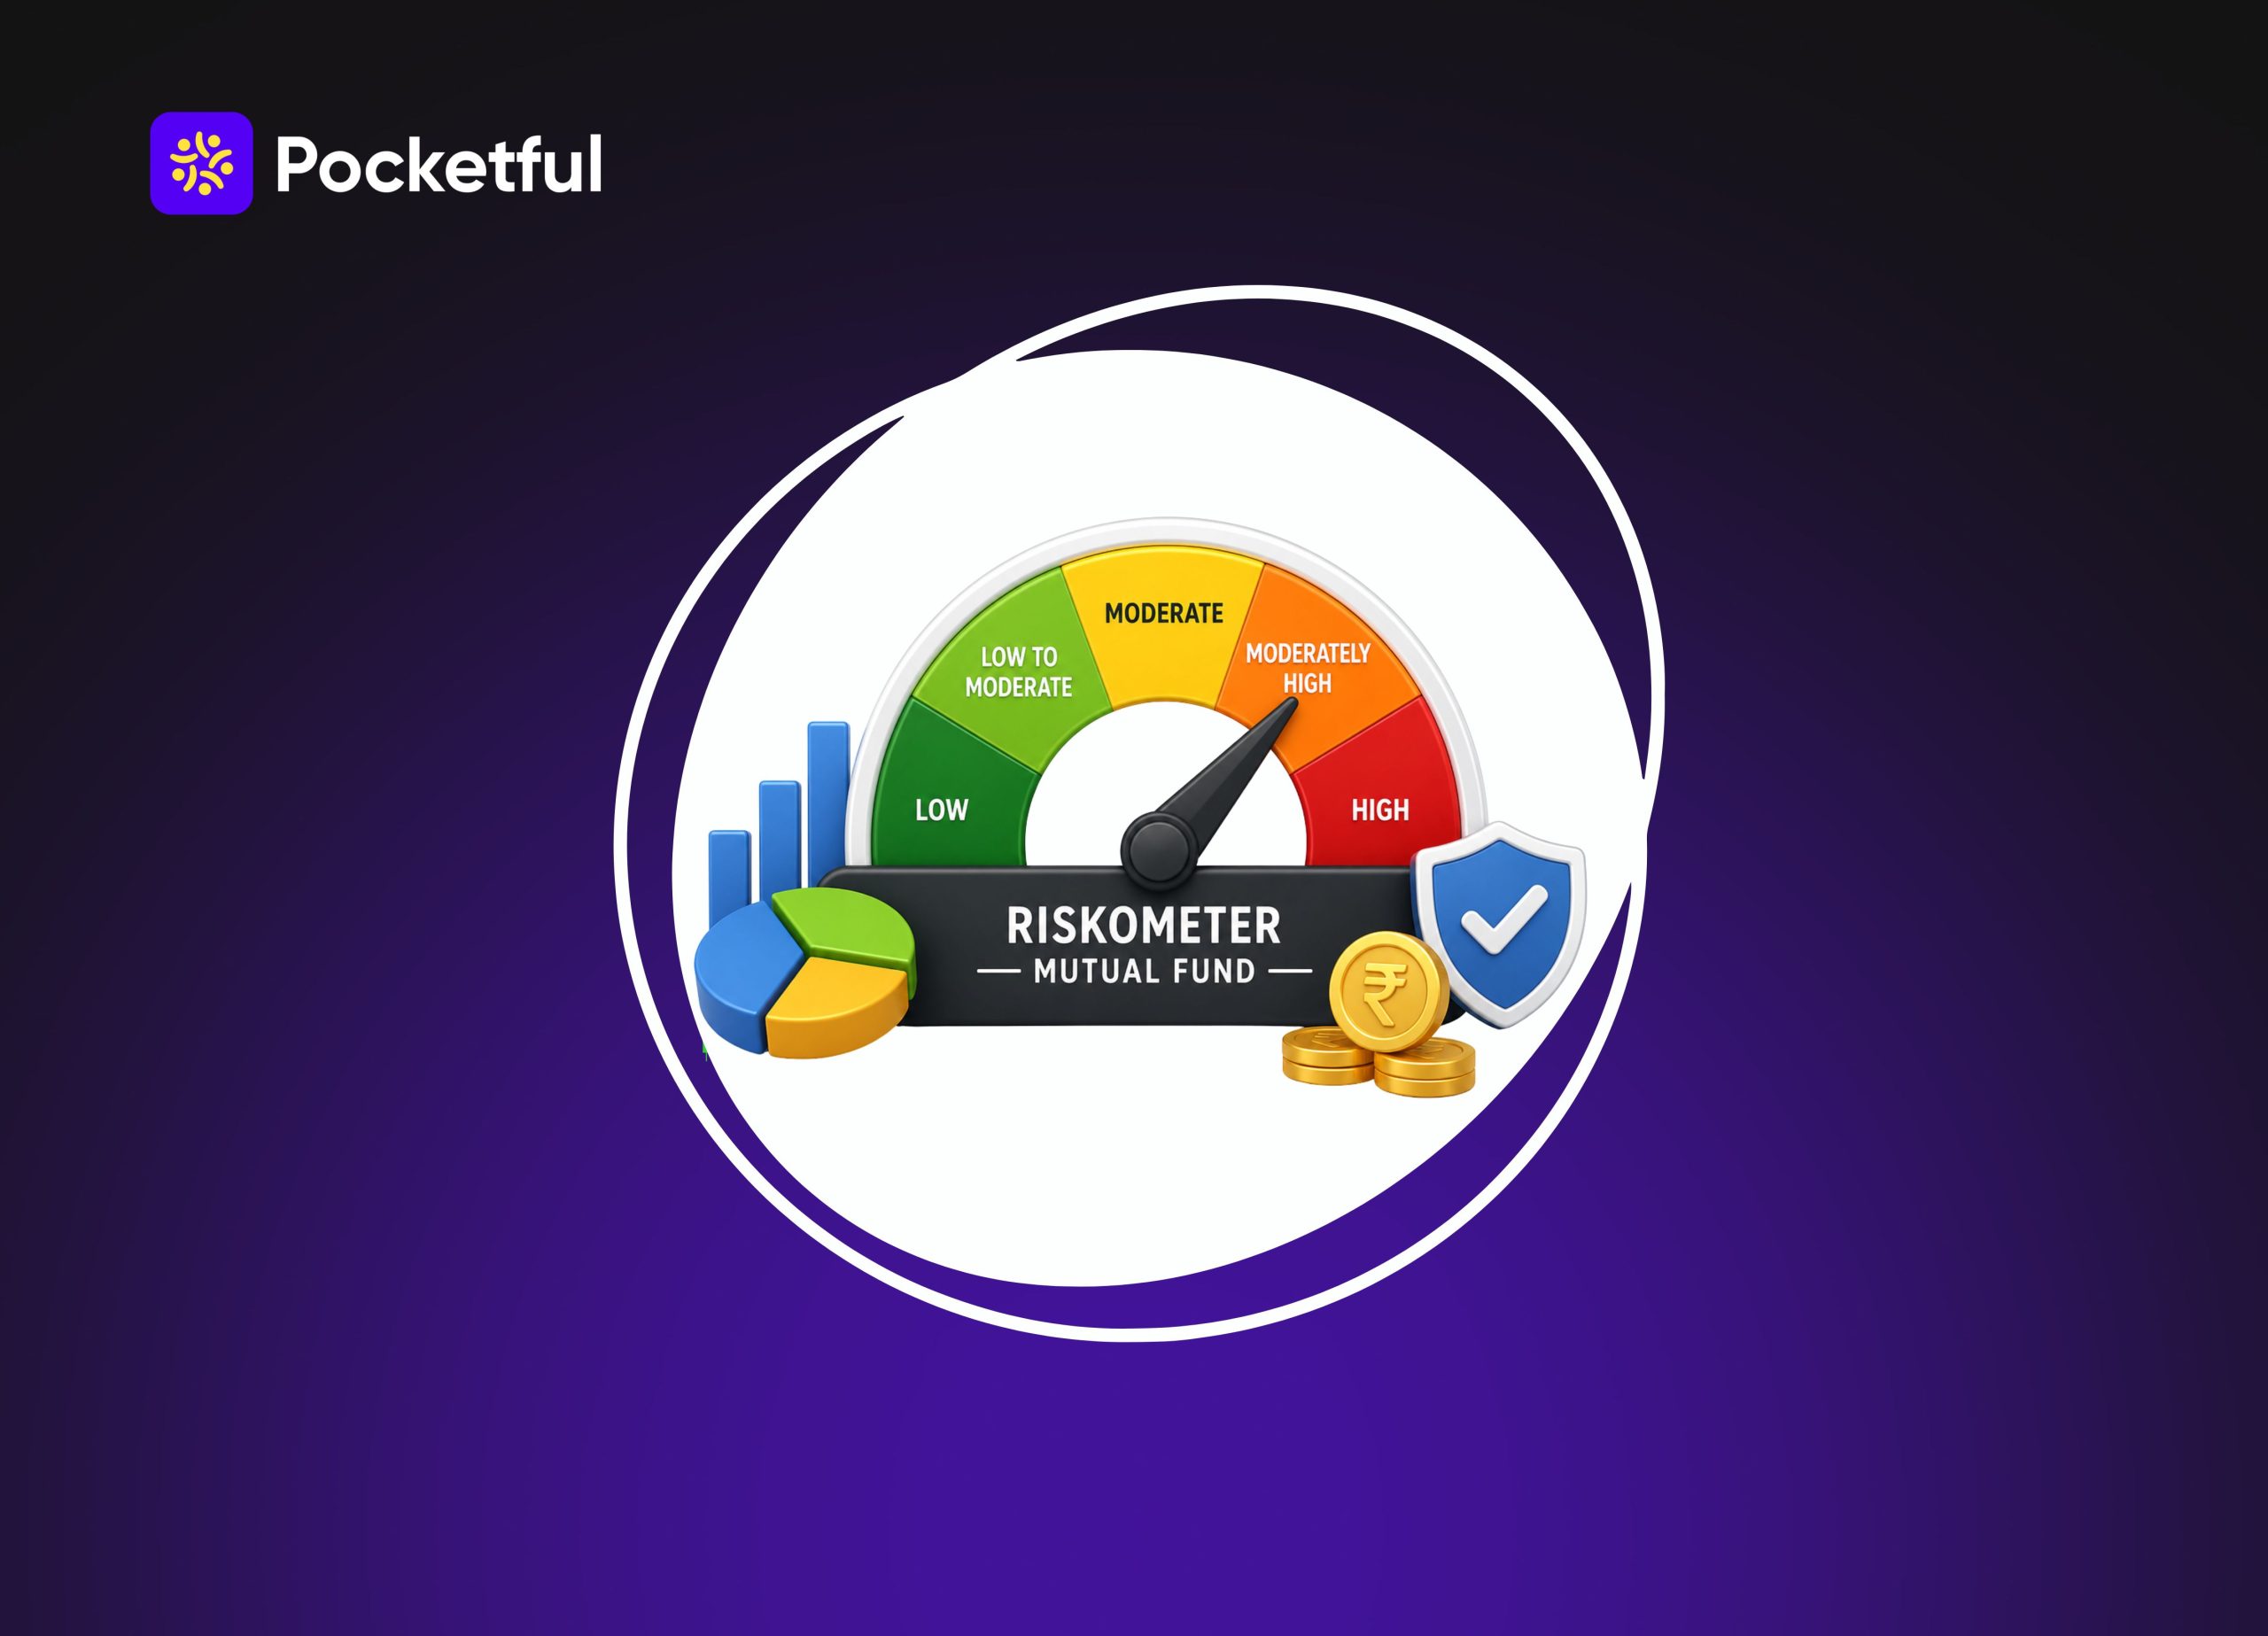
    A Mutual Fund Riskometer is a standardized visual indicator mandated by the Securities and Exchange Board of India (SEBI). It is basically a graphic tool that shows the exact level of risk a specific investment scheme carries. You can think of it just like the speedometer on your car dashboard, this financial dial tells you how much risk your money is taking. 

    For example, let us say you want to invest your savings in a very safe debt scheme. In this case, the needle on the dial will point directly to the green zone.

    On the other hand, if you choose a highly aggressive equity scheme, the needle will instantly point to the red zone. This makes it incredibly easy for regular investors to understand complex risk factors at a single glance.

    History of Riskometer

    The journey of this visual safety indicator shows a continuous effort by SEBI to simplify investing for everyone. The regulator constantly upgrades its rules to protect regular investors like us. The first version of this tool was introduced to the public back in March 2013.

    However, this broad classification confused many people because very different schemes were grouped together.

    To fix this issue, a major upgrade happened in July 2015. Then dial included low, moderately low, moderate, moderately high, and high risk categories.

    Later, in October 2020, another significant revision was announced. A sixth category called very high risk was added to capture extreme market movements. Most recently in late 2024, official color codes were assigned to all six levels. The regulator also made it mandatory to display the scheme dial right next to its benchmark index dial. This allows you to easily compare your fund with the broader market.

    Riskometer Risk Level

    The current framework of mutual fund riskometer classifies investment schemes into six distinct categories. Each level represents a different degree of potential volatility and comes with a specific color code. We have outlined these details below to help you easily understand what each level means.

    Risk LevelColourProducts under the categorySuitable for
    LowGreenIncome funds, gilt funds, and fixed maturity plans with a maturity of less than 90 days come under this category as these carry the lowest risk.Those who are risk averse and give priority to their investment safety.
    Moderately lowLight greenShort and medium term bonds with a maturity period of 91 days to 3 years come under this category. These also bear minimal risk.Those who prefer to take nominal risks but also prioritise the safety of their investment.
    ModerateYellowHybrid debt oriented funds, monthly investment plans, and arbitrage funds come under this category as these are somewhat risky. These are ideal for medium to long term investing.Those who prefer to invest longer than short term and would be ready to undertake a certain degree of risk for slightly lucrative returns.
    Moderately highOrangeGold ETFs, index funds, diversified equity funds, and balanced equity oriented funds with an equity exposure of upto 20 percent of the portfolio come under this category.Those who opt for long term investment and are ready to be exposed to some degree of risk.
    HighRedMicro cap funds, international funds, thematic funds, and sectoral funds are classified under this category.These are ideal for high net worth individuals or aggressive investors who want to invest for long term and can handle losses.
    Very HighDark RedSmall cap funds, mid cap funds, and dynamic asset allocation schemes fall under this category.Investors with a very high risk appetite and a highly extended investment horizon.

    Why SEBI Introduced Riskometer

    The Securities and Exchange Board of India introduced this tool to bring complete transparency to the financial markets. Before this visual dial existed, investors often chose schemes based purely on past returns. They completely ignored the hidden dangers involved in those investments.

    SEBI wanted to create a standardized language for risk that anyone could understand easily. This visual dial successfully prevents the mis selling of financial products by distributors.

    An aggressive scheme can no longer be sold as a safe option because the dial will immediately expose the truth. It simply empowers ordinary people to make informed decisions without needing a finance degree.

    Read Also: Mutual Fund Factsheet: Definition And Importance

    Types of Risks in Mutual Fund Measured by Riskometer

    The visual dial does not just guess the risk level randomly. It calculates a numerical score based on several underlying risk factors present in the portfolio. Here are the primary risks measured by this tool:

    • Market Risk: This refers to the general ups and downs of the stock market. Economic changes can cause the value of equity investments to drop suddenly. The dial captures this volatility to warn you in advance.
    • Liquidity Risk: This measures how quickly an investment can be sold in the market without facing a heavy loss. Some underlying securities are hard to sell during a sudden financial emergency. The tool accounts for this difficulty.
    • Credit Risk: This applies mostly to debt schemes and fixed income assets. It indicates the chance that a bond issuer might fail to pay back the interest or the principal amount. A higher chance of default increases the risk score.
    • Interest Rate Risk: Bond prices usually fall when overall interest rates in the economy rise. Schemes with long term bonds carry a much higher interest rate risk. The dial reflects this sensitivity to rate changes.
    • Concentration Risk: This happens when a scheme invests too heavily in one single sector or a few specific companies. If that particular sector performs poorly, your entire investment suffers significantly. The risk score rises when investments are not properly diversified.

    Use of Riskometer in Mutual Fund Investment

    You can actively use this tool to build a healthier and more balanced financial portfolio. Here are the best ways to utilize it:

    • Matching Personal Comfort: The dial helps you pick schemes that perfectly match your emotional ability to handle losses. A conservative investor can easily filter out high risk equity schemes right from the start. This prevents panic selling during market dips.
    • Reviewing Portfolio Changes: Asset management companies are required to update the risk dial every single month. You can check these updates to ensure your chosen scheme has not quietly become riskier over time. It acts as a continuous health check for your money.
    • Benchmarking Performance: The latest rules require schemes to display their risk dial alongside the market benchmark dial. This helps you see if a scheme manager is taking unnecessary risks compared to the general market. It makes performance comparison much more transparent.
    • Goal Planning: Short term financial goals require strict stability, so you can choose schemes in the green zones. Long term goals can tolerate the red zones for better potential growth. Aligning your goals with the right color code simplifies planning.

    Limitation of Riskometer

    While the dial is a fantastic guide, it does have certain boundaries. You must keep these limitations in mind before making financial decisions.

    • No Return Guarantees: A low risk label does not mean the investment is completely foolproof or guaranteed to give positive returns. It simply means the value will fluctuate less than an aggressive fund. You should never confuse low risk with guaranteed profits.
    • Backward Looking Data: The monthly risk score is calculated based on the portfolio holdings of the previous month. It cannot predict future market crashes or sudden economic crises. Therefore, it is a reflection of recent history rather than a future prediction.
    • Does Not Show Cost: The dial completely ignores the expenses and exit loads associated with a scheme. You must check these fee details separately before investing your money. High costs can eat into your returns regardless of the risk level.
    • Frequent Changes: Since the dial is updated monthly, a scheme can shift from a moderate category to a high category very quickly. This requires you to monitor your investments regularly rather than forgetting about them. Passive tracking might lead to unwanted surprises.

    Read Also: Mutual Fund Portfolio Tracking: A Complete Guide

    Conclusion

    Investing successfully is all about finding the right balance between long term growth and capital stability. The visual risk dial serves as a brilliant companion on your financial journey. It translates complicated market data into simple signals that anyone can easily interpret.

    By checking this tool regularly on platforms like Pocketful, you can stay fully aware of where your money is going. An informed investor is always a confident investor. Taking a quick look at this safety gauge ensures a well planned path toward achieving your long term financial dreams.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What Is An IPO Mutual Fund? Should You Invest?
    2Mutual Fund Taxation – How Mutual Funds Are Taxed?
    3Is Your Mutual Fund Investment Safe?
    4What is an Open-Ended Mutual Fund & How to Invest in it?
    5What is Annualised Returns in Mutual Funds?

    Frequently Asked Questions (FAQs)

    1. What is the meaning of a mutual fund riskometer? 

      It is a visual tool created by SEBI showing the level of market risk involved in a specific scheme.

    2. What are the benefits of using this tool?

      It helps you choose schemes matching your risk tolerance and prevents mis selling. It also offers complete transparency by displaying current portfolio risks.

    3. How will you use a riskometer for investing? 

      Simply look at the dial before investing your money. Select green zones for short term safety and orange or red zones for long term growth goals.

    4. Does the risk level change over time? 

      Yes, the risk level can change. Asset management companies update the score every single month based on the latest portfolio holdings.

    5. Are low risk schemes completely safe from losses? 

      No investment is entirely risk free. A low risk label merely indicates minimal price fluctuations, not a zero loss guarantee.

  • SIP Installment Failed? Reasons, Bank Charges & Solutions

    SIP Installment Failed? Reasons, Bank Charges & Solutions

    Investing a small portion of income every month helps create lasting wealth. Many individuals set up automatic payments to build their financial future without daily stress. A systematic approach brings discipline and reduces market timing risks. Sometimes, these automated transfers encounter roadblocks. A missed monthly deduction often causes unnecessary worry for beginners. People naturally panic about losing their money or facing harsh financial penalties. A single missed payment is a minor operational hiccup. It does not destroy the entire investment journey. 

    Understanding the underlying causes helps investors resolve the issue quickly and peacefully. By taking a few simple steps, individuals can put their wealth creation plan back on the right track and continue growing their money steadily.

    What Does SIP Installment Failed Mean?

    A failed payment means the mutual fund company could not take the expected investment amount from the connected bank account on the chosen date. The automated system tries to collect the funds electronically. The bank rejects this digital request due to operational issues.

    Before looking at the common SIP installment reasons, investors must first understand the basic auto-debit process. Every month, a digital mandate allows the bank to send money to the mutual fund company. If this electronic transfer stops, the installment fails. This failure does not mean the previous investments are lost. But banks may charge a penalty for insufficient balance when the SIP auto-debit fails.  The old money remains completely secure.

    Example 

    where an investor named Amit has a monthly mutual fund payment of Rs 5,000 scheduled for the 5th of every month. On April 5th, his bank account only has Rs 3,000. The bank receives the automatic request for Rs 5,000 but rejects it due to low funds. Amit receives a message saying his payment failed. His existing money in the mutual fund remains completely safe. The mutual fund company just skips that specific month. The entire process resumes automatically the next month if funds become available.

    Main Reasons Why Your SIP Installment Failed

    There are several common reasons why automatic deductions get rejected. Knowing these SIP installment reasons helps in preventing future problems.

    • Insufficient Bank Balance This is the most common reason for a failed transaction. The bank account must have enough money on the exact date of the deduction. If the balance is low, the bank automatically rejects the request
    • Expired or Rejected Bank Mandate A mandate is a digital permission given to the bank for automatic deductions. If the mandate expires, gets rejected, or contains incorrect bank details, the payment will not process. Signature mismatches also cause mandate rejections
    • KYC and Detail Mismatch Investors must complete their Know Your Customer requirements. If the PAN card is not linked to the Aadhaar card, financial transactions can stop immediately. Small spelling mistakes in personal details or bank records also cause payment failures.
    • Bank Technical Errors Sometimes the account has enough balance and correct details, but server issues or technical glitches at the bank stop the transaction. These technical glitches are temporary but lead to a missed month
    • Scheme Specific Restrictions In rare cases, the mutual fund company stops taking new money for a specific fund. If a mutual fund scheme is closed for new investments, the automatic payment will naturally fail.

    Read Also: Top SIP Investment Mistakes You Must Avoid

    SIP Installment Failed vs SIP Paused vs SIP Cancelled

    Many beginners get confused between a failed payment, a paused payment, and a cancelled payment. It is important to know the exact difference between these three terms to take the correct action.

    FeatureSIP Installment FailedSIP PausedSIP Cancelled
    MeaningThe payment did not go through due to an error or low balance.The investor voluntarily stops payments for a temporary period.The investor permanently stops future payments to the fund.
    Action RequiredThe bank balance or mandate details need to be checked and fixed.No action is needed. Payments resume automatically after the pause period.A fresh mandate must be registered to start investing again.
    Penalties or Bank ChargesBanks may charge a bounce fee for the failed transaction.There are no penalties or bank charges for pausing an investment.There are no penalties or bank charges for cancelling an investment.
    Impact on Old UnitsExisting units remain safe and continue to grow.Existing units remain safe and continue to grow.Existing units remain safe and continue to grow.

    Is There Any Penalty for Missing a SIP?

    Individuals often worry about harsh penalties when a payment is missed. The reality is much simpler, but there are some financial impacts to keep in mind based on current banking rules.

    • No Penalty from Mutual Fund Companies: Mutual fund houses do not charge any fine or penalty for a missed installment. There are no late fees levied by the asset management company. They simply do not allocate any new units for that specific month. The investment account remains active and healthy.
    • Possible Bank Charges: While the mutual fund company is forgiving, the bank usually is not. sip installment bank charges are a penalty fee for a failed auto-debit transaction. This is known as an ECS or NACH bounce charge. A penalty happens because the bank account did not have sufficient funds to honor the electronic request.
    • Varying Bank Fees : These bounce charges change depending on specific bank policies. Some banks charge around Rs 250 for a failed transaction, while others might charge up to Rs 500 or more for repeated bounce failures. 

    What Happens to Your Investment if a SIP Installment Fails?

    Missing a single month does not mean the end of the wealth creation journey. The financial system handles failed installments in a very specific way.

    • Existing Money Remains Safe: The money already invested is completely untouched. It continues to stay in the stock market and earns returns based on overall market performance. The mutual fund company never sells old units to cover a missed payment.
    • Automatic Continuation Next Month: The mutual fund company does not cancel the entire investment plan after just one missed payment. The automated system tries to deduct the money again the following month. Investors just need to ensure the balance is ready for the next cycle.
    • Loss of Compounding and Averaging Benefits: Regular investing relies heavily on the power of compounding. Missing payments reduces the final wealth accumulated over long periods. It also disrupts rupee-cost averaging. Missing an installment during a market dip means losing a chance to accumulate cheaper units, which can lower long-term profits.
    • Risk of Auto-Cancellation: Mutual funds cancel the entire plan only after multiple consecutive failures. According to the latest guidelines, if an account misses three consecutive installments, the asset management company automatically cancels the plan.

    What to Do If Your SIP Installment Has Failed?

    Taking immediate action prevents further bank charges and keeps financial goals on track. Here is a simple step-by-step guide to quickly fix the issue.

    • Step 1: Check the Bank Account Balance: Look at the detailed bank statement for the exact sip installment bank charges and date of the failed payment. Verify if the account had enough money to cover the full deduction. It is wise to maintain a small buffer amount in the account a few days before the scheduled date.
    • Step 2: Verify the Mandate Status: Log into the mutual fund platform and check the active auto-debit mandate. Ensure that the digital mandate is still active and has not expired. If it shows an error or rejection, a new mandate must be set up immediately.
    • Step 3: Update KYC and Personal Details: Check if the PAN card is properly linked to the Aadhaar card. Ensure there are no pending KYC verification requests. Correct any mismatched personal details with the mutual fund company or the banking partner.
    • Step 4: Make a Manual Lumpsum Payment: To maintain strict investment discipline, individuals can make a manual one-time payment. Most platforms allow users to invest a lumpsum amount equal to the missed monthly installment.
    • Step 5: Contact Support if Needed: If the account balance was sufficient and all details were correct, the failure might be a technical glitch. Reach out to the bank branch or the customer support of the investment platform for immediate guidance.

    Read Also: How to Cancel Mutual Fund SIP?

    Conclusion

    A long marathon is run when wealth is builded. Patience and consistency is required by it. A small hurdle is just faced when a monthly payment is failed. Worry is not needed to be felt. Discouragement should not be felt when a transaction is not gone through. The common causes can be understood. Quick corrective steps can be taken. The issue can be easily resolved by anyone.

    Discipline is stayed with monthly investments. The true key to big financial goals being achieved is holded by this. Consistent efforts must be made. Regular monitoring must be done. Timely actions should be taken. Long-term financial success will ultimately be led to by this. Steady investments should be kept made. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Trail Commission in Mutual Funds?
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. What is the meaning of a failed payment? 

      It means the mutual fund company could not deduct the investment amount from the bank account due to issues like low balance or mandate expiration.

    2. What are the benefits of continuing investments after a failure? 

      Continuing ensures long-term wealth creation. It helps investors benefit from compounding and cost averaging without disrupting their overall financial goals.

    3. How to use a lumpsum payment for a missed month? 

      Investors can manually buy mutual fund units equal to the missed amount through their investment platform, keeping the financial target on track.

    4. Are there any bank charges for missed payments? 

      Yes, banks usually charge a bounce penalty fee along with an 18 percent GST when an auto-debit fails due to insufficient funds.

    5. Does a missed payment cancel the entire plan? 

      No, a single missed payment does not cancel the plan. The system automatically cancels it only after three consecutive missed payments

  • SIP vs Recurring Deposit (RD): Which Is Better in 2026

    SIP vs Recurring Deposit (RD): Which Is Better in 2026

    Every month, millions of Indians face the same question, where do I put this ₹5,000 that I’ve managed to save? Two options come up almost every time: a Recurring Deposit at the bank, or a SIP in a mutual fund. Both take fixed monthly amounts. Both are accessible. But that’s roughly where the similarities end. The rd vs sip debate isn’t really about which is “better” in an absolute sense, it’s about which one fits your situation. This article breaks that down clearly.

    What Is a SIP?

    A Systematic Investment Plan is a fixed amount of money that you put into a mutual fund scheme at regular intervals, usually on a monthly basis. Every month, that money buys up units of a mutual fund based on the price of the fund on that particular day – the Net Asset Value, or NAV for short.

    When the market is down, your fixed amount gets you more units for your money. And when the market is up, it gets you fewer units. But the good news is that over time, it actually levels out the cost per unit you bought, a process called rupee cost averaging. It’s not about being a genius at timing the market; its about staying invested no matter whether the market is going up, down or sideways.

    SIP’s are pretty flexible – you can start one with as little as ₹100 a month on most platforms. And you’re not locked in either – most places let you pause, stop or even increase the amount you’re putting in without any penalty. But – and this is a big but – the returns are entirely market-linked, so theres no fixed number you can bank on.

    What Is an RD?

    A Recurring Deposit is one of the ways that banks and post offices try to get you to save a bit more money. You put in a fixed amount of cash every month for a set period of time and they pay you interest on that amount at a rate they agree on when you set it up. At the end of the set time period, they hand over the lot – the original amount you put in plus all the interest you earned – in one lump payment.

    In many ways, a RD is just a savings product with a fancy investment label. You know right from the start what you’re going to get back – it’s based on the interest rate they agreed on. Whether the market goes up or down, your money keeps on earning interest at that fixed rate. And that can be a pretty valuable thing for certain types of goals and for certain types of investors.

    As of 2026, major banks are offering the following RD rates:

    BankGeneral Citizen RateSenior Citizen Rate
    SBI6.5% p.a.7.0% p.a.
    HDFC Bank6.7% p.a.7.2% p.a.
    ICICI Bank6.6% to 7.0% p.a.7.0% to 7.5% p.a.
    Axis Bank6.5% p.a.7.2% p.a.
    Post Office RD6.7% p.a.6.7% p.a.

    Post Office RDs are backed by the Government of India and are among the safest options available. Bank RDs up to ₹5 lakh per depositor are covered under DICGC insurance.

    Difference Between SIP and RD: A Head-to-Head Look

    This is the core of the sip vs rd question. The two products look similar on the surface, with monthly contributions and long tenures, but differ on almost every meaningful parameter underneath.

    ParameterSIPRD
    ReturnsMarket-linked, not guaranteed. Historical equity SIP returns range from 12-15% CAGR over 10+ yearsFixed, guaranteed. Currently 6.5%-7% at most major banks
    RiskModerate to high depending on fund typePractically nil
    TenureNo fixed tenure; you decide when to stop6 months to 10 years, fixed at opening
    Minimum Amount₹100 per month on most platforms₹100–₹500 depending on the bank.
    TaxationSTCG at 20% on equity funds; LTCG at 12.5% above ₹1.25 lakhInterest taxed at slab rate; TDS if interest exceeds ₹40,000 in a year
    LiquidityCan redeem anytime; exit load may apply within 1 yearPremature withdrawal allowed with penalty; no partial withdrawal
    Inflation BeatEquity SIPs historically beat inflation over long periodsFixed returns often lag inflation over long tenures
    Best ForLong-term wealth creationShort-term goals, capital protection, conservative investors

    Read Also: Daily SIP vs Monthly SIP: Which SIP is Better?

    SIP vs RD: The Return Difference Over Time

    Numbers help here. Suppose you invest ₹5,000 per month for 10 years.

    With an RD at 7% p.a. (current rate):

    • Total invested: ₹6,00,000
    • Maturity amount: approximately ₹8.67 lakh

    With an equity SIP at 12% CAGR (conservative long-term estimate for diversified equity funds):

    • Total invested: ₹6,00,000
    • Estimated corpus: approximately ₹11.61 lakh

    That’s a gap of roughly ₹3 lakh on the same monthly investment over 10 years. Push the SIP return assumption to 15%, which many large-cap and flexi-cap funds have delivered over 10-year rolling periods, and the corpus jumps to approximately ₹13.93 lakh. Nearly double the RD.

    The caveat is real, though. SIP returns aren’t guaranteed. A bad decade, heavy market corrections, slow recovery can compress those returns significantly. RD will deliver exactly what it promised.

    Difference Between RD and SIP on Tax

    This is where many investors get surprised.

    RD interest is fully taxable as income. Every rupee of interest you earn gets added to your total income and taxed at your applicable slab rate. If you’re in the 30% bracket, 30% of your RD interest goes to tax. TDS at 10% is also deducted if your interest income from a single bank exceeds ₹40,000 in a financial year (₹50,000 for senior citizens as of April 2025 revision).

    SIP taxation depends on the type of fund and how long you stay invested:

    • Equity fund units held for more than 1 year attract LTCG tax at 12.5% on gains above ₹1.25 lakh per year
    • Units redeemed within 1 year are taxed at 15% (STCG)
    • Debt fund gains are taxed at slab rate regardless of holding period (post-2023 amendment)

    For an investor in the 30% slab, a well-held equity SIP is significantly more tax-efficient than an RD. The 12.5% LTCG vs 30% slab rate difference compounds meaningfully over a 10-year period.

    ELSS mutual funds, a specific category of equity funds, also give you a deduction of up to ₹1.5 lakh under Section 80C if you invest through SIP. RDs offer no such tax benefit.

    When Does RD Make More Sense Than SIP?

    The difference between SIP and RD isn’t always in favour of SIP. There are real situations where an RD is the right call.

    • Short time horizon: If you need the money in 1–2 years, a wedding, a vehicle purchase, a home down payment, equity SIPs are unsuitable. Markets can be down 20–30% at the exact point you need to withdraw. An RD locks in your rate and delivers exactly what you planned for.
    • Cannot handle volatility: If a 20% drop in your investment value will cause you to panic and redeem, an equity SIP will likely hurt you. The strategy only works if you stay through corrections. For an investor who genuinely can’t, an RD prevents self-inflicted losses.
    • Senior citizens and fixed income needs: RD rates for senior citizens go up to 7.5% at some banks, nearly risk-free income that beats savings account rates comfortably. For someone drawing down savings rather than building them, the predictability of an RD is practical, not conservative.
    • Emergency fund building: An RD is a better structure for building an emergency fund than a SIP. Liquidity with a penalty is better than liquidity with market risk when you might need the money unexpectedly.

    When Does SIP Make More Sense Than RD?

    • Long time horizon: If your goal is 7 years away or more, retirement, children’s education, buying a house in a decade, equity SIPs have historically delivered returns that leave RDs far behind. Time is the variable that converts market volatility from a risk into an advantage.
    • Beating inflation: Inflation in India has averaged around 5–6% over the long run. An RD at 6.7% leaves you with a real return of roughly 0.7–1.7%, barely above zero after tax. An equity SIP compounding at 12% over a decade generates real wealth that actually outpaces rising costs.
    • Tax efficiency: For investors in higher tax brackets, the tax treatment of equity SIP gains, especially LTCG at 12.5% for long-term holdings, is significantly more efficient than RD interest taxed at slab rate.
    • Flexible goals: SIPs have no fixed maturity. You invest as long as you want and redeem when your goal is met. An RD locks your tenure at the start, and breaking it early comes with penalties.
    • ELSS SIPs for tax saving: If you’re looking to exhaust your Section 80C limit of ₹1.5 lakh, an ELSS SIP serves double duty, wealth creation and tax deduction simultaneously. No RD does this.

    RD or SIP, Which is Better, A Practical Decision Framework

    Rather than a blanket recommendation, here’s a cleaner way to think about it:

    Your SituationBetter Option
    Goal is less than 3 years awayRD
    Goal is 7+ years awaySIP (equity fund)
    Cannot tolerate any loss of principalRD
    Want to beat inflation over the long runSIP
    Senior citizen needing stable incomeRD
    Salaried investor in high tax bracketSIP (for tax efficiency)
    Building emergency fundRD
    Saving for retirement 20 years awaySIP
    Want Section 80C benefitELSS SIP

    Many investors do both, an RD for near-term goals and capital protection, and SIPs running in parallel for long-term wealth creation. The two aren’t mutually exclusive.

    How to Start a SIP Through Pocketful

    If you want to start investing in mutual funds the right way, Pocketful makes the entire process simple and structured. Here’s how you can get started:

    Step 1: Create Your Account

    The first step is to download the Pocketful app and sign up. The registration process is quick and takes only a few minutes.

    • Enter your mobile number and verify with OTP
    • Set your login credentials
    • Access your personal dashboard

    Step 2: Complete Your KYC

    KYC is mandatory before you can invest in any mutual fund in India. On Pocketful, the entire KYC process is online and paperless.

    • Add your PAN and Aadhaar details
    • Enter your bank account information
    • Complete the verification process

    Step 3: Select a Mutual Fund

    Once your account is ready, you can browse mutual funds based on your goal, risk appetite, and investment horizon. Pocketful lists funds across all major categories.

    • Choose from equity, debt, hybrid, or index funds
    • Filter by AMC, fund rating, or past performance
    • Compare expense ratios before finalising

    Step 4: Start Your SIP or Lump Sum Investment

    Decide how you want to invest through a monthly SIP or a one-time lump sum. SIPs can be started with as little as ₹100 per month.

    • Set your SIP amount and date
    • Choose the fund and confirm your investment
    • Track your SIP performance directly from the dashboard

    Pocketful gives you access to direct mutual fund plans with zero commission, so your expense ratio stays low and more of your money stays invested.

    Read Also: SIP vs Lump Sum: Which is Better?

    Conclusion

    The sip vs rd debate comes down to one question, how long can you stay invested and how much uncertainty can you live with? RDs deliver exactly what they promise, with zero surprises. SIPs can deliver significantly more over long periods, but the ride involves dips, corrections, and years where returns look flat. Neither is universally superior. A 25-year-old saving for retirement doesn’t need the certainty an RD provides; they need growth. A 58-year-old saving for a foreign trip next year doesn’t need market exposure; they need predictability. Know your goal, know your timeline, and the answer to rd or sip which is better usually becomes obvious.

    Start your SIP journey with Pocketful and invest in mutual funds with zero commission, so more of what you earn stays with you.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1SIP in Stocks vs SIP in Mutual funds?
    2Bank of Baroda vs SBI Bank: Which is Better?
    3PNB Vs Bank of Baroda: Which is Better?
    4MRF vs Apollo Tyres: Which is Better?
    5Bank of Baroda Vs Canara Bank: Which is Better?

    Frequently Asked Questions (FAQs)

    1. Which is better for a salaried person, SIP or RD? 

      For a salaried person with a long-term goal like retirement or buying a house in 10+ years, a SIP in a diversified equity fund typically makes more sense. For near-term goals within 2–3 years, an RD is more appropriate. Many salaried investors run both simultaneously.

    2. Can I lose money in a SIP? 

      Yes, you can. SIPs are market-linked and returns are not guaranteed. In the short term, the value of your investment can fall below the amount you invested. Over longer periods of 7–10 years, the probability of negative returns from diversified equity SIPs has historically been very low, but it’s not zero.

    3. Is RD interest fully taxable? 

      Yes. Interest earned on RDs is added to your total income and taxed at your applicable slab rate. If interest from a single bank exceeds ₹40,000 in a financial year, TDS at 10% is deducted.

    4. Can I stop a SIP midway? 

      Yes, you can pause or stop a SIP at any time without penalty. The units already accumulated remain in your folio and continue to reflect the fund’s NAV. Stopping a SIP does not mean redeeming, you can redeem separately.

    5. What happens if I miss an RD instalment? 

      Banks typically charge a penalty for missed RD instalments. Multiple consecutive missed payments can lead to the RD being foreclosed. Most banks deduct the penalty from the maturity amount rather than requiring immediate payment.

    6. What is the minimum investment for a SIP? 

      Most platforms and mutual fund houses allow SIPs starting from ₹100 per month. Some fund schemes have a minimum of ₹500 or ₹1,000, but the entry point has dropped significantly in recent years.

    7. Is SIP better than RD for 5 years? 

      For a 5-year horizon, it depends on your risk tolerance. A hybrid or balanced advantage fund SIP may be appropriate if you can accept moderate volatility. A pure equity SIP over 5 years carries more risk than over 10 years. An RD gives you guaranteed returns with zero uncertainty. Many financial advisors suggest a mix, partial SIP in hybrid funds, partial RD, for a 5-year goal.

    8. Do RDs beat inflation? 

      At current rates of 6.5–7%, most RDs barely beat India’s average inflation of around 5–6%, and that’s before tax. After paying income tax on the interest at your applicable slab rate, the real return on an RD can turn negative for investors in higher tax brackets.

  • Mutual Fund Portfolio Tracking: A Complete Guide

    Mutual Fund Portfolio Tracking: A Complete Guide

    Financial progress must be actively monitored by individuals. A powerful driving force for that is mutual funds. Through mutual funds, savings are grown over time. However, an ideal approach is not just investing money and forgetting about it. 

    Financial markets move constantly. Economies change every single day. Therefore, investments must be tracked. Portfolios are regularly observed by investors.

    What is a Mutual Fund Portfolio?

    A mutual fund portfolio refers to a set of various mutual fund schemes in the possession of an individual investor. It gives a complete picture of the approach adopted by the investor in making investments, their objectives as well as their risk profile. In other words, it acts as a financial basket of various mutual funds.

    For example, an investor might hold a large cap equity fund, a short term debt fund, and a gold fund. These three funds together make up the mutual fund portfolio. This careful mix helps spread the risk across different asset classes. Proper diversification ensures that a loss in one sector might be balanced by gains in another.

    Every individual has a unique financial situation. Therefore, every portfolio will look slightly different from another. A young professional might have a portfolio filled with high growth equity funds. An older individual nearing retirement might prefer a portfolio focused on highly stable debt funds.

    The contents of the portfolio define how fast the wealth will grow over the years. It also determines the level of risk the investor is taking. Knowing the exact makeup of this portfolio is a basic requirement for achieving financial stability.

    Ways to Monitor a Portfolio

    Monitoring investments does not have to be a complicated task. There are several efficient ways to keep track of mutual fund performance. The right method depends on individual convenience and the total number of investments. Here are the primary ways to track a portfolio:

    1. Online Portfolio Trackers

    An online portfolio tracker is a highly effective tool for observing mutual fund investments. These digital platforms provide a clear and consolidated view of all holdings in a single place. Users just need to sign up using an email address and a Permanent Account Number (PAN).

    Platforms allow investors to view the Extended Internal Rate of Return (XIRR) and track overall profit easily. These trackers save precious time and remove the need to maintain complicated data spreadsheets.

    2. Asset Management Company Websites

    Every fund house or Asset Management Company (AMC) has an official website. Investors can log in to these portals to check the performance of their specific funds. This method is direct and provides authentic data right from the original source.

    However, this approach can take a lot of time if investments are spread across multiple different fund houses. Logging into five different websites to check a few funds is not very practical. This approach works best for people who invest all their money with a single fund house.

    3. Consolidated Account Statement

    The Consolidated Account Statement (CAS) is a unified document containing all mutual fund investments linked to a single PAN. Depositories like the National Securities Depository Limited (NSDL) send this statement directly to registered email addresses. It acts as a complete portfolio detailed on a single page.

    Investors can also download this statement from platforms like CAMS or KFintech. This monthly statement is an excellent way to maintain a secure record of all financial transactions. Many people use this document specifically during tax filing season to calculate capital gains easily.

    4. Mutual Fund Factsheets

    A mutual fund factsheet is basically a monthly report card released by the AMC. It shows the overall health of the mutual fund scheme clearly. This document contains deep insights into where the fund manager is investing the money.

    It displays the sector allocation, risk ratings, and the historical performance of the fund. The factsheet compares the fund returns against a standard market index. Regularly reading these sheets helps investors build solid financial knowledge over time.

    Tracking MethodPrimary BenefitBest Suited For
    Online TrackersConsolidated view with advanced analyticsInvestors with multiple funds across different AMCs
    AMC WebsitesDirect and authentic updatesInvestors dealing with only one fund house
    CAS DocumentOfficial record for taxation and safetyLong term record keeping and fraud prevention
    FactsheetsDeep insights into fund manager strategyDetailed analysis of scheme health and holdings

    Read Also: How to Build a Mutual Fund Portfolio

    Importance of Tracking Mutual Fund Portfolio

    Tracking investments is just as crucial as making the initial investment. Regular monitoring brings several key benefits and transforms a passive saver into a smart investor. Here is why tracking holds immense importance:

    • Know the Progress: Checking a portfolio regularly reveals how the investments are growing over time. It gives a transparent view of the entire financial journey. Acknowledging the gains builds confidence, while noticing the losses allows for timely course correction.
    • Stay In Control: A mutual fund portfolio is like a beautiful garden that needs constant care. Regular tracking helps identify underperforming funds before they cause significant financial damage. Without monitoring, bad funds will drag down the overall returns of a good portfolio.
    • React to Market Changes: The financial market constantly moves through ups and downs. A well monitored portfolio allows the investor to react promptly to sudden market changes. If a particular fund fails to perform, the money can be moved to a potentially more profitable option.
    • Tax Planning: Every financial investment decision eventually leads to some tax implication. Keeping a close eye on the portfolio helps in planning taxes very effectively. Knowing the exact holding period of each fund prevents heavy tax penalties on capital gains.
    • Ensure Goal Alignment: Investments are usually tied to life goals like retirement or a child education fund. Tracking ensures that the chosen funds are actually moving toward these specific targets. It stops the investor from getting distracted by short term market noise.

    What to Track in a Mutual Fund Portfolio

    Knowing exactly what to look for makes portfolio monitoring much more effective. Investors must focus on a few specific elements to ensure good health for their investments. Here are the most critical factors to track:

    • Fund Performance Against Benchmarks: It is essential to compare a fund return against its benchmark index. The Securities and Exchange Board of India (SEBI) mandates the use of a Total Return Index (TRI) for this fair comparison. This index includes both the stock price changes and the received dividends. A fund must consistently match or beat this benchmark.
    • Asset Allocation Mix: Asset allocation is the distribution of money across equity, debt, and cash. Market movements can easily disturb this original balance over time. Tracking helps ensure the portfolio stays strictly aligned with the intended risk tolerance.
    • Portfolio Rebalancing Needs: Sometimes a specific asset class grows much faster than others. Tracking highlights the exact moment when rebalancing is required to bring the risk back to normal levels. Rebalancing involves selling some profitable assets and buying cheaper ones to maintain balance.
    • Changes in Fund Strategy: AMCs sometimes change the core mandate of a fund. Investors must track these changes to ensure the new strategy still supports their original financial goals. Investors need to spot internal changes early to avoid taking unwanted risks.
    • Reviewing SIPs: A Systematic Investment Plan (SIP) needs occasional adjustments based on income changes. Regular tracking helps in planning a step up in contributions to match rising inflation. The investment amount must increase proportionally to beat the high cost of living.
    • Portfolio Overlap: Investors often buy multiple funds that invest in the exact same companies. For instance, two different equity funds might hold shares of the same large banks. This creates portfolio overlap and reduces the benefit of diversification. Checking overlap ensures that the investor is not paying multiple fees for the same stock exposure. Online overlap tools help identify these common stocks easily.
    Metric to TrackWhy It MattersAction to Take
    Benchmark ComparisonShows if the fund is truly performing wellExit funds that constantly underperform the TRI
    Asset AllocationControls the overall portfolio riskShift funds between equity and debt when needed
    Portfolio OverlapPrevents investing in the same stocks twiceRemove duplicate funds to ensure true diversification
    SIP AmountsEnsures savings match inflation ratesIncrease SIP contributions as yearly income grows

    Read Also: How to Evaluate Mutual Fund Company Performance

    Conclusion

    Tracking a mutual fund portfolio is a highly rewarding financial habit. It creates a deep sense of financial security and overall awareness. Regular monitoring removes the fear of the unknown from the entire investing journey.

    By using modern tools and platforms, anyone can manage their wealth effortlessly. Staying updated on fund performance, asset allocation, and market trends builds a solid financial foundation. A well maintained portfolio stands strong against market volatility.

    In the end, steady discipline remains the true key to financial freedom. Celebrating the continuous growth of investments provides great motivation for a prosperous and stress free life.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Top Gold Mutual Funds in India
    2Best Silver Mutual Funds to invest in India
    3Best Brokers for Mutual Funds
    4Best Gold Investment Schemes in India
    5Best Money Market Mutual Funds in India

    Frequently Asked Questions (FAQs)

    1. What is the meaning of a mutual fund portfolio? 

      It is a collection of various mutual fund schemes held by an investor, designed to achieve specific financial goals through proper diversification.

    2. What are the main benefits of tracking a portfolio? 

      Tracking helps monitor financial progress, control risks, and align investments with life goals. It is also highly useful for planning taxes effectively.

    3. How to use an online portfolio tracker? 

      Users can sign up with an email address and a PAN to use a tracker. It gives a consolidated, real-time view of all investments.

    4. What is a Consolidated Account Statement? 

      It is a single document detailing all mutual fund transactions across different fund houses. It links everything to one PAN for easy tracking.

    5. How often should a portfolio be reviewed? 

      Reviewing a portfolio once or twice a year is sufficient for most long term investors. It should also be reviewed during major life events.

  • Open Free Demat Account

    Join Pocketful Now

    You have successfully subscribed to the newsletter

    There was an error while trying to send your request. Please try again.

    Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.