Blog

  • Terminal Value: Meaning, Formula & How to Calculate

    Terminal Value: Meaning, Formula & How to Calculate

    Understanding the true worth of a business takes patience and proper analysis. Analysts often project earnings for the next few years to see where a company stands today. However, strong businesses usually last much longer than a short forecast period.

    Finding the intrinsic worth of those distant future years completes the entire financial puzzle. This guide breaks down the concept into simple terms. Readers will discover the basic math and logic used by experts to measure long-term growth and profits.

    What Is a Terminal Value?

    When looking at a business, forecasting cash flows for the next five or ten years is a standard practice. Beyond that timeline, predicting exact numbers becomes extremely difficult. This is where a specific financial concept steps in to save time and effort.

    In simple terms, the terminal values meaning revolves around the estimated worth of a company beyond a set forecast period. Instead of guessing exact profits year after year until the end of time, analysts use one single number to represent all those future years. This concept assumes that a mature business will grow at a steady pace forever.

    When a firm is young, its growth is often rapid and unpredictable. It is relatively easy for experts to map out high growth for the next five years. Because no one can predict exact cash flows forever, analysts impose closure on their models. They stop estimating individual yearly cash flows at a future point.

    At this cutoff point, they compute one final value that reflects the worth of the firm as a going concern from that day forward. It makes up a massive chunk of a company’s total valuation, sometimes reaching up to eighty percent. Understanding this idea is essential for anyone trying to figure out the true intrinsic worth of a stock.

    Terminal Value Formula

    Analysts rely on specific math equations to find this future estimate. The exact terminal value formula depends entirely on the method chosen for the valuation.

    Here are the two main ways to approach the math:

    1. Perpetuity Growth Method

    This approach assumes a business will grow at a stable rate forever. The formula is: 

    Terminal Value = (Free Cash Flow * (1 + g)) / (WACC – g).

    Here, the free cash flow is the cash generated in the last forecasted year. The WACC stands for the Weighted Average Cost of Capital, and the letter ‘g’ stands for the perpetual growth rate.

    2. Exit Multiple Method

    This method uses current market data from similar companies. The formula is: 

    Terminal Value = Financial Metric * Exit Multiple. 

    The financial metric is usually a final year profit figure like earnings before interest, taxes, depreciation, and amortisation.

    Let us look at an example of terminal value using the first method. Suppose a firm has a final year cash flow of ₹100, a perpetual growth rate of 3 percent, and a cost of capital of 10 percent.

    To calculate terminal value, one would apply the numbers like this: 100 * (1 + 0.03) / (0.10 – 0.03). The final result comes out to ₹1,471.43. This specific figure represents what the business is expected to be worth after the initial forecast period ends.

    Methods of Calculating Terminal Value

    There are two popular methods to calculate this metric in the financial world. Each method has its own logic and suits different types of companies.

    • The Perpetuity Growth Method: This approach works best for mature and stable companies. It assumes the business will keep growing at a very slow, constant pace forever. The growth rate chosen here is usually tied to the overall economic growth of the country. It typically sits between two to four percent. A company cannot grow faster than the overall economy forever, otherwise it would eventually become larger than the economy itself.
    • The Nuances of Growth: Experts often debate what the correct constant growth rate should be. A safe proxy for this long-term rate is the risk-free interest rate of the country. Using a conservative rate prevents the final valuation from exploding into unrealistic numbers. Additionally, the growth rate can even be negative if a company is expected to slowly lose market share over time. While it provides a smooth theoretical value, it is very sensitive to small changes in the assumed growth rate.
    • The Exit Multiple Method: This approach is more practical and market-driven. It looks at how similar businesses are priced in the market today. If a rival company sells for ten times its earnings, the same multiple is applied to the target company’s projected future earnings. Analysts often prefer this method for younger, faster-growing companies or when a buyout is expected.
    • The Flaws of Multiples: This method completely avoids the trap of guessing a permanent growth rate. However, this method mixes relative market pricing with fundamental intrinsic valuation. If the entire stock market is currently overvalued, the final estimate will also be artificially inflated.

    Read Also: What is Option Premium & How is it Calculated?

    How to Calculate Terminal Value

    First, analysts project the expected free cash flows for a specific period. This is usually a window of five to ten years. This window is known as the explicit forecast period.

    Next, one must choose the correct terminal value formula based on the company’s maturity. If using the growth method, the final year’s cash flow is factored in with a realistic long-term growth rate. The growth rate must be lower than the discount rate to keep the calculation mathematically sound.

    Finally, the calculated figure must be discounted back to the present day. A sum of money in the future is worth less than the same amount today. Discounting brings that future value down to current terms, completing the entire valuation process.

    It is vital to avoid common mistakes during this final step. Many analysts forget to discount the final number back to the present date. Adding the undiscounted future number directly to today’s cash flows will heavily overstate the final price.

    Terminal Value Vs Instrumental Value

    People often confuse these two terms because they sound similar. However, they belong to completely different fields of study.

    AspectTerminal ValueInstrumental Value
    Basic MeaningRepresents the estimated financial worth of a business at the end of a specific forecast period.Represents the value of a specific behaviour or trait based on its usefulness in achieving an end goal.
    Main FocusFocuses on the final financial outcome or the end result of a valuation process.Focuses on the usefulness of an action to achieve a desired outcome.
    Use in FinanceIt is a vital and heavily used component in corporate business valuation models.It is a psychological or ethical concept and is not used in business valuation.
    Example ApplicationCalculating the present value of future cash flows for a stock listed on the market.Developing traits like honesty or ambition that help an individual achieve a comfortable life.

    Importance of Terminal Value in Valuation

    This single metric plays a massive role in the world of investing. It is not just a backup number, it is a core pillar of financial analysis.

    • Captures Long-Term Worth: Businesses do not simply close down after a five-year forecast. This number ensures the ongoing, long-term potential of the company is properly counted in the final price.
    • Carries the Highest Weight: In most discounted cash flow models, this estimate makes up between sixty to eighty percent of the company’s total worth. Therefore, it dictates the final valuation heavily and requires careful attention.
    • Simplifies Complex Math: Guessing cash flows for thirty or forty years into the future is impossible. This estimate reduces the complexity by providing one solid, manageable number.
    • Exposes Valuation Flaws: Unrealistic assumptions hidden in the final year of a model are instantly exposed when the growth rate is compared against normal economic growth. If an analyst claims a stock is cheap, reviewing this specific calculation often reveals the hidden truth.
    • Helps in Decision Making: A positive result signals strong long-term wealth creation for investors. Conversely, a negative result acts as a warning sign of declining cash flows. 

    Conclusion

    Understanding a company’s distant future worth brings great clarity to the investment process. While financial forecasting naturally involves many assumptions, having a structured approach makes the stock market much less intimidating. By breaking down long-term growth into a single manageable number, investors gain a much deeper appreciation for business fundamentals. Tools and platforms are readily available today to help verify these financial metrics with ease. Taking the time to study these numbers results in smarter, safer, and more confident financial decisions over a lifetime.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1Short Straddle: Option Strategy with Examples
    2Top Algorithmic Trading Strategies
    3What is Zero Days to Expiration (0DTE) Options and How Do They Work?
    4Types of Traders in the Stock Market: Styles, Strategies & Pros and Cons
    5Risk Management In Trading
    6Understanding Futures Pricing Formula

    Frequently Asked Questions (FAQs)

    1. What is the meaning of Terminal value concept? 

      It refers to the estimated financial worth of a business beyond its initial projected forecast period, assuming stable operations forever.

    2. What are its main benefit of terminal values? 

      It simplifies long-term financial forecasting into one manageable number. This helps capture the permanent worth of a company without guessing decades of exact data.

    3. How to use Terminal Value in market analysis? 

      Analysts discount this future estimate back to present terms. They add it to near-term cash flows to find a stock’s true intrinsic price.

    4. What is a perpetual growth rate? 

      It is a small, constant rate at which a mature company is assumed to grow forever. It typically stays between 2 to 4 percent.

    5. Does it impact the final company value? 

      Yes, it often represents 60 to 80 percent of a firm’s total valuation, making it the most important driver in a financial model
  • How To Use Directional Movement Index In Trading?

    How To Use Directional Movement Index In Trading?

    While it may seem easy to place a trade based on a sharp rise or fall in a stock within the Indian market, the real challenge lies in identifying the correct trend. The Directional Movement Index (DMI) can help improve this understanding. In this blog, we will explore how to interpret and use it in trading.

    What Is the Directional Movement Index? 

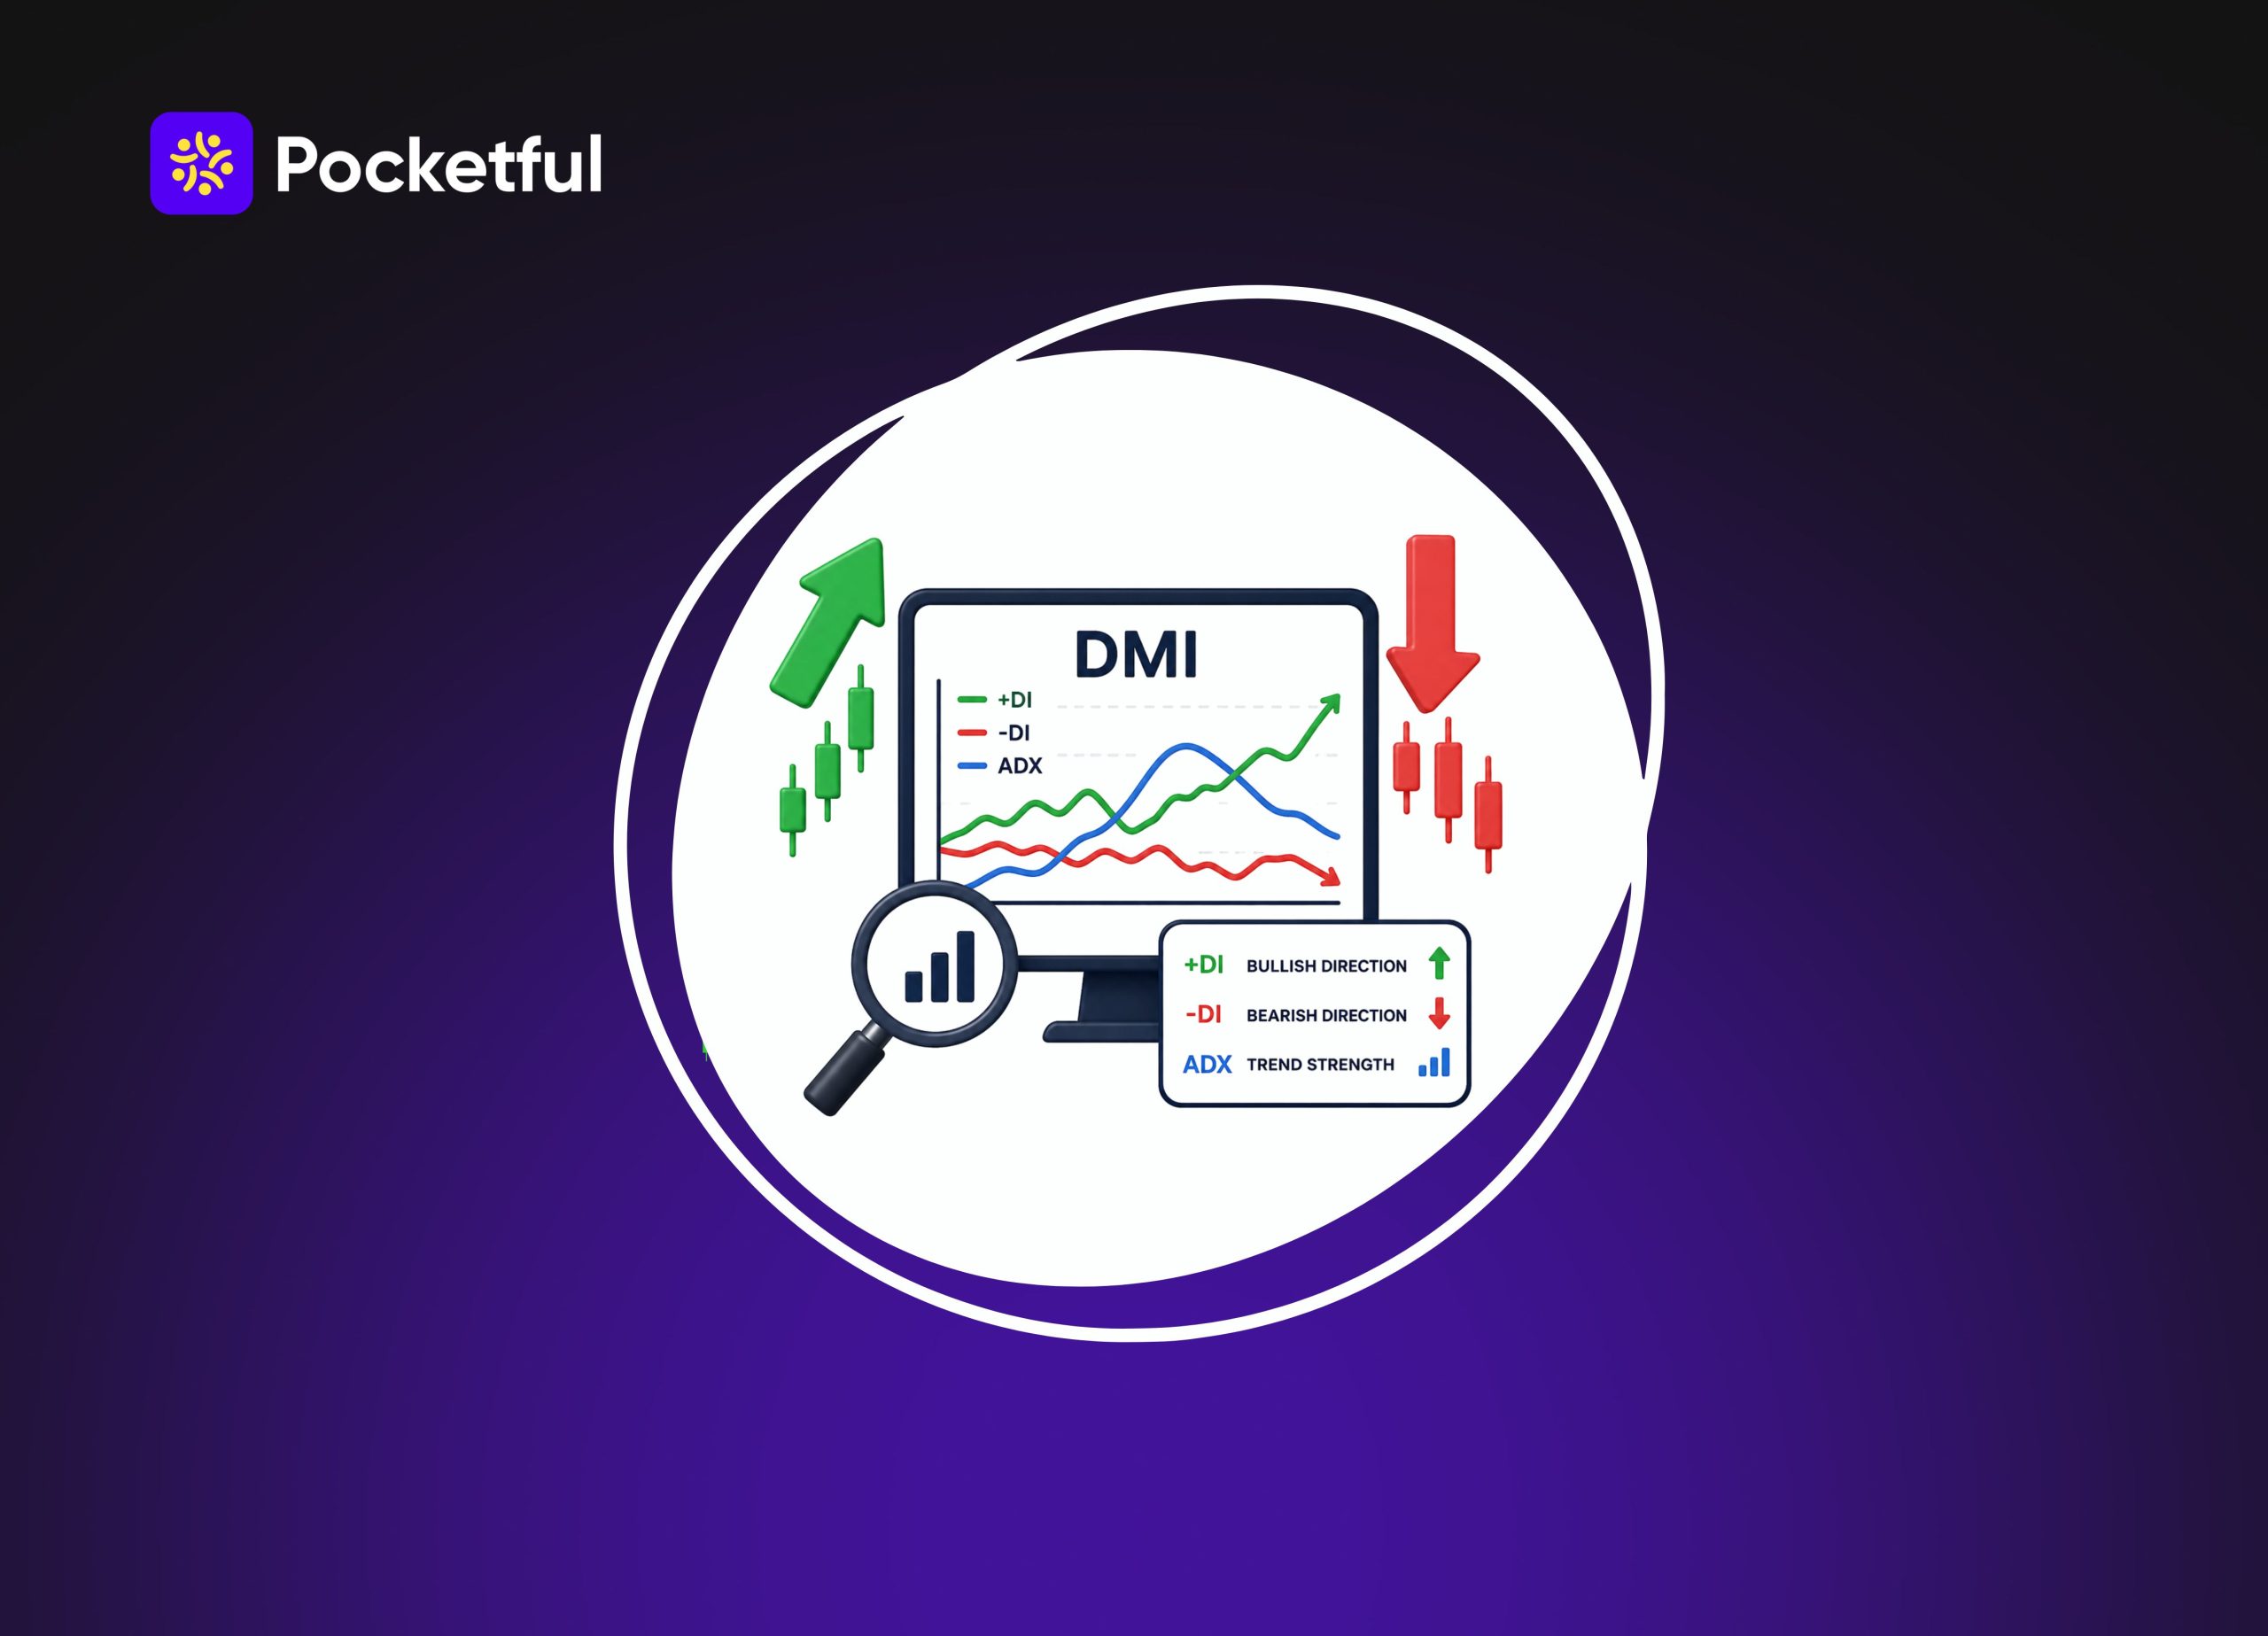
    The Directional Movement Index (DMI) is a technical analysis indicator used to understand the direction and strength of a trend in a stock or index. It was developed by Welles Wilder. The DMI system consists of three main components: +DI, -DI, ​​and ADX. Typically, the default look-back period is set to 14, although this can be adjusted based on the trading timeframe.

    Three main components of DMI

    Component What does it indicate?
    +DIStrength of upward price movement
    -DIStrength of downward price movement
    ADXHow strong is the trend?

    How Does the DMI Indicator Work? 

    By comparing price movements, the DMI helps determine whether buying or selling pressure is stronger in the market. Its functioning can be understood through a few key steps.

    Step 1: Comparing Price Movement

    First, the high and low of the current candle are compared with those of the previous candle. This reveals which movement upward or downward is more significant.

    Step 2: Determining +DM and -DM

    If the upward movement is stronger, it is classified as Positive Directional Movement (+DM). Conversely, if the downward movement is stronger, it is classified as Negative Directional Movement (-DM).

    Step 3: Incorporating True Range

    Next, the True Range (TR) is used to measure the actual price movement. The +DM, -DM, and TR values ​​are processed using Wilder’s smoothing method.

    Step 4: Deriving +DI and -DI

    The +DI and -DI values ​​are calculated from the smoothed figures. By observing the positions of these two lines on the chart, a trader can gauge whether the upward or downward directional movement is stronger.

    Step 5: ADX Indicates Trend Strength

    Finally, the gap between +DI and -DI gives us the DX, which gets smoothed out to form the ADX. This indicator measures pure trend strength, though it won’t tell you which direction price is actually moving.

    How to Read +DI, -DI and ADX? 

    To interpret the DMI correctly, simply observing the crossover of the lines is not enough. It is essential to analyze all three components together to understand the market’s direction and the strength of the move.

    What does it mean when +DI is above -DI?

    When +DI remains above -DI, ​​the upward directional movement is considered relatively strong. If the stock price is simultaneously forming higher highs and higher lows, this can support the existence of a bullish trend. However, entering a trade solely based on a DI crossover is not the right approach.

    What does it indicate when -DI is above +DI?

    If -DI rises above +DI, it indicates that the downward directional movement is strengthening. For instance, if an NSE stock is consistently forming lower highs and lower lows while -DI is above +DI, this can provide additional confirmation of a bearish trend.

    How do you read the ADX?

    ADX simply shows trend strength, not which way prices are moving. As a quick rule, a reading past 25 usually means a solid trend is underway, whereas anything below 20 tells you the market is weak or just drifting sideways. That 20 to 25 zone stays pretty ambiguous. Don’t treat these as hard trading rules; they’re basic reference points.

    Read Also: What is Price Action Trading & Price Action Strategy?

    How to Use DMI in Trading: A Practical Process 

    The DMI is best utilized when viewed as part of a complete trading setup. Its purpose is not to take a trade on every signal, but rather to filter for superior setups.

    • Assess the Setup on the Chart: First, check whether a setup such as a breakout, pullback, or trend continuation is forming in the stock.
    • Mark Key Levels: Identify recent highs, lows, support, and resistance levels. These levels will assist in planning your entry and exit.
    • Seek Confirmation from the DMI: Next, check if the DMI reading aligns with your setup. If both the price and the indicator point in the same direction, the setup becomes more compelling.
    • Determine Risk Before Entry: Decide on your stop-loss and position size before executing the trade. This makes it easier to keep losses under control in the event of a false signal.

    How to Use DMI for Intraday Trading in India? 

    In intraday trading, it is essential to interpret the DMI alongside short-term price movements. A practical approach involves observing the trend on a 15-minute chart and then determining the entry timing on a shorter timeframe.

    • Start with the 15-Minute Chart: First, examine the overall DMI reading on the 15-minute chart. This provides better context regarding the direction of the trading session compared to shorter timeframes.
    • Determine Entry Timing on the 5-Minute Chart: Once the broader setup is clear, you can look for entry opportunities on the 5-minute chart. Here, changes in the DMI lines should be considered significant only if the price is also moving in the same direction.
    • Manage the Position During a Strong Move: If the trade moves in your favor, monitor price behavior rather than relying solely on a fixed target. If the DMI strength begins to wane, it may be time to review the position.
    • An Important Precaution for Intraday Trading: The DMI is a lagging indicator; consequently, signals often appear after the price movement has already begun. This means that using it to catch the exact top or bottom is not the right approach.

    DMI for Swing Trading: What Changes? 

    In swing trading, the DMI is used not for capturing minor intraday price fluctuations, but for identifying trends that persist over several days. Consequently, both the chart timeframe and the trade’s holding period are crucial factors.

    • Observe the Trend on the Daily Chart: Swing traders typically begin by analyzing the daily chart. This approach filters out short-term market noise, making it easier to understand the stock’s broader price movement.
    • Pay Attention to Pullbacks: Consider a scenario where a stock is in an uptrend and approaches a support level following a decline over a few sessions. By examining the DMI readings, a trader can assess whether this is merely a temporary pullback or if the trend is genuinely weakening.
    • Review Based on the Holding Period: Since a swing trade position may be held for several days, it is not necessary to alter your decision based on every minor fluctuation in the DMI. It is more practical to re-evaluate the trade only when there is a significant shift in the price structure or the overall trend.

    DMI With Other Technical Tools: What Actually Adds Value? 

    The DMI alone does not constitute a complete trading setup. However, choosing the right combination makes it easier to interpret price, trend, and market activity simultaneously.

    1. DMI + Price Action

    Price action provides the “ground reality” for the DMI. If the indicator signals a specific direction, check the chart to see if the candlesticks support that move. This helps avoid making decisions based solely on the indicator.

    2. DMI + Moving Average

    Moving Averages help identify the broader trend direction of a stock, while the DMI helps assess the strength of that trend. The two can be used together, particularly to filter and refine trend-following setups.

    3. DMI + Volume

    If volume rises alongside a price movement, that move warrants closer attention. Observing volume in conjunction with the DMI especially during breakouts in Indian stocks can provide useful confirmation.

    Common Mistakes While Using DMI

    The biggest mistake in understanding the DMI is interpreting the indicator without considering the market context. By avoiding certain common errors, its signals can be utilized more practically.

    • Treating Every Crossover as a Trade: Taking a position immediately upon seeing a +DI and -DI crossover is not the right approach. In a sideways market, such signals can occur frequently, often lacking strong follow-through.
    • Mistaking ADX for Direction: The ADX indicates only the strength of a trend. A rising ADX is not inherently a bullish signal; it can rise even during a strong downtrend.
    • Treating Fixed Levels as Absolute Rules: ADX levels like 20 or 25 serve as useful reference points, but it is unwise to treat them as fixed entry rules across every stock and timeframe. The context of a signal can shift depending on market conditions.
    • Relying Solely on the Indicator: The DMI is just one component of technical analysis. It is more sensible to make decisions by considering it alongside price behavior and other relevant market information.

    Read Also: Best Indicators for Swing Trading

    Conclusion

    The DMI cannot give you a precise prediction of every market move, but it can certainly help you understand the trend. For Indian stocks, it is more practical to use it in conjunction with price action and risk management. Ultimately, having a clear setup and a defined risk strategy before entering a trade is more important than any single indicator.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    15 Must-Read Best Swing Trading Books for Trader
    2What is the Best Time Frame for Swing Trading?
    3Different Types of Trading in the Stock Market
    4Types of Traders in the Stock Market: Styles, Strategies & Pros and Cons
    5Top Indicators Used By Intraday Traders In Scalping

    Frequently Asked Questions (FAQs)

    1. What is DMI in trading?

      DMI is a technical indicator that helps in understanding the direction and strength of a trend.

    2. What are +DI and -DI?

      +DI represents upward movement, while -DI represents downward movement.

    3. What is the role of ADX in DMI?

      ADX indicates the strength of the prevailing market trend.

    4. How is DMI used in trading?

      DMI is used to assess trends and filter potential trading setups.

    5. Can DMI be used for intraday trading?

      Yes, DMI can also be used for intraday trading.

  • Interest Rate Parity: Meaning, Formula & Types Explained

    Interest Rate Parity: Meaning, Formula & Types Explained

    Global finance acts like a massive puzzle with constantly shifting pieces. Currency values move up and down daily while central banks adjust borrowing costs. Understanding how these moving parts connect is crucial for anyone entering the markets. The secret lies in realizing that global money systems naturally seek balance. When borrowing costs differ between two nations, exchange rates automatically adjust to maintain fairness. This balancing act keeps international trade stable and ensures no single market offers an unfair advantage.

    What Is Interest Rate Parity

    The interest rate parity theory explains a very important rule in the world of global finance. It connects the borrowing costs of two different countries with their currency exchange rates. For readers starting their financial journey, this concept might seem heavy at first glance. However, the core idea is quite simple to grasp.

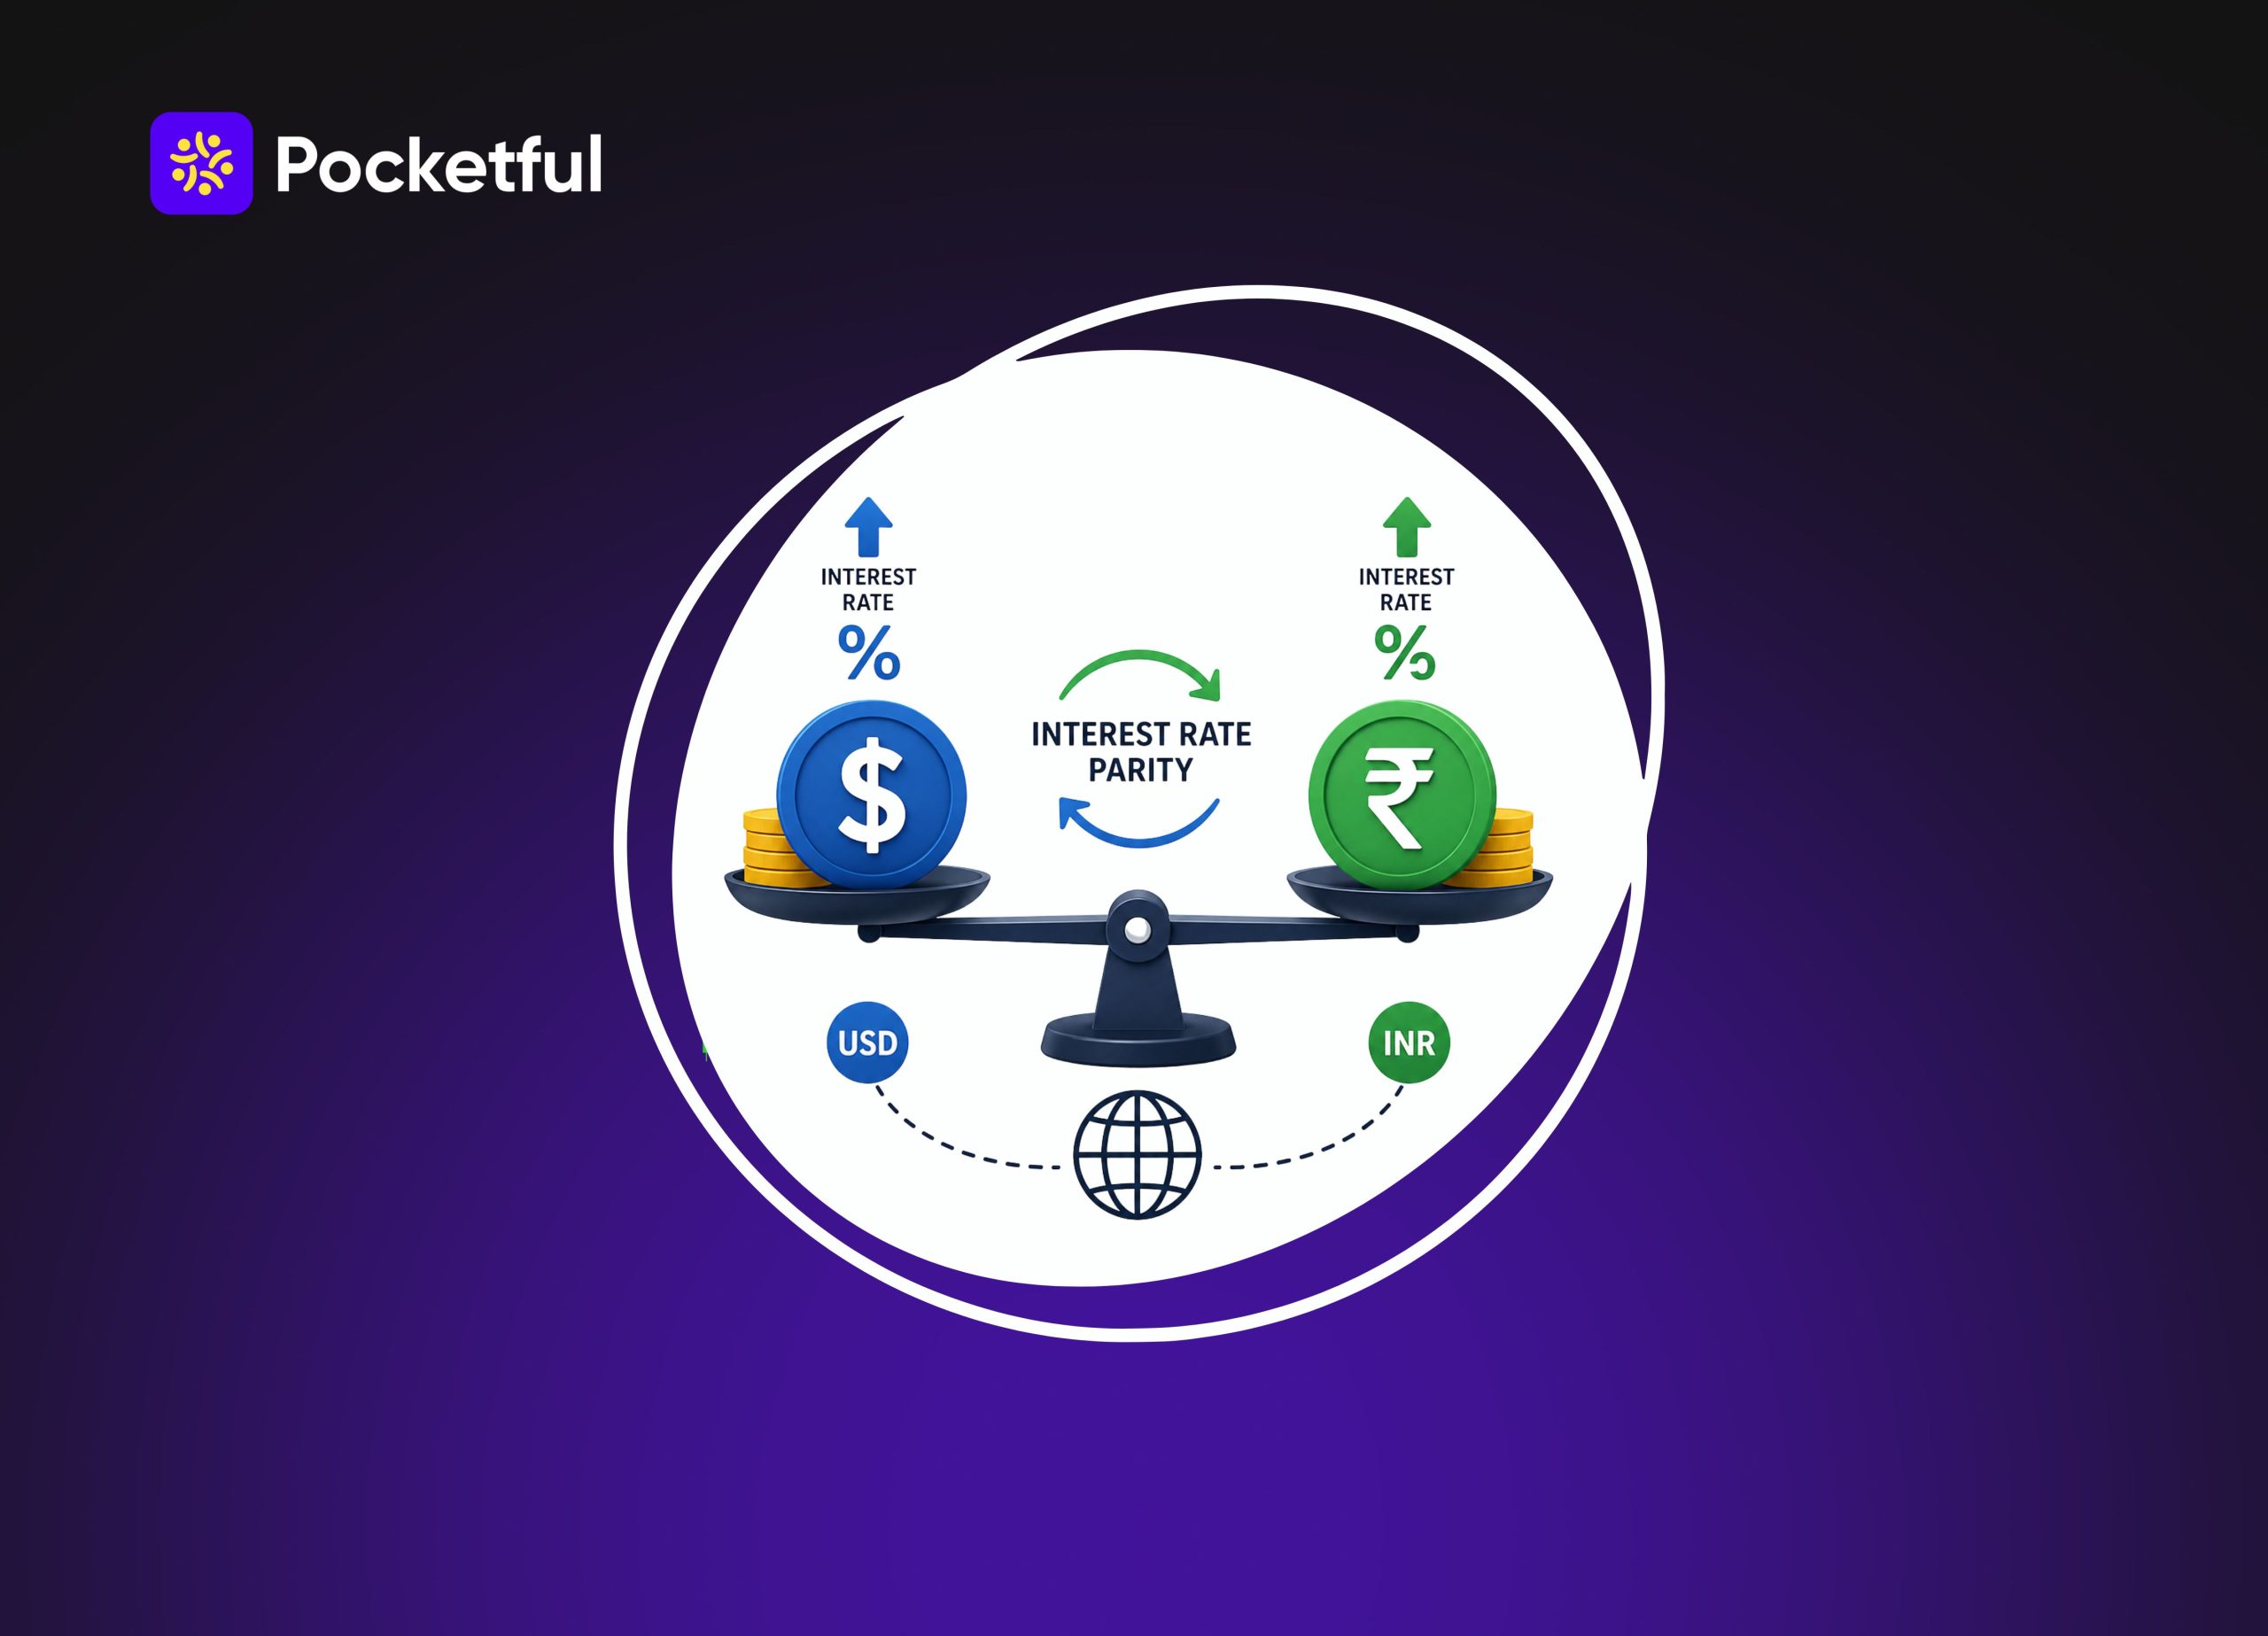
    To put it simply, interest rate parity means that the difference in interest rates between two countries equals the expected change in exchange rates between their currencies. If one country offers a much higher interest rate on its bank deposits, its currency will eventually drop in value compared to the other country. This drop balances out the extra interest earned.

    This specific rule exists to stop people from making guaranteed profits without taking any risk. In the financial world, making a risk-free profit is called arbitrage. If this natural balance did not exist, an investor could borrow money in a country with very low rates. They could then invest that same money in a country with high rates and make free money.

    To calculate how this balance works in real life, financial experts use the interest rate parity formula. This mathematical equation shows exactly how the current exchange rate and the future exchange rate must adjust. The adjustment perfectly matches the differing borrowing costs between the two nations.

    Covered Interest Rate Parity

    Investors often want to protect their money from sudden currency changes. They use covered interest rate parity to achieve this goal safely. This method relies on special financial agreements called forward contracts.

    A forward contract acts like an insurance policy for the exchange rate. It allows an investor to lock in a specific exchange rate for a future date. This completely removes the fear of currency values dropping unexpectedly.

    Here are the main points to understand about this protected investment style:

    • The word covered simply means the investor is fully protected against all exchange rate risks by using a forward contract.
    • Because the risk is covered, the interest rate parity rule ensures that the final profit remains exactly the same as investing back in the home country.
    • The difference between the current exchange rate and the locked future exchange rate perfectly balances the difference in the two countries’ interest rates.
    • This specific type of parity is very common among large international banks and institutional investors. These big players want to avoid unexpected financial losses during cross-border operations.
    • If the market fails to maintain this balance, smart traders will immediately exploit the gap for free money. Their rapid buying and selling actions quickly force the market back into its normal equilibrium.
    • Economists have found empirical evidence that this covered condition generally holds true for all freely traded currencies in the modern day.

    This covered approach makes cross-border business much safer. Companies importing goods can calculate their future costs without worrying about a sudden currency crash.

    Uncovered Interest Rate Parity

    Sometimes investors choose not to use protective forward contracts. In this scenario, understanding what is interest rate parity becomes even more critical. This specific and riskier situation is known as uncovered interest rate parity.

    In this case, the investor simply puts their money in a foreign country and hopes the currency values behave exactly as expected. There is no safety net provided. The profit margin depends entirely on market movements.

    Here are the key aspects of the uncovered version:

    • Investors take on the full currency risk. Their expected return depends entirely on their own forecast of future exchange rates.
    • The underlying theory assumes that a currency with a higher interest rate will naturally depreciate against a currency with a lower interest rate over time.
    • Since there is no protection, if the foreign currency drops in value more than expected, the investor could lose a significant amount of their original money.
    • This concept relies heavily on the free movement of capital and the perfect substitutability of domestic and foreign assets. Money must flow easily and quickly across country borders for this natural balance to occur.
    • In the real world, this uncovered balance does not always work perfectly. Panic in the market, sudden inflation, and strict government policies can cause unexpected currency shifts.

    When this uncovered theory fails, it sometimes leads to carry trades. A carry trade happens when investors borrow money in a currency with a low interest rate and invest in a high-yield currency. Platforms like Pocketful offer advanced charts that help traders track these international currency trends safely and effectively.

    Read Also: Types of Interest Rates Explained

    The Interest Rate Parity Formula

    The mathematical side of this concept is quite straightforward. Financial analysts use a specific equation to find the exact future exchange rate. This helps them understand where the currency price should naturally settle.

    The standard equation used globally is: F = S(1 + id)/(1 + if)

    To understand this equation, one must look at its individual parts carefully. The letter F stands for the forward exchange rate, which is the expected future price. The letter S stands for the spot exchange rate, which is the current price of the currency today.

    Furthermore, the symbol “id” represents the interest rate in the domestic country. The symbol “if” represents the interest rate in the foreign country.

    Let us look at a practical example involving the Indian Rupee (INR) and the US Dollar (USD). This will make the concept clearer for readers trying to understand global money flows.

    Suppose the current spot exchange rate is 83 Indian Rupees for 1 US Dollar. The domestic interest rate in India is 6 percent. The foreign interest rate in the United States is 4 percent.

    Using the equation, 

    84.59 = 83(1.06)/(1.04)

    This result means the Indian Rupee is expected to drop slightly in value compared to the Dollar. The 2 percent difference in interest rates is perfectly offset by the change in the currency price. Therefore, an investor makes the same profit whether they keep their money in Dollars or convert it to Rupees.

    Difference between covered interest rate vs uncovered interest rate parity

    Understanding the core distinction between the two types is vital for any active market participant. Both theories explain how money moves globally, but they handle financial risk very differently.

    The main difference lies in the use of forward contracts. One method uses these contracts for total protection, while the other relies entirely on market predictions.

    The table below highlights the key differences clearly.

    FeatureCovered Interest Rate ParityUncovered Interest Rate Parity
    Protection LevelUses forward contracts to completely eliminate exchange rate risk.Does not use any protective contracts. The currency risk is entirely open.
    Outcome CertaintyProvides a guaranteed, locked-in future exchange rate for the investor.Relies purely on the expected future exchange rate holding true.
    Overall RiskExtremely low risk. This makes it highly popular for large global banks.High risk due to potential unexpected and sudden currency changes.
    Real-World AccuracyGenerally holds true in modern, open financial markets without strict controls.Often fails in reality due to market panic, taxes, and high inflation.
    Arbitrage ImpactEliminates risk-free profit opportunities instantly as markets adjust.Market deviations can lead to risky carry trades by bold investors.

    Both methods help individuals and large institutions make smarter financial choices. 

    Read Also: How Interest Rates Impact Mutual Funds

    Conclusion

    The deep concepts of global finance do not have to be intimidating or overly complicated. By understanding how borrowing costs and currency values connect, anyone can gain a clearer picture of the world economy.

    These parity rules keep global markets stable and fair for all participants. They ensure that money flows logically from one nation to another without creating unfair advantages. Understanding these mechanisms reveals exactly why exchange rates constantly shift in the daily news. learning these fundamental financial theories is a wonderful step toward better financial literacy. 

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is a Fixed Income Mutual Fund?
    210+ Best Investment Plan for Monthly Income in India
    3Types of Bonds in India
    4Simple Interest vs Compound Interest?
    5Impact of Interest Rate Change on Financial Markets
    6What are Bond Valuation?

    Frequently Asked Questions (FAQs)

    1. What is the basic meaning of IRP? 

      It states that the difference in interest rates between two nations perfectly equals the expected change in their currency exchange rates.

    2. What are the benefits of this IRP? 

      It prevents unfair risk-free profits across borders. It also helps multinational businesses accurately forecast future exchange rates for smoother operations.

    3. How do investors use interest rate parity theory? 

      Investors use it to decide whether to invest locally or abroad. It helps calculate if foreign investments remain profitable after currency fluctuations.

    4. Why does the parity sometimes fail? 

      It fails due to sudden government taxes, strict capital controls, unexpected high inflation, or severe global market panic.

    5. Does it apply to everyday traders? 

      Yes. Everyday traders use it to understand broad market trends. Modern applications help them track these important macroeconomic indicators easily.

  • SEBI Rules for Authorised Person Registration

    SEBI Rules for Authorised Person Registration

    Entering the financial markets as a business partner opens doors to tremendous growth and endless possibilities. The stock market provides a brilliant pathway to build a solid career while helping investors manage their wealth effectively. To step into this exciting space, individuals must follow specific guidelines set by the market regulator. The authorities have laid down a clear path for seamless entry. Following these steps ensures a highly rewarding and completely safe professional journey.

    Who is an Authorised Registration Person for SEBI?

    An authorised person acts as a vital bridge between a registered stockbroker and a retail investor. Formerly known as a sub broker, this individual or firm provides clients with safe access to the trading platform of a stock exchange. They work strictly as dedicated agents for their affiliated stockbrokers.

    These professionals guide clients to choose the right shares and assist them in building strong investment portfolios. They operate under the constant supervision of their stockbroker. The stockbroker remains completely responsible for all their official actions and trades.

    Unlike direct brokers, these agents do not charge brokerage directly to the clients. Instead, they receive a fixed commission from the stockbroker for every transaction they help execute. This system keeps the market transparent, fair, and highly regulated for everyone involved.

    Registration Forms of Authorised Person

    The registration process requires specific forms to be filled out and submitted carefully. These documents are usually provided by the affiliated broking house. Filling these correctly prevents unnecessary delays in the final approval process.

    • Official Application Form: The main application document must be obtained from the stockbroker’s official website. This form captures all the basic details of the applicant. It needs to be duly signed and stamped by both the applicant and the broking house.
    • Form-B: This is a mandatory form required by the stock exchange for official records. The form must be filled, signed, and stamped in the exact format defined by the broking house. Any minor mistakes here can delay the entire registration process.
    • Form-C: This document acts as an official endorsement from the broker. It must be printed directly on the member’s official letterhead. It needs to bear the official registration stamp of the broking house to be considered valid.
    • Official Debit Authorization Letter: The broking house must provide a formal financial letter to the exchange. This letter allows the stock exchange to deduct the registration fees directly from the broker’s account. This makes the fee payment process smooth and removes the need for manual cheque clearances.
    • Reference Letters: The applicant must submit two distinct reference letters recommending them for the role. At least one of these letters must come directly from the applicant’s banker. This step helps the authorities verify the financial standing and character of the applicant.

    Read Also: Can an Authorised Person Trade for Himself? Rules Explained

    Eligibility of SEBI Rules Authorised Person

    Meeting the eligibility criteria is the first major step for anyone looking to enter this business. The rules exist to ensure that only capable and trustworthy individuals handle investor money. The market regulator wants to protect the common investor from fraud and mismanagement.

    The criteria cover everything from basic education to the legal structure of the business. Both individuals and corporate companies can apply for this role. They simply need to meet the specific conditions outlined below.

    Criteria CategorySpecific Eligibility Rules
    CitizenshipThe applicant must be a resident and a legal citizen of India.
    Age LimitThe individual must be at least 18 years old, though some brokers might require applicants to be above 21 years of age.
    EducationThe applicant needs to have passed at least the 10th standard or an equivalent high school examination.
    CertificationThe applicant must hold the required NISM certifications for the specific market segment to prove their practical knowledge.
    InfrastructureThe individual must possess adequate office space, manpower, and computer equipment to handle daily trading activities smoothly.
    Entity StructureCompanies must be registered under the Companies Act, while partnerships need registration under the Partnership Act of 1932 or LLP Act of 2008.

    Additional Declaration of Authorised Person

    Along with the main forms, the applicant must provide a few specific legal declarations. These documents confirm the ethical background and clear intentions of the applicant. It is a formal way to promise the regulator that business will be conducted honestly.

    • Direct Dealing Undertaking: The applicant must declare in a prescribed format that they will deal directly with investors. They must confirm that they will not work through any other unapproved or hidden person. This ensures total transparency in daily business operations.
    • Clean Record Declaration: A formal written statement is required to confirm a completely clean past. This builds trust between the regulator and the applicant.
    • Broker Agreement Copy: A certified true copy of the formal agreement between the broking firm and the applicant is absolutely needed. This important document must be printed on a Rs. 100 stamp paper. It must be clearly signed by witnesses to be legally binding.
    • Profit Sharing Details: If the applicant operates as a partnership firm, they must declare the exact profit sharing ratio among all the partners. This document must include the total number of partners and their specific asset details. It prevents future financial disputes among business owners.

    Other Declaration of Authorised Person

    Depending on the specific type of business entity, some extra declarations might be needed during the process. These ensure that the business structure complies fully with corporate laws. It helps the regulator understand who is actually running the business behind the scenes.

    • Corporate Entities: If the applicant is a registered corporation, they have to follow strict company laws. They must submit a certified true copy of the ROC Form 32. This proves their legal standing and active status in the corporate registry.
    • Board Resolutions: Corporate bodies need to provide an official board resolution document. This document must clearly authorize specific directors or managers to conduct trading activities on behalf of the company. It ensures that the company officially supports the trading venture.
    • Partnership Firms: Partnerships require different proofs of existence to operate legally. A duly signed and notarized copy of the partnership deed is highly required. The memorandum of articles must also be submitted alongside it for full legal clarity.
    • Broker Database Certificate: If the applicant is already a member of a regional stock exchange, they have to show proper proof. They must provide a broker database certificate for verification. This needs to be certified directly by the respective regional exchange.
    • Cancellation Undertakings: Some individuals might already be registered as a remisier with the same exchange. In such cases, they cannot hold two conflicting positions at once. They must submit an undertaking to cancel their previous premiership during the new registration process.

    Documents Required for Authorised Registered Person

    The following papers must be arranged properly before applying.

    • Identity and Age Proof: Certified photocopies of a valid ID card are strictly required for identity checks. This ID card must clearly show the applicant’s exact date of birth. The regulator uses this to verify that the applicant meets the exact age criteria.
    • PAN Card: A clear copy of the Permanent Account Number card is completely mandatory for everyone. The government uses this specifically for tax tracking and financial identity verification. Without a PAN card, no financial business can be started in India.
    • Educational Certificates: A passing certificate for the highest educational qualification must be attached to the application. Usually, a High School Certificate or 10th standard pass certificate is the minimum requirement. This proves the applicant has the basic educational knowledge required for the role.
    • Address Proofs: Valid documents showing both the residential address and the official office address must be submitted. This helps the broker and the exchange know exactly where the business operates. It is vital for sending official letters and legal notices.
    • Market Experience Certificate: Sometimes an applicant does not meet the minimum educational criteria set by the rules. In such scenarios, they must submit a hard copy of a Market Experience Certificate. This certificate must come directly from a registered financial firm.

    Read Also: Authorised Person Vs Franchise: What’s the Difference?

    Conclusion

    Entering the financial sector as a certified professional opens the door to immense growth and learning. The rules and guidelines created by the regulator exist purely to build a safe, transparent, and highly trusted market environment. By completing the correct paperwork and understanding the compliance requirements, individuals can build a highly respectable career.It brings financial independence to the professional and deep safety to the retail investor. Ready to build your business as an Authorised Person? Partner with Pocketful for competitive profit sharing, advanced trading tools, and dedicated support to help you manage your operations smoothly. 

    Frequently Asked Questions (FAQs)

    1. What is the meaning of an Authorised Person? 

      It is a registered individual appointed by a stockbroker. They provide clients safe access to the trading platform, acting as a trusted bridge.

    2. What are the main benefits of this registration? 

      Registered individuals gain access to advanced trading platforms. They earn steady commissions and build a respected business with very low initial investment.

    3. How to use the registration certificate for an Authorised Person? 

      The certificate is used to officially onboard new clients. It allows the person to legally operate a financial services office under a stockbroker.

    4. Is a large amount of capital required to become an Authorised Person? 

      No, entering this business requires very low capital. Individuals only need basic office infrastructure and a small one time registration fee.

    5. Can one person work with multiple brokers? 

      No, the rules state that an individual can only affiliate with one stockbroker on a single stock exchange at any given time

  • Can an Authorised Person Trade for Himself? Rules Explained

    Can an Authorised Person Trade for Himself? Rules Explained

    Individuals acting as ‘Authorised Persons’ in the stock market often have a common question: can an authorised person trade for themselves? Can they buy and sell shares for their own account while also managing trades for clients? To answer this, it is essential to understand the role of an Authorised Person and the distinction between personal trading and client interests.

    What Is an Authorised Person in the Stock Market? 

    An Authorised Person (AP) is an individual or entity appointed by a stockbroker to act as their agent. The AP assists clients in accessing trading services and navigating processes associated with the broker. An AP is not a trading member of the stock exchange in their own right.

    For example, if an AP assists clients with trading on the broker’s platform, they operate in accordance with the rules and agreement established by the broker. Their role is that of an authorized intermediary between the client and the broker.

    Can an Authorised Person Trade For Himself? 

    Can an Authorized Person (AP) trade on their own behalf? Understanding the answer requires making a crucial distinction. According to the NSE, proprietary trading refers to trading conducted by a member on their own behalf. An AP’s role is different; they act as an agent for the stockbroker. Therefore, merely holding an AP registration does not grant them the same proprietary trading rights as a Trading Member.

    This does not mean that an AP is automatically prohibited from maintaining their own investments. If an AP wishes to trade in shares or other securities for themselves, they must ensure that their personal trading aligns with their role as an AP, the broker agreement, and applicable compliance requirements. Under the NSE’s current framework, a written agreement between the AP and the Trading Member is mandatory, outlining conditions such as specific activities and responsibilities.

    What points should be kept in mind regarding personal trading?

    SituationWhat should be kept in mind?
    Investing in yourselfRefer to the broker’s applicable policy and the AP agreement.
    Handling orders for the clientThis is a client-related activity.
    Trading for oneself in the client’s account.One should not do this.
    Receiving funds or securities from the client in one’s own name.It is not permitted under NSE AP conditions.
    Taking personal advantage of a client’s information.It could become an issue of conflict of interest.

    Example: Suppose an AP wants to purchase a stock for their personal portfolio. In this case, it is crucial to first ensure that the transaction is executed within their own capacity and in accordance with the broker’s applicable rules. However, if the same AP uses a client’s account for their own trade, the matter escalates from a personal investment to a compliance issue.

    Why Is Personal Trading Different for an Authorised Person? 

    Additional compliance requirements apply to an Authorized Person’s (AP) personal trading because their professional role is directly linked to market activity.

    • Keep Roles and Personal Interests Separate: An AP should separate their investment decisions from their professional responsibilities to avoid confusing the two roles.
    • Check the Broker’s Policy: Every AP should review their broker’s agreement and internal compliance rules. Brokers may establish specific conditions regarding personal trading.
    • Keep Personal Trades Separate from Client Orders: Transactions executed by the AP for themselves must be kept distinct from client trading activity. This minimizes confusion during order handling.
    • Do Not Use Sensitive Information: Non-public information such as client orders, holdings, or trading plans should not form the basis of an AP’s personal trades.
    • Do Not Use Client Accounts: Using a client’s account, login details, or funds for personal trading is improper. The NSE classifies such activities as irregularities associated with APs.
    • Seek Clarification from Compliance First: If there is any doubt regarding a rule, it is safer to obtain confirmation from the broker’s compliance team before executing a trade, rather than raising the issue afterward.

    Read Also: Authorised Person Vs Franchise: What’s the Difference?

    Authorised Person Own Trading vs Client Trading 

    The distinction between an AP’s own trading and client trading is primarily determined by whose behalf the trade is executed and who bears the responsibility for it.

    BaseAuthorized Person’s Own TradingClient Trading
    Purpose For the AP’s own investment or tradingFor the client’s investment or trading
    Funds UsedAP’s own fundsClient’s funds
    Trading DecisionBased on the AP’s own decisionBased on the client’s instructions
    Trading AccountAP’s appropriate personal trading arrangementClient’s registered trading account
    Profit or LossBorne by the APBorne by the client
    AP’s RoleManages his own investment activityAssists the client under the broker’s framework
    Client CredentialsNot used for personal tradingUsed only for authorised client activity
    Client InformationNot used for personal advantageHandled according to confidentiality requirements
    Funds HandlingAP business funds should remain separate from personal fundsClient funds are handled through the prescribed broker framework
    Compliance FocusBroker policy, AP agreement and applicable rulesClient protection and proper order handling

    Can an AP Use a Client’s Trading Account for His Own Trade? 

    No. An Authorised Person cannot use a client’s trading account for their own personal trades. According to NSE inspection circulars, irregularities associated with an Authorised Person include trading using the client’s login details, trading in the client’s account without permission, and obtaining trading authority from the client to trade on their behalf.

    The rule simply means

    A client’s trading account is intended solely for that client’s transactions. An AP must not use the client’s account, login details, or trading authority for their own personal trading.

    SituationSituation in accordance with the rules
    The AP should trade using a personal trading arrangement suitable for themselves.In accordance with the broker and applicable compliance requirements.
    Trade for yourself using the client’s account.Permission is not granted.
    Trade using the client’s login ID and password.Permission is not granted.
    Obtain trading authority from the client and place orders on their behalf.Flagged by the NSE as an irregularity.
    Open a position in the client account for your own benefit.Permission is not granted.

    What Happens If an AP’s Own Trade Conflicts With a Client’s Trade? 

    When a conflict arises between an AP’s own trades and the client’s interests, personal interest cannot take precedence over the client’s interest. In accordance with SEBI’s code of conduct framework, such conflicts must be identified, managed, and—where necessary—disclosed.

    1. Prioritizing Client Interest

    An AP must refrain from seeking personal gain in such situations, especially when in possession of confidential information regarding the client.

    2. Handling Conflicts

    In such scenarios, it is essential to adhere to the broker’s compliance processes. If necessary, personal trades may need to be restricted or avoided to ensure the client’s interests are not compromised.

    3. Key Rule

    An AP cannot engage in personal trading in a manner that creates a conflict between their professional obligations to the client and their own personal interests.

    Authorised Person vs Trading Member: Are They Allowed to Trade the Same Way? 

    The market roles of an AP and a Trading Member differ; therefore, their trading rights cannot be considered identical.

    Basis Authorised PersonTrading Member
    Status Stock broker’s agentMember of the stock exchange
    Market AccessIt provides access to the exchange trading platform through a broker.Trades directly under exchange membership.
    Own-Account TradingMember-level proprietary trading rights are not automatically granted based on AP status.Can engage in own-account trading under the applicable membership framework.
    Client OrdersAssists clients with trading services within the broker’s framework.Can execute client orders.
    AgreementThere is a written agreement between the broker and the AP.It operates in accordance with exchange membership and regulatory requirements.
    Funds and SecuritiesYou cannot receive or pay money or securities related to AP business in your own name or account.It handles matters in accordance with the applicable exchange and regulatory framework.
    ResponsibilityThe Trading Member is responsible for the acts and omissions of the AP.A member is directly accountable for their regulatory and exchange responsibilities.

    How Should an AP Keep Personal and Client Trading Separate? 

    Keeping personal and client trading separate minimizes the scope for confusion regarding order handling and compliance.

    • Maintain Your Own Trading Arrangement: An AP should use their own appropriate trading arrangement for personal investments or trading, rather than using a client’s account.
    • Do Not Use Client Credentials: Client login details, account access, or trading authority must not be used for the AP’s own trading activities.
    • Maintain Proper Records: Records of personal transactions should be kept clear and distinct so that, if necessary, it is easy to determine the capacity in which the trade was executed.
    • Adhere to the Broker’s Compliance Policy: An AP should first understand their broker’s internal policies and applicable requirements regarding personal trading.

    Read Also: How to Become a Sub Broker in India

    Common Mistakes APs Should Avoid 

    For an AP, even a minor error can lead to a compliance issue; therefore, it is essential to avoid certain common mistakes associated with personal trading.

    • Ignoring Broker Conditions: An AP should not engage in any personal trading activity without fully understanding the trading and compliance conditions outlined in their agreement.
    • Mixing Roles: Handling professional responsibilities and personal financial decisions in the same manner can lead to confusion.
    • Conducting Transactions Without Records: It is important to properly maintain necessary records and confirmations for personal trades to ensure a clear transaction trail.
    • Checking Compliance After the Fact: In ambiguous situations, it is better to seek clarification from the broker or compliance team beforehand rather than dealing with issues that may arise after the trade has been executed.

    Conclusion

    For an Authorised Person, the most important aspect when engaging in personal trading is to adhere to the broker’s agreement and applicable regulations. Keeping personal trading and professional responsibilities separate helps the AP avoid unnecessary compliance issues and conflicts.

    Frequently Asked Questions (FAQs)

    1. Can an Authorised Person (AP) trade for themselves?

      This depends on the broker’s policy, the AP agreement, and applicable regulations.

    2. Can an AP trade for themselves using a client’s account?

      No, a client’s account cannot be used for personal trading.

    3. Are the AP and the Trading Member the same?

      No, an AP acts as an agent for the broker, whereas a Trading Member is a member of the exchange.

    4. Can an AP use a client’s login details?

      No, unauthorized use of client credentials is not permitted.

    5. What should an AP do before engaging in personal trading?

      They should review the broker’s compliance policy and the agreement.

  • How to Calculate Stock Volatility in Excel?

    How to Calculate Stock Volatility in Excel?

    When evaluating a stock, looking at returns alone leaves out a big piece of the puzzle. It is just as important to track how sharply and how often the price swings up and down. That price movement is what investors call stock volatility. The good news is that calculating it does not take high-priced financial software. With basic access to Microsoft Excel, anyone can figure out these numbers in a few quick steps. The guide below breaks down the full process using simple terms and practical examples. 

    What Is Stock Volatility? 

    Not all stocks experience the same price behavior. Some stocks witness significant fluctuations within a single day or over a few days, while others remain relatively stable. This degree of fluctuation in a stock’s price is known as “stock volatility.” Simply put, the greater the price movement, the higher the volatility is considered to be. However, this does not indicate whether a stock is good or bad; it merely reflects the speed or intensity with which its price changes.

    Example: 

    Stock30-day high priceMinimum price for 30 daysVolatility
    Stock A₹505₹495Less
    Stock B₹560₹440More

    Let’s understand this with an example: If one stock remained within the ₹495 – ₹505 range throughout the month, while another fluctuated between ₹440 and ₹560, the second stock would be considered to have higher volatility. In other words, since its price underwent greater variation, it can be considered to carry relatively higher risk.

    Why Do Investors and Traders Measure Stock Volatility? 

    Volatility provides an indication of how rapidly a stock’s price can change. This information helps in making better decisions during investing and trading.

    • To understand risk: Every stock carries a different level of risk. By looking at volatility, one can gauge the likelihood of significant price fluctuations.
    • For better comparison of stocks: Even if two stocks are delivering good returns, their price movements may differ. Volatility helps in understanding this distinction.
    • For investment planning: Many investors use volatility metrics to determine the appropriate amount of capital to allocate to a specific stock.
    • To select stocks based on investment style: Investors who prefer lower risk often look for stocks with relatively low volatility. Conversely, others seek opportunities in stocks that exhibit significant price fluctuations.
    • For better preparation in trading: Price movement is crucial in swing trading and options trading. Understanding volatility aids in formulating better trading strategies.

    Read Also: What Is Black-Scholes Model

    What You’ll Need Before Starting in Excel 

    Before you begin calculating stock volatility, it is essential to have the correct data and certain necessary elements ready. If the data is accurate from the start, the results obtained in Excel will also be more reliable.

    RequirementWhy Is It Important?
    Historical Stock Price DataPast price data is required to calculate stock volatility accurately.
    Adjusted Closing PriceIt accounts for stock splits, bonus issues, and dividend payouts, giving you a much truer picture of returns than standard closing prices.
    Microsoft ExcelExcel provides built-in functions that make volatility calculations simple and efficient.
    At Least 30 Trading Days of DataA larger dataset generally provides more reliable results. Using 30 to 252 trading days is a common practice.
    Data Arranged in Chronological OrderPrices should be organized from the oldest date to the newest so that daily returns are calculated correctly.
    No Blank or Missing ValuesMissing or incorrect data can lead to calculation errors and inaccurate volatility results.

    Workflow Before You Start Stock Volatility Calculation

    Before applying a formula in Excel, it is helpful to understand the order in which the entire calculation takes place.

    StepWhat You’ll DoPurpose
    Step 1Import historical stock price data into ExcelPrepare the data required for the calculation.
    Step 2Calculate daily returns for each trading dayMeasure how much the stock price changes from one day to the next.
    Step 3Calculate the standard deviation of daily returnsDetermine the stock’s daily volatility.
    Step 4Annualize the daily volatilityConvert daily volatility into an annual percentage using the standard market method.
    Step 5Analyze the final volatility valueUnderstand whether the stock has relatively low, moderate, or high price fluctuations based on historical data.

    Step 1: Prepare historical price data in Excel.

    First, open the historical stock prices for your target company in Excel. If the file is in CSV format, just import it into your sheet no need to create a new tab. Next, widen the price column so the numbers are easy to read. This makes adding formulas much cleaner and keeps everything clear at a glance. 

    Example

    DateAdjusted Close Price
    01-Jan₹100
    02-Jan₹102
    03-Jan₹101
    04-Jan₹104

    Step 2: Create a new column for Daily Return

    Add a new column right next to the ‘Price’ column and call it ‘Daily Return’. You will calculate the daily returns inside this column. Type the formula into the first row and press Enter. Make sure the result looks correct. If the number appears fine, click the bottom corner of that cell and drag it all the way down to fill the rest of the rows automatically.

    =LN(B3/B2)

    Example

    DateAdjusted Close PriceDaily Return
    01-Jan₹100
    02-Jan₹1020.0198
    03-Jan₹101-0.0098
    04-Jan₹1040.0293

    Note: A return value will not be calculated for the first row because the price for the preceding day is unavailable. This is perfectly normal.

    Step 3: Calculate the volatility of the daily returns

    Once you have daily returns for the whole column, pick an empty cell below them to find the volatility. Just highlight all those return values and enter the formula. 

    =STDEV.S(C3:C31)

    After applying the formula, you will get a value in decimal form. This represents the daily volatility for your selected period.

    Step 4: Calculate Annual Volatility

    Now, convert the daily volatility into annual volatility to make the result easier to understand and compare with other stocks.

    To do this, enter this formula in another cell.

    =STDEV.S(C3:C31)*SQRT(252)

    If you want to view the result as a percentage, change that cell to the percentage format. This will make the value easier to read.

    Daily VolatilityAnnual Volatility
    0.012019.05%

    Step 5: Check and Compare the Results

    You now have the final volatility value ready. Instead of stopping at just one stock, apply this same method to other stocks as well. Once you have the volatility data for all the stocks, it will be easier to understand which stocks experience greater price fluctuations and which ones are more stable.

    Common Mistakes in Calculating Stock Volatility

    It’s easy to make small mistakes when calculating volatility in Excel for the first time. Often, your formula is right, but bad data or wrong formatting messes up the answer. Double-checking these few things early saves you from fixing errors later.

    • Failing to check the data: Take a quick look at the spreadsheet before starting the calculation. If a row is blank or a price for a specific date is missing, subsequent results could be affected accordingly.
    • Always using an old spreadsheet: Some people add new data to an existing Excel sheet and immediately run the formula. It is best to verify whether the formula actually extends to include the new rows.
    • Accepting the result without questioning it: If a stock’s volatility appears unusually high or low, review the calculation instead of immediately accepting the figure as correct. Often, the issue lies with incorrect data rather than the formula itself.
    • Treating all companies the same way: Price movements vary by industry. Therefore, directly comparing the volatility of a banking stock with that of a small-cap or IT stock does not provide an accurate picture.
    • Treating volatility as the final deciding factor: Volatility merely indicates the extent of price fluctuations. When making investment decisions, it is advisable to also consider the company’s financial performance, business operations, and other relevant information.

    Conclusion

    The biggest advantage of learning how to calculate stock volatility is that you can understand a stock not just by its returns, but also by its price fluctuations. Excel makes this task easier. Just keep in mind that when making any investment decision, you should consider the company’s fundamentals and your own investment goals alongside volatility.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What is Future Trading and How Does It Work?
    2Types of Futures and Futures Traders
    3Difference Between Options and Futures
    4Synthetic Futures – Definition, Risk, Advantages, Example
    5Difference Between Forward and Future Contracts Explained
    6Cost of Carry in Futures Contract
    7Silver Futures Trading – Meaning, Benefits and Risks

    Frequently Asked Questions (FAQs)

    1. How to calculate stock volatility in Excel?

      Stock volatility can be calculated using historical price data, daily returns, and the STDEV.S formula.

    2. Which Excel formula is used for stock volatility?

      The STDEV.S formula is used for volatility, and the LN formula is used for daily returns.

    3. Can beginners calculate stock volatility in Excel?

      Yes, anyone can get started using basic Excel formulas.

    4. How many days of data are required for stock volatility calculation?

      Data from at least 30 trading days should be used for better results.

    5. Is high stock volatility always risky?

      No, it merely indicates significant price movement, not the total investment risk.

  • What are Passive ETFs?

    What are Passive ETFs?

    Try asking ten investors what passive investing means, and you will get ten half-formed answers. Someone will say something about index funds. Someone else will just say that they are the boring way of investing. However, to your surprise, that second person is not completely wrong. Passive ETFs are boring. 

    If you have spent years chasing multibaggers or trying to time every Nifty swing, this might feel very simple for you. No fund manager making bold calls with your money. It just tracks an index and lets the market do whatever it is going to do anyway. But that simplicity is why passive ETFs have become one of the fastest-growing corners of the Indian mutual fund and ETF world.

    So let us get into it in detail: what these are, how they work, and why traders are now parking money here alongside their active investments.

    What is a Passive ETFs?

    A Passive ETF, or Exchange Traded Fund, is a basket of securities designed to mirror the performance of a specific index, for example, Nifty 50, Sensex, etc.

    It replicates the index that it is tracking with the same stocks, same weightage, more or less.

    Example:

    ABC stock makes up 10% of the Nifty 50; a Nifty 50 ETF will hold roughly 10% of its portfolio in Reliance too. 

    ETFs trade on stock exchanges like the NSE and BSE throughout market hours. 

    You need a demat and trading account to buy them, just like you would for any stock. Prices move in real time, and you can enter or exit whenever the market is open.

    Features of Passive ETFs

    • They track the index: Passive ETFs do not rely on a fund manager’s skills. Whatever is in the index, in whatever proportion, is what you own. 
    • Affordable: A Sensex or NIFTY 50 ETF in India have an expense ratio somewhere between 0.05% and 0.20%. Compare that to 1-2% for a lot of actively managed equity funds, and over 15-20 years that gap turns into a big amount. That is not a small difference
    • They are liquid: Since they trade all day on the exchange, you are not stuck waiting for a closing NAV like with a regular mutual fund.
    • Diversification: One ETF unit can also give you instant diversification. Buy a Nifty 50 ETF, and you will suddenly get exposure to 50 of India’s biggest companies, including banking, IT, FMCG, pharma, energy, etc. If you buy individual stocks of the Nifty 50, you’d need a lot more capital and a lot more patience.
    • Low Portfolio Turnover Ratio: Turnover stays low too, since nobody’s constantly buying and selling based on market calls. Less churn generally means better tax efficiency compared to actively managed funds that trade frequently.

    Types of Passive ETFs

    • Broad market ETFs: Nifty 50, Sensex, Nifty Next 50, Nifty 100, Nifty Midcap 150
    • Sectoral and thematic ETFs: Nifty Bank, Nifty IT, Nifty Pharma, Nifty PSU Bank, and similar sector-focused options
    • Smart beta / factor-based ETFs: Nifty Low Volatility, Nifty Alpha 50, Nifty Quality 30, which tilt toward specific investment factors while still being rules-based rather than actively managed
    • Debt ETFs: Bharat Bond ETFs are a good example, tracking a basket of government-backed corporate bonds
    • Gold ETFs: track domestic gold prices, giving exposure without the hassle of storing physical gold
    • International ETFs: These ETFs track global indices like the Nasdaq 100 or S&P 500, letting Indian investors get exposure to US markets without opening an overseas trading account

    That range means passive investing today isn’t just about equity anymore. You can build a diversified, low-cost portfolio using ETFs alone if you wanted to.

    Read Also: What is Equity ETFs?

    Benefits of Investing in Passive ETFs 

    • Cost efficiency: Lower expense ratios mean more of your money stays invested and compounds over time, instead of getting eaten up by management fees.
    • Simplicity: You do not need to track quarterly results, analyze balance sheets, or worry about whether a fund manager’s strategy is working. You are simply betting on the broader market’s long-term growth trajectory, which in India’s case has historically been strong enough.
    • Reduced manager risk: With active funds, your returns depend heavily on the fund manager’s decisions. If there is a change in the manager, then the performance can shift too. Passive ETFs remove that dependency entirely 
    • Easy entry point for beginners: For someone who is new to investing and unsure where to start, a broad market ETF is often recommended as a low-risk, low-effort way to get market exposure without needing deep knowledge of individual stocks.
    • Flexibility to trade like a stock: ETFs are traded throughout the day, you get more control over your entry and exit price compared to mutual funds, where you are stuck with the closing NAV. 

    Taxation of Passive ETFs

    Passive ETFs are generally taxed based on the type of ETF and how long you hold the investment. For equity-oriented ETFs, gains on selling units are treated as capital gains.

    • Short-Term Capital Gains (STCG): equity ETF sold within 12 months of purchase, the gain is generally taxed at 20%, subject to applicable rules.
    • Long-Term Capital Gains (LTCG): equity ETF holds for more than 12 months, long-term gains are directly taxed at 12.5%. LTCG under Section 112A is exempt up to ₹1.25 lakh in a financial year, subject to applicable conditions.
    • Dividends: Any dividend or other distribution received from an ETF is generally taxable in the hands of the investor according to the applicable tax rules.
    • Debt ETFs: For debt-oriented ETFs purchased on or after April 1, 2023, capital gains are generally treated as short-term capital gains (STCG), regardless of how long you hold the units. The gains are added to your taxable income and taxed according to your applicable income tax slab rate. Indexation benefits are not available.
    • Other ETFs: The taxation of gold, silver or international ETFs can differ from equity ETFs, so investors should check the applicable tax treatment before investing.

    Note: Tax rules can change over time, so investors should check the latest applicable rates before investing. 

    Active ETFs vs. Passive ETFs – Table of Differences 

    ParameterActive ETFs/FundsPassive ETFs
    ObjectiveAims to beat the benchmark indexAims to match the benchmark index
    Management styleFund manager actively picks and adjusts stocksSimply replicates the index composition
    Expense ratioRanges from 1% to 2%Ranges from 0.05% to 0.20%
    Portfolio turnoverHigh, frequent buying/selling based on market viewsLow, changes only when the index itself changes
    TransparencyHoldings can shift often, less predictableHoldings mirror a public index, always known
    Risk of underperformanceCan underperform benchmark after feesDesigned to track benchmark. Might create a small tracking error*
    TradingBought/redeemed at end-of-day NAV (if mutual fund)Traded on exchange in real time, like a stock

    (Tracking error is the gap between the ETF’s return and the index’s return over the same period. A lower tracking error means the ETF is doing its job well. You will usually find this figure on the fund house’s factsheet.)

    Things to Keep in Mind Before Investing in Passive ETFs

    • Demat & Trading Account: An investor needs a demat and trading account to buy and sell ETFs. If you do not already have one, opening an account with a broker is the first step.
    • Lower Liquidity Sometimes: Liquidity can be an issue with some lesser-known or niche ETFs. Not every ETF has strong daily trading volumes, and low liquidity can sometimes lead to a gap between the ETF’s market price and its actual NAV, which is known as the price deviation. Stick to ETFs with decent trading volumes and a track record.
    • Volatility during Market Swings: Passive ETFs also will not protect you during market downturns. If the Nifty falls 15%, your Nifty ETF falls roughly the same amount too. There is no fund manager stepping in to reduce equity exposure. That is the trade-off for lower costs.
    • Not much suitable for Small Cap category: While passive investing works well for broad, efficient markets like large-cap indices, it may not be the most effective approach for less efficient segments like small caps, where skilled active management can sometimes genuinely add value.

    Read Also: What are International ETFs?

    Conclusion 

    Passive ETFs have been a great investment option for most Indian investors’ portfolios by now, and it is easy to comprehend the reason for the same once you understand them. You get benefits like low cost, transparency, simple to grasp, and broad exposure, without needing to become a full-time stock analyst.

    But they work best as one piece of a bigger plan, not a complete answer on their own. Whether you are just getting started or trying to balance an actively managed portfolio, figuring out where passive ETFs fit into your goals is what matters here. Once that is clear, opening a trading account and getting started takes hardly a few minutes.

    S.NO.Check Out These Interesting Posts You Might Enjoy!
    1What Is iNAV in ETFs?
    2What is Dividend ETF?
    3What are Bond ETFs?
    4What is a Smart Beta ETF?
    5What is Nifty BeES ETF?

    Frequently Asked Questions (FAQs)

    1. Are passive ETFs safe to invest in?

      Somewhat. There is no capital protection here because if the index falls, your ETF falls too.

    2. What is the minimum amount needed to invest in a passive ETF?

      Just the price of one unit, which can be as low as a few hundred rupees depending on the ETF. Usually, no big capital is needed to get started.

    3. Do I need a demat account to buy passive ETFs? 

      Yes. Since ETFs trade on the exchange just like stocks, a demat and trading account is a must.

    4. Which is better: index funds or ETFs? 

      Depends on what your goal is. Index funds are simpler if you want to invest via SIP without opening a demat account. ETFs give you more control over pricing since they trade throughout the day.

    5. Can passive ETFs give negative returns? 

      Absolutely, yes. If the underlying index drops, so does your ETF. No fund manager is stepping in to protect you from the fall. 

  • What is Equity ETFs?

    What is Equity ETFs?

    Whenever you think about investing in the capital market, the first thing that comes to your mind is that you need to purchase individual stocks, and this will increase the concentration risk in your portfolio. But there is an option through which you can invest in a whole basket of stocks with a single investment, which is known as “Equity ETFs”.

    Now, we will give you an overview of what Equity ETFs are along with the best Equity ETFs in India. 

    What are Equity ETFs?

    Equity ETFs, or Exchange Traded Funds, are investment tools that primarily invest money in a basket of equity or stocks. They are traded on an exchange like any other share, and investors can purchase them in units. By investing in equity ETFs, an investor gets exposure to multiple companies through a single investment. To invest in ETFs, it is necessary to have a demat and trading account with a broker.

    Key Features of Equity ETFs

    The key features of Equity ETFs are as follows:

    • Passive Funds: ETFs are passive investment options as the fund manager does not actively pick the stocks; instead, they invest in a basket of stocks tracking a particular index.
    • Real-Time Monitoring: As ETFs are traded on an exchange, their price can be tracked in real time during the trading hours.
    • Lower Cost: ETFs generally have a lower expense ratio when compared to other actively managed funds.
    • Liquidity: Equity ETFs can be bought and sold on an exchange, hence providing liquidity to the investors so that they can buy and sell it anytime.
    • Diversified Exposure: Equity ETFs provide exposure to a basket of stocks through a single investment, helping investors diversify across multiple companies or sectors.

      Types of Equity ETFs

      Equity ETFs can be classified based on the stocks, sectors, themes, or markets they track. Here are the common types:

      Types of Equity ETFsWhat Does It Means
      Market Index ETFsIndex ETFs track a market index like the Nifty 50 or Sensex, giving investors options to a wide range of stocks. These etfs are generally replicas of Index.
      Sector ETFsSectoral ETFs concentrate on a specific sector, such as banking, IT, pharma, or energy. This allows investors to focus on a particular area of the market which they have conviction to rise. 
      Thematic ETFsThis can help investors to focus on a specific  theme. Such ETFs focus on a certain trend in their investments, which may include manufacturing, infrastructure, consumption, or technology.
      Dividend ETFsSuch ETFs tend to add companies with a history of dividend payments, making them attractive for investors who want to make wealth with consistent profit sharing with less risk.
      International ETFsInternational ETFs allow investors to participate in foreign stock, indices or markets from their own country.

      How Do Equity ETFs Work?

      The working of Equity ETFs is very similar to purchasing a fruit basket instead of purchasing a single fruit. The fund manager identifies the index that aligns with the investment objective and evaluates the weightage of the stocks of that index. 

      Once they identify the weightage, they invest all investors’ money in stocks of that particular index. Along with this, the fund manager rebalances the portfolio regularly to align with the allocation of weightage of stocks in the portfolio. However, this can lead to tracking error in the returns of the fund. 

      Read Also: What are International ETFs?

      Benefits of Investing in Equity ETFs

      The key benefits of investing in equity ETFs are as follows: 

      • Diversification: The key advantage of investing in equity ETFs is diversification. One gets exposure to many stocks through a single investment. An investment in the Nifty 50 ETF allows an investor to take exposure in the top 50 companies of Nifty.
      • Economical: As ETFs are a passive investment option, they generally have a lower expense ratio. This can keep the investment costs relatively lower.
      • Transparency: By investing in ETFs, the investor gets to know exactly where their money is invested. Allowing them to adopt a transparent investment approach. 
      • Liquidity: Equity ETFs are traded on stock exchanges like shares, allowing investors to buy and sell units during market hours at prevailing market prices.

        Risk of Investing in Equity ETFs

        The risk of investing in equity ETFs is as follows:

        • Market Risk: This is one of the key risks while investing in equity ETFs. Therefore, during any market downturn, the value of your investment may fall.
        • Tracking Error: An ETF reflects the performance of an underlying index. But sometimes their returns do not exactly replicate the return of the index due to various transaction charges, cash holdings, portfolio rebalancing, etc.
        • No Guaranteed Return: Investment in an ETF does not guarantee a return and can be volatile during market movements. Hence, investors cannot consider it as a guaranteed return investment option.
        • Sector-Specific Risk: Sectoral ETFs are concentrated in a particular industry or sector. Adverse developments, regulatory changes, or economic conditions affecting that sector can significantly impact the ETF’s performance.

          How to Invest in Equity ETF

          Investing in an Equity ETF is very easy nowadays. An investor is required to follow the steps mentioned below:

          • Visit the Website of Pocketful: An investor is required to visit the website of Pocketful and click on the Open Demat Account tab.
          • Open a Demat Account: On the page, you are required to fill in your details and add your bank account. 
          • Login: Once your demat and trading account is opened successfully, you are required to log in to the trading application provided by Pocketful.
          • Adding Funds: You are required to add funds into your demat account so that you can purchase the Equity ETF. Funds can be added through various online methods such as UPI, NEFT, RTGS, etc.
          • Choosing the Equity ETF: There are various equity ETFs listed in the stock exchange that are offered by various mutual fund houses. One must evaluate all the ETFs and choose the best fund based on their investment goal.
          • Placing Order: Once you choose the Equity ETF, you can easily buy it on the Pocketful mobile application depending on your investment amount.
          • Periodic Review: Regular monitoring of your portfolio is required to book profit timely.

          Read Also: What Is Nifty ETF?

            Conclusion

            On a concluding note, investing in an equity ETF allows an investor to take exposure in various stocks through a single investment. Buying numerous stocks carries concentrated risk, but equity ETFs allow a diversified portfolio. There are various types of Equity ETFs available in the market, and an investor can choose any one of them based on their risk profile. However, choosing an ETF does not directly eliminate market risk; therefore, it is advisable to consult your investment advisor. 

            S.NO.Check Out These Interesting Posts You Might Enjoy!
            1What Is iNAV in ETFs?
            2What is Dividend ETF?
            3What are Bond ETFs?
            4What is a Smart Beta ETF?
            5What is Nifty BeES ETF?

            Frequently Asked Questions (FAQs)

            1. Is it mandatory to have a demat account to invest in ETFs?

              Yes, to invest in ETFs, it is mandatory to open a demat account because ETFs are traded on the stock exchange.

            2. What is tracking error in an Equity ETF?

              When the performance of a passive fund shows a difference from the performance of the underlying asset class or index, that is known as Tracking Error. It generally occurs because of factors such as expense ratio, portfolio rebalancing, etc.

            3. When can I buy and sell the equity ETFs?

              You can buy and sell the equity ETFs only during the market trading hours, that is, from 9:15 to 3:30.

            4. Among ETFs and stocks, which carries more risk?

              Individual stocks carry more risk as the investment is made in a single company. On the other hand, an ETF provides exposure to a basket of stocks, allowing an investor to diversify their fund.

            5. What are Equity ETFs?

              Equity ETFs are an investment tool that allows an investor to take exposure in a basket of stocks, and it is traded on a stock exchange like a regular share. An investor is required to have a demat and trading account to start investing

          1. What is Basis of Allotment in IPO?

            What is Basis of Allotment in IPO?

            If you’ve ever applied for a hot IPO and then spent the next few days refreshing the registrar’s website every couple of hours, you already know the feeling this article is about. There’s a strange mix of hope and dread that kicks in once the subscription window closes: did you get the shares, or is your money about to bounce back into your account? That outcome comes down to something called the basis of allotment, and it’s worth actually understanding rather than just waiting on.

            This piece walks through what the basis of allotment means, who decides it, how the whole IPO allotment process plays out, and how you can actually apply for an IPO on the platform.

            What Does Basis of Allotment Mean?

            In a nutshell, the basis of allotment (BoA) is the rulebook that decides who gets a piece of the action in an IPO and how many shares they get. And here’s the thing – it’s not a decision made by the company; it’s a very specific, SEBI-regulated process that the registrar to the issue follows to the letter, with the stock exchange (NSE or BSE) giving the final okay.

            Now, if not too many people are applying for shares – and they usually aren’t – life is simple: everyone gets what they asked for. But things get really interesting when an IPO takes off, and thousands of people are scrambling to get in on the action. That’s when the company has to have some solid, fullproof system in place to figure out who actually gets the shares. And that’s exactly what the BoA document is all about.

            You’ll usually see this document show up a few days after the IPO closes, broken down by the type of investor, showing in detail how the demand stacked up against the available shares and how the shares were eventually divided up.

            Why Is the Basis of Allotment Important in an IPO? 

            For one, it’s what keeps the process honest. When a retail portion gets oversubscribed 30 or 40 times, there’s always a lingering worry that bigger applicants somehow get an edge. Because the allotment is computerised and overseen by the exchange, that worry mostly goes away.

            It also gives investors an idea of their allotment chances. For example, if the retail category is oversubscribed 25 times, the probability of receiving shares is relatively low. 

            There’s a money angle too. Until the allotment is out, your funds sit blocked through ASBA or a UPI mandate. The BoA is what tells you whether that money turns into shares or gets released back to you, which matters if you were planning to redeploy it elsewhere.

            And sometimes, it’s simply diagnostic. If your application got rejected, it’s not always about oversubscription; a mismatched PAN or an incorrect DP ID can knock you out too. Checking the allotment status (and understanding why you didn’t make the cut) can save you from repeating the same mistake next time.

            Who Actually Decides the Basis of Allotment?

            Not the company that’s a common misconception. The job falls to the Registrar to the Issue, a SEBI-registered intermediary (names like Link Intime, KFin Technologies, and Bigshare Services come up often), working alongside the exchange where the company is listed.

            Roughly, this is how it plays out:

            The registrar first goes through every application received during the subscription period, checking PAN details, demat account information, and whether payments or UPI mandates actually came through. Anything invalid or duplicated gets filtered out at this stage. Based on the final validated numbers in each category, the registrar then works out the allotment by lottery for retail investors if oversubscribed, and a proportionate split for NII and QIB categories. The exchange reviews this before it’s made official, and only then does the basis of allotment get published.

            This two-layer check registrar plus exchange is really what gives the process its credibility. It’s not left to the company’s discretion at any point.

            Read Also: What is the IPO Allotment Process?

            How the Allotment Process Plays Out

            The approach changes depending on whether the issue is oversubscribed and which category you fall under. If the IPO is undersubscribed, nothing tricky here. Every valid applicant gets exactly what they applied for.

            If the IPO is oversubscribed, things split by category:

            • Retail Individual Investors (RIIs): Since most retail applicants go for a lot or two, a computerised lottery decides who gets in. The idea is to spread allotments across as many people as possible rather than favour those who applied for more so a bigger application doesn’t really improve your odds within the retail cap.
            • Non-Institutional Investors (NIIs/HNIs): This is where proportionate allotment kicks in. If the NII segment is oversubscribed 8 times, someone who applied for ₹8 lakh worth of shares would typically end up with around ₹1 lakh worth scaled down in proportion to the oversubscription.
            • Qualified Institutional Buyers (QIBs): Same proportionate logic applies here, no lottery involved, since this category is made up of mutual funds, banks, and foreign portfolio investors applying in bulk.

            The Math Behind Proportionate Allotment

            For categories that follow the proportionate route, the formula the registrar uses is fairly straightforward:

            Allotment Ratio = Shares Available in the Category ÷ Total Shares Applied For in that Category

            Shares Allotted = Shares Applied For × Allotment Ratio

            So if a category has 1 lakh shares reserved and applications come in for 12 lakh shares, the ratio works out to roughly 1:12 each applicant gets about a twelfth of what they applied for, adjusted for minimum lot rules.

            How the Allotment Splits Across Investor Types

            SEBI sets aside specific portions of every IPO for different kinds of investors:

            • Retail Individual Investors: typically get a minimum of 35% of the net offer, for anyone applying up to ₹2 lakh. Bidding at the cut-off price is a smart move here; it keeps your bid valid regardless of where the final price lands within the band.
            • Non-Institutional Investors (NII): get a minimum of 15%, further split into smaller NIIs (₹2 lakh to ₹10 lakh) and bigger NIIs (above ₹10 lakh), each with its own slice of the quota.
            • Qualified Institutional Buyers (QIB): can get up to 50% of the net offer, with a portion carved out specifically for mutual funds.

            Worth knowing: if one category doesn’t get fully subscribed, the leftover shares can be reallocated to categories that are oversubscribed, and occasionally, that ends up benefiting retail applicants.

            When Does the Basis of Allotment Come Out?

            IPO timelines have tightened up quite a bit over the last few years. Here’s roughly how it plays out now:

            • Closing Day (T-Day): Subscription window shuts.
            • T+1: Registrar validates applications, rejects the technically invalid ones, and works out the allotment numbers.
            • T+2: Basis of allotment is published, and refunds for unsuccessful applicants start moving.
            • T+3: Shares land in demat accounts, and the stock usually lists shortly after.

            These timelines can shift slightly issue to issue, so it’s worth checking the specific dates for whichever IPO you’ve applied to rather than assuming they’ll always match exactly.

            How to Check Your IPO Allotment Status

            A few reliable ways to check, rather than sitting around waiting for an email:

            1. Registrar’s website: All IPO has a registrar attached to it. Visit their portal, choose the IPO name and search with your PAN, application number or DP/Client ID.
            2. NSE or BSE websites: You can check allotment status in both exchanges; just select the IPO and enter your PAN and application number.
            3. Your broker’s app: most trading platforms, Pocketful included, let you check your allotment status right within the app, so you don’t have to rely between websites.

            Keep your PAN, application number, and DP ID within reach; most portals will ask for at least one of these.

            Read Also: How to Check IPO Allotment Status

            How to Apply for an IPO Through Pocketful

            If you’re applying through Pocketful, the process is designed to be quick and mostly happens within the app itself:

            1. Log in to your Pocketful account. Make sure your demat and trading account are active, and that your bank account is linked for UPI-based payments.
            2. Head to the IPO section. You’ll find a list of currently open IPOs along with key details: price band, lot size, issue dates, and category-wise subscription status.
            3. Select the IPO you want to apply for. Tap on it to view more details, including the company’s financials and the offer structure, before deciding how much you want to bid.
            4. Enter your bid details. Choose the number of lots, and either select a specific price within the band or go with the cut-off price (usually the safer choice, since it keeps your bid valid no matter where the final price settles).
            5. Enter your UPI ID. This is the ID linked to your bank account, and it’s what Pocketful uses to raise the mandate request for blocking your application amount.
            6. Approve the UPI mandate. You’ll get a notification on your UPI app (Google Pay, PhonePe, or whichever app you use); approve it before the deadline. This step trips people up more often than you’d expect, so don’t let it sit unapproved.
            7. Track your application. Once submitted, you can check your application status and, later, your allotment status directly from the IPO section in the app.
            8. Check allotment and next steps. Once the basis of allotment is out, Pocketful will show you whether you’ve been allotted shares. If you have, they’ll be credited to your demat account before listing; if not, the blocked amount gets released back automatically.

            The whole point of applying through a broker like Pocketful is that it collapses a fairly process bidding, mandate approval, and tracking into a few taps, without you needing to visit the registrar’s site at every step.

            Common Reasons Investors Don’t Get an Allotment

            Even in a fair system, a lot of applicants walk away empty-handed. Usually it comes down to one of these:

            • Heavy oversubscription: the most common reason by far. More applicants than lots simply means the lottery won’t favour everyone.
            • Duplicate applications on the same PAN: SEBI allows only one application per PAN. Applying twice, even through different brokers, gets you rejected.
            • Incorrect details: a mismatched PAN, DP ID, or bank account can invalidate an otherwise fine application.
            • UPI mandate or payment issues: forgetting to approve the mandate in time, or not having sufficient balance blocked, is a surprisingly frequent slip-up.
            • Bidding below the cut-off price: if your bid price ends up lower than the final issue price, it won’t be considered valid.
            • Same UPI ID across multiple family applications: a lot of people try to apply through several family members’ accounts but use one UPI ID for all of them, which gets flagged.

            A Few Ways to Improve Your Odds

            Applying for a spot in a super popular retail category is always a bit of a crapshoot, but there are some habits you can get into that might just give you a bit of an edge and make you less likely to get knocked out on a technicality at the very last minute

            • Instead of making one big application with all your eligible family members on the same account, try applying through multiple eligible family accounts, each with their own PAN and UPI ID. That way you spread your bets and aren’t putting all your eggs in one basket
            • In the retail category, it’s actually better to apply for single lots in different accounts rather than putting in one big application with multiple lots – the way the lottery is set up, it treats each application pretty much equally, so by breaking it down into smaller applications you stand a better chance of getting some through
            • Play it safe by sticking to the cut-off price, so you don’t run the risk of your bid being rejected because it’s too high.
            • Get your application in early rather than waiting till the last minute so you have time to sort out any payment issues that might come up.
            • Double-check – and then double-check again – your PAN, DP ID, and bank details before you hit submit
            • If you qualify for one of the shareholder or employee quotas, use that – the odds are always much better in those pools than they are in the general public pool

            Wrapping Up

            The basis of allotment is not fine print, it is the moment you know whether your IPO application turned into shares or refund. Once you understand how the registrar and exchange work together, how the lottery and proportionate methods differ in various categories and the typical problems with applications, the whole thing seems much less of a black box. The application process with Pocketful takes only a few minutes, and the waiting begins after you click submit.

            S.NO.Check Out These Interesting Posts You Might Enjoy!
            1What is IPO Lot Size?
            2How to Cancel an IPO Application?
            3What Is a Hot IPO?
            4What is Face What is the IPO Cycle
            5What is NII in IPO?

            Frequently Asked Questions (FAQs)

            1. What is the deal with allotment in an initial public offering?

              The allotment situation in an IPO is decided by the method used to sort out who gets how many shares. The registrar in charge of the IPO gets to decide this, and the stock exchange has to give it the thumbs up to make sure its all fair and square.

            2. Who actually puts the allotment plan together?

              The allotment plan is put together by the registrar company itself, like KFin Technologies, Link Intime, or Bigshare Services, and then gets a once-over by the relevant stock exchange before they publish it.

            3. When do the IPO allotments come out?

              As a rule of thumb, the basis of allotment is usually announced a couple of working days after the IPO closes for business. At that point you can go check and see if you got any shares.

            4. What happens if I don’t end up getting any shares?

              If you don’t get an allotment, then the money that was blocked from your bank just gets released back into your account; no need to do anything else.

            5. Does sending in multiple applications for more shares increase my chances of getting an allotment?

              Generally for individual investors, sending in multiple applications for more shares won’t improve your chances of getting an allotment in an oversubscribed IPO. What’s more, most retail allotments are decided by an automated lottery system for all eligible individual applications.

          2. Kelly Criterion for Stock Trading

            Kelly Criterion for Stock Trading

            If you select the right stocks but still fail to generate good long-term returns, the reason is often incorrect position sizing. This is where the Kelly Criterion and the Kelly Formula come into play. They help determine the prudent amount of your total capital to allocate to a trade. In this article, we will explore this concept using simple language, relevant examples, and a practical approach.

            What Is the Kelly Criterion? 

            The Kelly Criterion is a position sizing strategy that helps determine the appropriate portion of your total capital to allocate to a specific trade. It does not suggest which stocks to buy; instead, it assists in calculating the optimal investment amount based on your trading data.

            This concept was developed by John L. Kelly Jr. in 1956. Initially applied in information theory, it was later adopted for risk and capital management in fields such as investing and trading.

            To put it simply Suppose your trading strategy is consistently yielding good results. The Kelly Criterion helps determine what percentage of your total capital it would be prudent to allocate to a particular trade. Its objective is not to predict future stock prices, but rather to determine your position size using a scientific approach.

            Understanding the Kelly Formula 

            The most important component of the Kelly Criterion is the Kelly Formula. It helps estimate what percentage of your total capital is appropriate to invest in a single trade, based on your past trading performance. Keep in mind that this is useful only when you have sufficient trading data.

            Kelly Formula: Kelly % = W − [(1 − W) ÷ R]

            Terms used in the formula

            • W (Win Rate): The proportion of total trades that resulted in a profit.
              Formula: Win Rate = Winning Trades ÷ Total Trades
            • R (Reward-to-Risk Ratio): The ratio of the average profit from a successful trade to the average loss.
              Formula: Reward-to-Risk Ratio = Average Profit ÷ Average Loss
            • Kelly %: This indicates what percentage of your total trading capital can be allocated to a single trade.

            Note: The Win Rate and Reward-to-Risk Ratio used in the Kelly Formula should always be based on your actual trading record or sufficient backtesting data. Calculations based on estimated figures may not yield accurate results.

            How to Calculate the Kelly Criterion 

            Suppose the record of your last 100 trades is as follows.

            DescriptionValue
            Total Trades100 
            Successful Trades60 
            Losing trades40
            Average profit₹6,000
            Average Damage₹4,000

            Step 1 Calculate the Win Rate

            Win Rate = 60 ÷ 100 = 0.60 (60%)

            Step 2 Calculate the Reward-to-Risk Ratio

            R = ₹6,000 ÷ ₹4,000 = 1.5

            Step 3 Apply the Kelly Formula

            Kelly % = 0.60 − [(1 − 0.60) ÷ 1.5]

            • = 0.60 − (0.40 ÷ 1.5)
            • = 0.60 − 0.2667
            • = 0.3333

            Kelly Percentage = 33.33%

            Based on this example, the Kelly Formula indicates that if your trading strategy’s performance remains consistent in the future, you could theoretically invest up to approximately 33% of your total capital in a single trade. However, in practice, most experienced traders opt for “Half Kelly” (around 16.5%) or “Quarter Kelly” (around 8.25%) instead of utilizing the full Kelly percentage, as this allows for better control over risk and portfolio volatility.

            Read Also: Formulas used to Calculate Profit and Loss in Nifty Options

            Why Position Sizing Matters More Than Picking Winning Stocks 

            Merely selecting the right stock does not guarantee successful trading. If the investment amount is not determined correctly, even a promising trade may fail to yield the expected results.

            • A single wrong decision can impact the entire portfolio: If excessive capital is allocated to a single trade, even a moderate loss can significantly affect the portfolio’s overall returns. Therefore, maintaining a balanced investment approach for every trade is essential.
            • Not every trade carries the same level of risk: Trades vary in nature; some entail lower risk, while others involve higher risk. Position sizing helps determine the investment amount by taking these differences into account.
            • It helps preserve capital over the long term: Losses are a normal part of trading. By employing the right position size, your capital remains intact even after a series of losses, allowing you to capitalize on future opportunities.
            • It fosters a habit of disciplined trading: When every trade is executed according to pre-defined rules, the likelihood of making emotional decisions driven by greed or panic is minimized. This leads to a more systematic approach to trading.
            • The Kelly Criterion offers a solution to this challenge: The Kelly Criterion helps estimate the optimal portion of your total capital to allocate to a trade based on your past trading performance. Its objective is to determine the appropriate position size, rather than to recommend which stocks to buy.

            Full Kelly vs Half Kelly vs Quarter Kelly 

            Not every trader wants to take the same level of risk. That is why the Kelly Criterion is applied in different ways. Most professional traders prefer Half Kelly or Quarter Kelly over the full Kelly approach, as this can reduce the risk of significant volatility and drawdowns.

            MethodCapital AllocationRisk LevelBest For
            Full KellyInvest the entire amount corresponding to the percentage derived from the formula.High Experienced traders with robust backtesting and consistent performance data.
            Half Kelly50% of the percentage obtained from the Kelly Formula.Moderate Swing traders and active traders who seek a balance between risk and return.
            Quarter Kelly25% of the percentage obtained from the Kelly Formula.Low New traders or conservative investors who prioritize capital preservation.

            Example: If the result of the Kelly Formula is 20%, then

            • Full Kelly: 20% capital investment
            • Half Kelly: 10% capital investment
            • Quarter Kelly: 5% capital investment

            When Should You Use the Kelly Criterion? 

            The Kelly Criterion is not equally useful in every trading situation. It works best when you have reliable data on your trading strategy and make decisions based on that data.

            SituationShould You Use It?Reason
            Rule-Based Trading StrategyYes In a strategy with defined rules, it is easy to measure the win rate and the reward-to-risk ratio.
            Backtested Trading SystemYes Using the Kelly Formula based on historical data obtained from backtesting can be more reliable.
            Trading Journal with Enough RecordsYes When sufficient trading history is available, the calculation is based on actual performance.
            Quantitative or Systematic TradingYes It is considered more effective in trading based on data and statistical analysis.
            Random Stock SelectionNoIt is not possible to accurately estimate the win rate and risk-reward ratio without a clear strategy.
            New Traders with Limited Trade HistoryNoThe result of the Kelly Formula may not be reliable due to limited trading data.

            Advantages of Using the Kelly Criterion 

            The objective of the Kelly Criterion is not merely to determine position size, but also to make trading decisions more systematic and data-driven.

            • Aids in better capital allocation: It helps prevent the allocation of an excessive amount of available capital to a single trade.
            • Facilitates data-based decision-making: The Kelly Formula performs calculations based on your trading history rather than relying on guesswork.
            • Provides a clear framework for every trade: It helps determine how to set position sizes, leading to more systematic decision-making.
            • Can be used with various trading strategies: If the win rate and risk-reward ratio for a strategy are known, the Kelly Criterion can be applied to it.
            • Strengthens long-term risk management: When used correctly, it helps manage capital more systematically, making it easier to sustain trading over the long term.

            Limitations of the Kelly Formula 

            Like any position sizing method, the Kelly Formula has certain limitations. Therefore, it should be used judiciously and in conjunction with other risk management rules.

            • Relies on accurate data: The Kelly Formula is useful only when you have sufficient and reliable trading data. If the win rate or reward-to-risk ratio is incorrect, the result will also be inaccurate.
            • Does not guarantee future results: This formula performs calculations based on past performance. There is no guarantee that future results will mirror the past, especially amidst changing market conditions.
            • May suggest large position sizes: In certain situations, the Kelly Formula may suggest a relatively large position size. Consequently, many experienced traders use “Fractional Kelly” instead of “Full Kelly” to keep risk levels lower.
            • Not always suitable for new traders: If you have executed very few trades or your strategy is not yet stable, it is better to build a sufficient trading track record before using the Kelly Formula.
            • Not a substitute for risk management: The Kelly Formula only helps in determining position size. For successful trading, other principles such as stop-loss orders, diversification, and proper risk management are equally essential.

            Kelly Criterion vs Fixed Percentage Position Sizing 

            The objective of both position sizing methods is to control risk, but they operate differently. The Kelly Criterion determines position size based on trading data, whereas Fixed Percentage Position Sizing involves risking a predetermined percentage on every trade.

            Kelly CriterionFixed Percentage Position Sizing
            It is based on the win rate and the reward-to-risk ratio.A pre-determined risk (such as 1% or 2%) is taken in every trade.
            Position size may vary based on trading data.The position size is determined according to established rules.
            Sufficient trading history is required.It can be easily adopted even without historical data.
            It focuses on data-based position sizing.It is a popular method for simple risk management.
            It is a bit complex and requires calculations.It is relatively easy to understand and implement.

            Common Mistakes Traders Make While Using the Kelly Criterion 

            The Kelly Criterion is useful only when the correct information and approach are employed. Certain mistakes are frequently observed in this regard:

            • Applying the same formula to every strategy: The Kelly percentage derived for one strategy cannot be applied to another; each strategy performs differently.
            • Failing to update calculations: If your trading performance has changed, determining position sizes based on outdated calculations is not advisable.
            • Ignoring the possibility of significant drawdowns: Some traders focus solely on potential returns, whereas it is crucial to understand the impact on capital during a streak of losses.
            • Overlooking market conditions: Just because a strategy has performed well in the past does not mean it will yield similar results under all market conditions.
            • Investing beyond your risk capacity: Regardless of the percentage suggested by the formula, it is always best to determine position sizes based on your own risk-bearing capacity.

            Read Also: Understanding Futures Pricing Formula

            Conclusion

            The Kelly Criterion is a useful method for determining the correct position size, but it is effective only when you have reliable trading data. Use it in conjunction with your trading strategy and risk management, rather than as a standalone tool for making decisions.

            S.NO.Check Out These Interesting Posts You Might Enjoy!
            1What are Bond Valuation?
            2Commodity Channel Index (CCI): Meaning, Formula, Calculation & Trading Strategy
            3Silver Futures Trading – Meaning, Benefits and Risks
            4Interest Coverage Ratio (ICR): Formula, Meaning, Calculation & Uses
            5What Is Day Trading and How to Start With It?

            Frequently Asked Questions (FAQs)

            1. What is the Kelly Criterion?

              The Kelly Criterion is a position sizing method that indicates the appropriate amount to invest in a trade.

            2. What is the Kelly Formula used for?

              The Kelly Formula is used to determine the appropriate position size for a trade.

            3. Is the Kelly Criterion suitable for beginners?

              Yes, but sufficient trading data is required for better results.

            4. Does the Kelly Formula guarantee profits?

              No, it only helps in determining the position size.

            5. Why do traders prefer Half Kelly?

              Because it results in relatively lower risk and portfolio volatility.

          3. Open Free Demat Account

            Join Pocketful Now

            You have successfully subscribed to the newsletter

            There was an error while trying to send your request. Please try again.

            Pocketful blog will use the information you provide on this form to be in touch with you and to provide updates and marketing.